


Indonesia's Housing Loans Grow At 5%. Bad Loans Sit Well Above Their Long-Run Average


|
HONG KONG, Nov 19, 2026 - (ACN Newswire) - Mortgage NPL hit 3.35% in May 2026 while loan growth cooled to 4.99% - the construction-cost squeeze behind Indonesia's rising credit risk 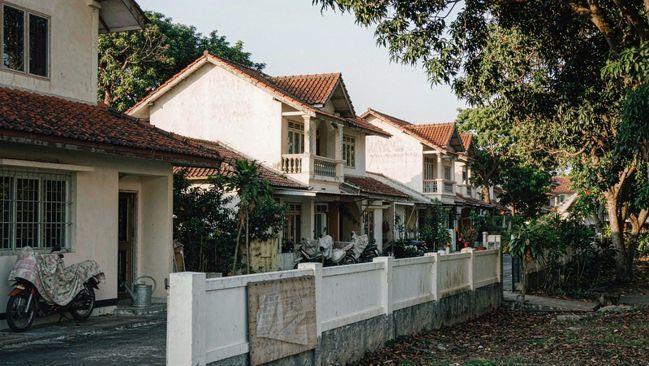 Indonesia's housing credit is still expanding. The quality of that credit is moving the other way. Bank Indonesia's monthly financial statistics, tracked on CEIC, put growth of landed-house mortgage loans at 4.991% year on year in May 2026, and growth of all real-estate loans at 4.505%. Both are respectable numbers by regional standards. The same series shows the non-performing ratio on real-estate loans reaching 3.350% in May, up from 3.257% in April, against a long-run average of 2.890% since 2014. The tension sits in the combination. Fast credit growth usually dilutes a bad-loan ratio, because the denominator grows faster than the defaults. Slow growth usually exposes it. Indonesia is running the uncomfortable middle case: growth above 4.5%, defaults climbing anyway. The NPL series bottomed at 2.017% in December 2022. It has risen more than 1.3 percentage points in about three and a half years. The mechanism, as this article reads it: a cost squeeze and a rate squeeze are hitting housing developers first, and the stress is now working through to the borrower side. Shophouse mortgages - loans that mix business and property risk - have already crossed the 4% line, at 4.070% in April. Landed-house mortgages, the larger and more policy-sheltered book, are following with a lag. The numbers, segment by segment The Bank Indonesia series breaks the property loan book into segments, and the segments do not tell one story.
Source: CEIC (Bank Indonesia data) Three readings come out of the table. First, the small-house segment - the 22–70 m2 band where most subsidised demand sits - is growing fastest at 5.992% while carrying an NPL of 3.220%. Policy-supported demand is holding up the volume. Second, the big-house segment grows slowest at 3.429%, consistent with affordability limits at the top of the market. Third, the shophouse book is the outlier on quality: 4.070% in April, up from 4.090% in March, roughly a full point above the landed-house ratio. The landed-house NPL did tick down from 3.308% in May to 3.271% in June. One month is not a trend. Banks retire or restructure bad loans in batches, and a single month of improvement inside a three-and-a-half-year climb says little. The working assumption here is that the upward drift continues until several months of data say otherwise. How this cycle differs from the last The current series has a usable history, and the shape of the previous cycle puts the present one in focus. The full NPL series, running since January 2014, peaked at 3.493% in July 2020 - the pandemic shock, when loan growth collapsed and defaults were recognised in a burst. The series low before this cycle was 2.207% in December 2014. The current reading of 3.350% sits 0.143 percentage points below that pandemic peak. The difference is the shape, and the shape matters for what happens next. In 2020 the ratio spiked because the denominator shrank: lending froze, and the existing stock of bad loans suddenly weighed more. Nothing about that pattern suggested deep borrower distress unique to housing; it was the credit cycle seizing everywhere at once. The current move is slower and carries different information. Loan growth is still positive at 4.5–5%, so the denominator is not doing the damage. The numerator - the actual stock of non-performing loans - is growing on its own. A ratio that climbs while lending expands means new defaults are being generated faster than the growing book can dilute them. That is a borrower-level deterioration, not a statistical artefact. It also means the ratio can accelerate. If loan growth keeps cooling toward the rate at which defaults accumulate, the ratio moves faster; the 2020 peak is not a natural ceiling, and the three-quarters-of-a-point distance to 4% can close in well under a year at the current drift. The cost side: margins compressed while the price ceiling froze The supply side of Indonesian housing has been squeezed for over a year, and the squeeze is documented in detail by developers' own associations. The Jakarta Post reported in June 2026 that builders of subsidised housing were warning that the business had become financially untenable. The Himperra association called for an urgent adjustment of the government's benchmark selling price, arguing that the pricing formula no longer reflected economic reality. The benchmark price was last revised in 2024. One association figure quoted the shift bluntly: 2026 brought not a simple price increase but a change in the cost structure itself. Rising fuel prices had set off a chain reaction, and the weakening rupiah inflated logistics expenses and the cost of imported raw materials. The volume numbers behind those complaints are measurable. Indonesia's construction cost index rose 8.1% year on year in April 2026, against 0.8% a year earlier, according to BPS data reported by the Jakarta Post. Costs grew ten times faster than they did a year before, while the price developers are allowed to charge for a subsidised house stayed where the government set it in 2024. The Jakarta Post reporting also captured what the squeeze does to behaviour. For many subsidised-housing developers, accelerating the disbursement of financing has become the only way to stay afloat - pulling cash forward from buyers and banks to cover today's costs. That is survival behaviour, and it has a quality cost. A developer booking revenue on delivery schedules it cannot meet, or discounting to move stock, is borrowing margin from the future. The sector's cash-flow strain therefore shows up in the loan book with a delay: the 2026 cost shock lands in 2026–2027 instalments. The transmission chain from this table to the mortgage book is short. A developer whose margin disappears does three things in sequence: slows down new starts, stretches payment to suppliers, and delays delivery on signed contracts. A buyer waiting for a delayed house is a borrower paying instalments on something they cannot yet use. Some of those instalments stop. That is how a construction-sector cost problem becomes an NPL problem with a lag of several quarters. The rate side: borrowing costs moved up while the currency dictated policy On 20 May 2026, Bank Indonesia raised its benchmark rate by 50 basis points to 5.25%, the first increase since April 2024, after holding at 4.75% for seven months. The central bank framed the move as a defence of rupiah stability and its inflation band, following a period of currency pressure. Mortgage pricing in Indonesia follows the policy rate with a lag, but the direction is set: variable-rate KPR holders and new borrowers both face higher instalments than they did in early 2026. The comparison with the rest of the banking system makes the housing slowdown sharper. OJK figures reported through IDN Financials put total bank credit growth at 9.98% year on year in April and 11.51% in May 2026. Housing loans growing at roughly 4.5–5% are running at less than half the speed of the system. Bank liquidity is not the constraint: the OJK data show liquid assets at 24.74% of third-party deposits, well above the 10% regulatory floor. The money exists. What has changed is the risk-return arithmetic on housing credit specifically - developers with compressed margins are weaker counterparties, and household repayment capacity is being tested by the same cost pressures. Where the stress shows first The segment table carries a warning that is easy to miss. Shophouse mortgages crossed the 4% NPL line before the residential book did. Shophouse loans sit at the intersection of property and small-business finance. The borrower typically services the loan from shop revenue, not from a salary. When construction costs push up the price of stock, fittings and rent, the small merchant's margin compresses first, and the shophouse mortgage feels it before any household book does. The 4.070% April reading is consistent with that ordering: the commercial-adjacent segment breaks the 4% line while the landed-house segment, at 3.308%, approaches it. The ordering also explains why the shophouse line is worth watching as a leading indicator rather than a separate story. Small merchants have thinner reserves than households, no payroll to fall back on, and revenue that moves with local foot traffic. A household behind on a mortgage still has wage income to draw on; a shopkeeper behind on a shophouse loan has inventory. When the cost index runs at 8.1%, that inventory costs more to replace every month, and the gap between revenue and obligations widens first for the borrower whose income is a business. The residential book follows the same cost curve with the cushion of wages, which is slower to break. The 22–70 m2 residential band deserves its own note. It is growing fastest ( 5.992% ) and carries an NPL of 3.220%, slightly below the landed-house average. That looks reassuring. It is partly a mix effect: the newest loans in the band are young, and young loans have not yet had time to default. Long-tenor lending front-loads growth and back-loads risk. A book growing at 6% with long maturities will show its true quality several years out, which is why the current 3.220% should be read as a floor, not a verdict. The policy counterweight, and its limits The bullish case for Indonesian housing credit rests on policy, and the policy is real. Bank Indonesia has been scaling up its macroprudential liquidity incentive scheme, known as KLM, which lets banks hold fewer required reserves against lending to priority sectors including housing. The mechanics are worth spelling out, because the scheme is not a rate cut. Banks in Indonesia must park a share of customer deposits as reserves at the central bank. Under KLM, the share they must park shrinks when the lending goes to designated sectors - housing, real estate and construction among them. The released reserves become lendable funds, which lowers the effective cost of a housing loan without the central bank touching its benchmark rate. Housing, real estate and construction carry a dedicated sub-cap of 1.4% of third-party funds, of which banks were using 1.32%. A separate inclusion-oriented channel, RPIM, pushes banks toward low-cost mortgages for lower-income households. The cap itself rose to 6% of third-party funds, effective September 2026, from 5.5% in August. According to Bank Indonesia figures cited in industry reporting, the scheme supported 115,927 new commercial mortgages totalling Rp683.5 trillion, about US$4.3 billion, between April 2025 and July 2026. On top of this, qualifying borrowers can access loan-to-value ratios up to 100%, removing the down-payment requirement entirely. The central bank has also kept its coordination with the housing ministry visible at governor level, a signal that the incentive channel is meant to stay open. This is the counter-evidence case stated on the card: if policy loosening lifts transactions, the NPL ratio's denominator grows and the ratio can stabilise without any loan actually performing better. Two forces are pushing in opposite directions at once. The limits are equally concrete. A 100% LTV loan strips out the borrower's own buffer, which historically is the first loss-absorbing layer. The KLM channel lowers banks' funding cost for housing credit without touching the benchmark rate, so it softens the supply of credit while the May rate hike is hardening its price. And the incentive's dedicated housing headroom - 0.08 percentage points between current use and the cap - is not large. If the cost squeeze on developers continues, policy can slow the deterioration; it cannot reverse the arithmetic of a builder who cannot build at the capped price. What would confirm or break the judgment The falsifiable condition on this theme is explicit: if the mortgage NPL breaks 4% within a year, the debt-service stress reading is confirmed. The shophouse book has already crossed that line, at 4.070%. The landed-house book, at 3.271% as of June, sits about three-quarters of a point below it and has been climbing for roughly three and a half years. Three markers are worth tracking, none of which requires privileged data. The monthly NPL series on CEIC, where a printed 4% on the landed-house line settles the question. The KLM usage ratio, where movement from 1.32% toward the 1.4% cap would show banks pulling the policy lever at full force. And the government's response to the developers' price-adjustment requests, which as of the June reporting remained unanswered - an approved increase would relieve the supply-side squeeze at its source. The judgment breaks the other way if the landed-house NPL falls for three consecutive months while segment growth climbs back above 6%. That combination would say the policy counterweight is working through the denominator, and the stress reading would need to be revised. What this means for builders and suppliers The risk concentration is not where headlines usually put it. Bank Indonesia's own liquidity data show the banking system carrying abundant reserves, and housing is a small share of total credit growing at 11.51%. The stress sits one layer down: small and mid-sized developers with capped selling prices, and the building-material suppliers carrying their receivables. For businesses exposed to the sector, the asymmetry points toward the subsidised supply chain. Small-ticket housing is where the policy money is directed - the KLM sub-cap, the subsidised lending programmes, the transaction-support schemes - and where volume is most defensible when the market cools. The high-end segment grows slowest in the current data and carries no dedicated policy support. Suppliers and contractors choosing between the two books are, in effect, choosing between a policy-backed flow and a discretionary one. For banks, the KLM mechanism is a transfer of reserve cost into mortgage yield, and its remaining headroom is thin. The usage ratio's path over the next two quarters will show whether the incentive is actually binding on lending decisions or already priced in. Limitations
Sources
|
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment