


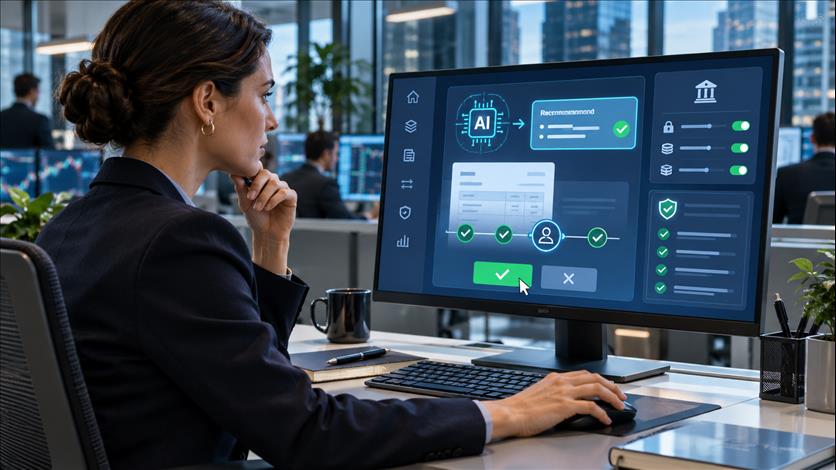
The Record Behind An AI-Proposed Fund Payment


| Stage | Responsibility |
|---|---|
| 1. AI proposes | Matches the $240,000 invoice and prepares an instruction. A proposal is not authorization. |
| 2. Fund checks | Independently verifies changed bank details and obtains required approvals. Holds release while verification is missing. |
| 3. System records | Enforces the fund's decision and records whether the instruction was actually executed. |
Suppose the fund's policy requires independent verification whenever a beneficiary's bank details change. It also requires two authorized people to approve payments above a specified threshold. An agent cannot waive either requirement because a supplier's message sounds urgent.
The correct next step is to hold the proposed instruction until the required checks and approvals are complete. The fund's own payment gateway or workflow applies that hold. The agent does not become the approver, and the evidence system does not inherit the fund's authority.
That distinction matters even when the control works. Six months later, an operations reviewer should not have to infer that a payment was stopped from a chat transcript saying,“Escalated to finance.” The reviewer needs a record connecting the proposed instruction, the control response, the human decision and the gateway's execution status.
A hold is a control decision. A rejection is a human or policy decision. Neither, by itself, proves that no money moved. That last fact must come from the execution system.
Follow one instruction from beginning to endA useful record for this example has six connected parts.
First, capture the proposal. Identify the amount, currency, invoice, supplier, beneficiary details, destination account reference and the agent or workflow version. Preserve the evidence the agent used. Sensitive data belongs in the fund's approved storage and access controls, not in a broadly shared transcript.
Second, identify the applicable policy. Which version was in force? What triggered beneficiary verification? What approval threshold applied? A link to today's policy is not enough if the rules have changed since the decision.
Third, record the disposition. The checks identify the changed beneficiary and return a hold. Keep the reason and the evidence supporting it. Do not substitute a new model-generated explanation for the actual decision basis.
Fourth, preserve human authority. Who was authorized to verify the supplier's change, and who could approve the payment? The verification should use an independently established contact route, not simply the number or link supplied in the change request. The record should show the evidence available to the reviewer and the action that reviewer took.
Fifth, capture the outcome. In our example, the supplier cannot be independently verified that afternoon. The reviewer declines release pending verification. The payment gateway records that the instruction was not executed. Connect that response to the same instruction identifier so an auditor is not comparing unrelated events.
Sixth, support later review. An authorized reviewer should be able to verify the integrity of the record and reconstruct the recorded evaluation using the captured inputs and matching policy and software versions. This is not asking today's language model to recreate yesterday's answer.
What changes when the supplier is verified?The next morning, the fund confirms the change through its established supplier contact. That does not make yesterday's blocked instruction an approved payment retroactively.
The workflow should preserve the earlier hold and create a distinct continuation or new instruction, linked to the original. It should capture the new verification evidence, the required approvals and the actual execution response. A reviewer can then follow the whole sequence: proposed, held, verified, approved and executed.
This also avoids a misleading success metric. An agent that completed the invoice matching did useful work. It did not complete the payment until the fund's controls and execution system did their parts. Measuring those stages separately lets operations teams distinguish productivity from unauthorized action.
Verification and replay answer different questionsA signed record can help establish whether recorded content has been altered and whether it was signed by the expected key. It does not prove that the original inputs were true or that an authorized person made a wise decision.
Replay is a separate test: can the recorded evaluation be reproduced from the inputs and versions retained at the time? A successful replay supports investigation of the decision process. It is not a compliance certificate, a legal conclusion or proof that the payment was appropriate.
Funds should ask both questions. They should also test the link to enforcement. A correct hold disposition that a gateway ignores is not an effective payment control. The record needs to preserve that failure rather than label the workflow safe because one component returned the right answer.
How evaluation, optimization and governance fit togetherFor a hedge fund, the need is practical: a payment instruction or other high-consequence action must stay within the fund's rules even when an agent produces a fluent explanation. The fund keeps its approval authority and responsibility for execution.
Evaluation and optimization address different parts of that workflow. Evaluation compares behavior as models or workflow versions change, helping reviewers identify drift or upgrade-related changes rather than assuming yesterday's tests still describe today's system. Optimization recommends workflow changes intended to improve performance or reduce cost; a person approves those changes. Governance then applies the fund's action rules to proposed instructions. Together, these paths connect the question“Has behavior changed?” to“What should we improve?” and“Is this particular action allowed?” A cheaper workflow does not earn permission to skip beneficiary verification, and a good evaluation result does not authorize a payment.
The replayability artifact gives the evaluator recorded cases to test model or workflow changes. Reviewed failures inform evaluation and optimization; changes can be compared for performance and cost under the same controls. Savings should be measured without weakening governance or confusing cheaper models with payment authority.
That institutional context is also why Forge has brought in Declan Sheehy as Senior Advisor, Financial Services. His background includes 18 years at HSBC Alternative Investments in operations and technology. He now leads One Blackwater, advising regulated financial-services firms on technology selection and AI oversight. For hedge-fund readers, his relevance is the operational side of adoption: how a fund evaluates a technology vendor, assigns control ownership and puts oversight into the work, rather than treating AI governance as a separate presentation. His Forge advisory role is an affiliation, not an independent endorsement.
A practical test for the operations teamBefore expanding an agent's payment role, run one instruction through an approved test environment and ask:
-
Can we distinguish proposal, disposition, approval and execution?
Can we identify the exact policy and system versions used?
Is the approver's authority clear, including approval limits?
Does missing verification lead to a safe outcome?
Does the gateway enforce the disposition, and is its response captured?
Can an independent reviewer examine the record without relying on the original operator's memory or the agent's explanation?
Test exceptions, not only the easy path. Change beneficiary details. Remove required evidence. Reuse an old approval on a new instruction. Check whether the workflow preserves the problem and prevents an unsupported release.
The goal is not to create another dashboard or collect every possible log. It is to preserve enough connected evidence to answer a concrete question: why was this particular instruction allowed, held or refused, and what did the fund actually do?
As AI agents take on more operational work, the fund keeps responsibility for its rules, approvals and execution. Accountability means being able to show how that responsibility was exercised, one decision at a time.
SourcesOriginal article: Brittany Istenes, Forge Orbital, October 1, 2026.
[1] U.S. Treasury, February 19, 2026.
[2] Financial Stability Board, Sound Practices for Responsible Adoption of Artificial Intelligence (AI): Final report, October 15, 2026.
About the authorsBrittany Istenes serves as Chief Trust & Ecosystem Officer and Executive Advisor to Forge Orbital. Her work focuses on the connection between technology, institutional trust and financial-services adoption.
Joseph Varga is the founder and CEO of Forge Orbital, an accountability layer for AI agents and a member of NVIDIA Inception. His background includes executive leadership in deep tech, enterprise go-to-market work and three years in defense technology.
The payment example used in this article is hypothetical. This article is intended as operational commentary and should not be interpreted as legal, compliance, regulatory, or investment advice.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment