


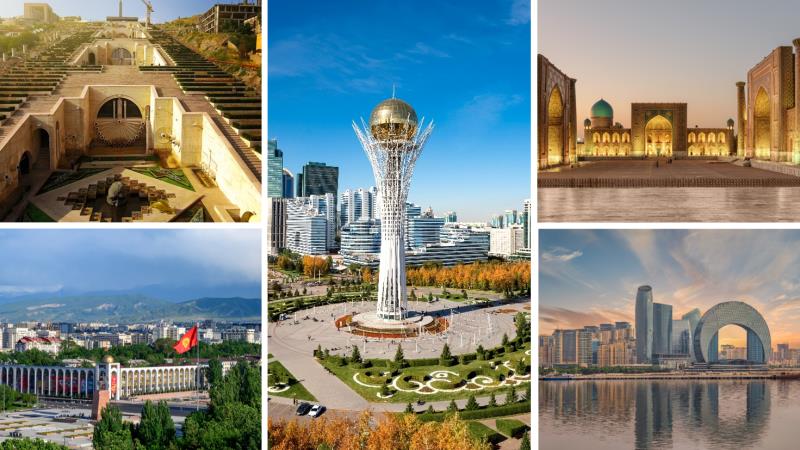
CCA Macro And Credit: Stronger Credits, More Selective Opportunities


The CCA has stood out for its improving sovereign ratings despite a series of external shocks. Stronger balance sheets, economic reforms and greater political stability have supported upgrades and reduced perceived risk. But markets have moved ahead of the rating agencies: 5Y USD spreads already imply ratings at least one notch above current levels across the region. Further upgrades may therefore have less effect on bond prices, particularly in countries where spreads are already tight.
Kazakhstan and Azerbaijan already have strong investment-grade profiles, leaving less room for further spread tightening. Uzbekistan remains our preferred sovereign credit, with reforms, fiscal discipline and privatisation creating room for further rating improvement and a broader investor base. Armenia looks more vulnerable to disappointment: positive rating outlooks sit alongside twin deficits and continued reliance on external inflows. Kyrgyzstan 's recent upgrade shows that the positive rating momentum is spreading beyond the region's more established sovereign credits.
Macro: Resilient, but increasingly divergentOur 2027 calls remain constructive on growth and currencies, but sources of resilience differ. High core rates are manageable while domestic real rates, sovereign buffers and capital inflows hold up, but a potential portfolio flow reversal is a risk.
-
Armenia: Benefits from strong inflows and progress in the peace process, although twin deficits and an expensive currency leave less room for disappointment.
Azerbaijan: Exceptional sovereign assets and high oil prices protect the peg, while weak oil production and limited diversification constrain growth.
Kazakhstan: Combines high real rates and better market access with persistent twin deficits and greater sensitivity to foreign portfolio flows.
Kyrgyzstan: Rapid infrastructure-led growth and an improving sovereign rating are offset by overheating, opaque external flows and growing state-led investment.
Uzbekistan: Combines high real rates, privatisation inflows and potential recovery of gold exports, but overheating and twin deficits prevent a structural appreciation call.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment