


ASEAN Is More Supply-Chain Battleground Than Strategic Bloc


Washington and Beijing are no longer competing only for diplomatic influence, military access or market share. They are trying to shape the industrial systems on which future power will rest: semiconductors, artificial intelligence, critical minerals, batteries and data infrastructure.
In Southeast Asia, that contest is playing out in factories, investment decisions and national development plans.
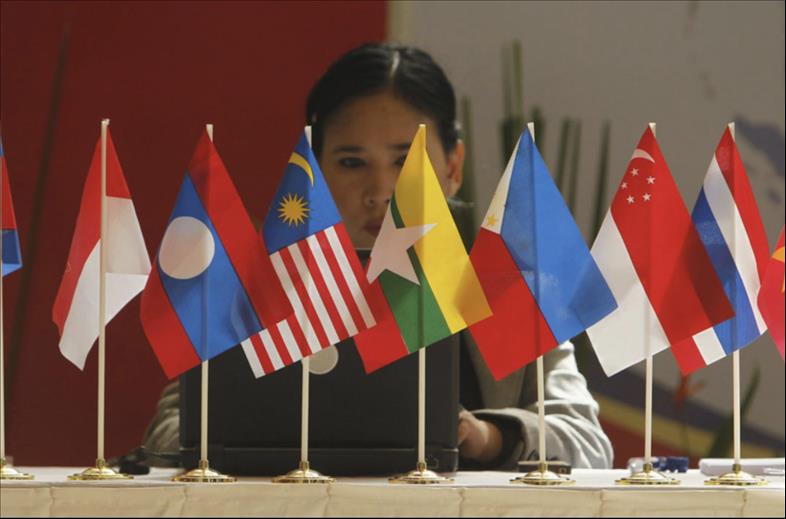
ASEAN leaders are holding a special summit with the United States, even as China remains the bloc's largest trading partner. But being courted by rival powers is not the same as setting the terms of their engagement. The question is whether ASEAN can turn its place in global production into collective leverage, or whether its members will continue to negotiate their dependencies one by one.
The numbers show why the region matters to both superpowers. ASEAN drew a record US$246 billion in foreign direct investment in 2025, up 10% from a year earlier and about 15% of global inflows. Two-way merchandise trade with China reached $913 billion.
Trade in goods with the United States totaled $550.5 billion, while US trade in goods and services with ASEAN came to $686 billion. The figures use different accounting scopes, but both underscore the region's exposure to great power rivalry.
A chip shortage, a mineral export ban, a tariff escalation or a change in data rules can reverberate through production networks. The openness that attracts manufacturers also leaves Southeast Asia vulnerable to decisions made elsewhere.
Integration has brought opportunity, but not the capacity to manage shared risks; it has advanced faster than the institutions needed to coordinate industrial strategy, technology policy and economic security.
Great-power competitionThe US-China rivalry increasingly centers on industrial ecosystems rather than individual markets. Washington is using export controls, subsidies, investment screening and initiatives such as Pax Silica to secure trusted networks for advanced chips, AI infrastructure and critical minerals.
Beijing retains commanding positions in manufacturing, processing and the components that technology and clean-energy industries depend on. Both are using economic tools to pursue strategic goals.
Critical minerals show how concentrated these networks have become. The International Energy Agency reports that the three largest refining countries' average share across key energy minerals rose from 82% in 2020 to 86% in 2024.
Latest stories Hasina must return via extradition, not on her own terms Uncomfortable question at heart of Europe's identity crisis Anthropic IPO: the age of miracles, priced at $78 a shareNearly 90% of supply growth came from a single leading supplier in each case: Indonesia for nickel, and China for cobalt, graphite and rare earths. Diversification is a strategic priority, but it also makes producers and processors targets of geopolitical pressure.
Semiconductors reveal a different imbalance. ASEAN accounts for more than 20% of global back-end operations, including assembly, testing and packaging, but less than 10% of front-end work such as research, design and wafer fabrication. Singapore and Malaysia hold stronger positions in advanced segments. The region is deeply embedded in the industry, but its hold on high-value functions is uneven.
Pax Silica is Washington's effort to build a network of partners around strategic technologies and supply-chain security; it is not an ASEAN-wide initiative. Singapore and the Philippines have joined.
The United States has said it will announce nothing major at the Manila summit on a proposed Pax Silica economic security zone in the Philippines, because negotiations are continuing. For now, the initiative is advancing through selective partnerships, and its implications for regional integration remain unclear.
Divergent dependenciesThe phrase“ASEAN supply chain” obscures more than it explains, because the region is not a single production system. Singapore is a hub for finance, logistics and advanced manufacturing. Malaysia has a substantial semiconductor base.
Vietnam is a major manufacturing center, and Thailand is tied to automotive networks. The Philippines pairs an electronics industry with close security ties to Washington. Indonesia's strategic weight rests partly on nickel and batteries.
These differences shape national calculations. Indonesia's nickel-processing expansion is closely linked to Chinese capital and technology, even as Jakarta courts Western markets and investment.
Malaysia and Singapore want ties to American-led semiconductor ecosystems while preserving commercial links with China. The Philippines' security relationship with Washington makes its choices different, and Vietnam is diversifying its manufacturing without abandoning deep trade ties to China.
That variation is not a flaw in itself. Hedging and diversification are rational for states operating amid uncertainty. The trouble comes when national strategies are not matched by regional coordination.
If members negotiate separately over minerals, data infrastructure, chip investment, export controls and market access, ASEAN's collective bargaining power will be difficult to mobilize.
Nor does the bloc's trade pattern suggest that integration can offset external dependence. Intra-ASEAN trade made up 21.4% of the total in 2024, according to ASEAN Key Figures 2025.
That does not mean integration has failed: cross-border production relies on outside inputs, and trade shares cannot capture every supply-chain link. But the region's fortunes remain tied to external markets and suppliers.
Its production networks are regional in geography but global in ownership, technology and demand.
Connectivity without collective powerThe deeper weakness is the gap between economic connectivity and collective economic power.
ASEAN has built trade agreements and diplomatic mechanisms. The signing of the Digital Economy Framework Agreement in Manila is a meaningful step toward common rules for digital trade, and it shows that members can still negotiate shared frameworks.
But digital integration alone cannot resolve differences in industrial capacity, infrastructure, energy, technology ownership or exposure to external controls.
Diplomatic centrality and strategic leverage are different things. ASEAN can convene major powers, keep dialogue open and resist formal alignment. But convening is not the same as setting conditions. Leverage requires coordinated investment priorities, stronger regional suppliers, pooled bargaining power and common standards.
For Indonesia, the point is concrete. Its nickel industry illustrates both opportunity and constraint: the country is central to global supply growth, yet much of its downstream ecosystem is tied to Chinese industrial networks.
The answer is not to replace one partner with another but to deepen technological capacity, broaden sources of investment, expand local suppliers and secure multiple markets. Without those capabilities, control of a resource can coexist with dependence.
Sign up for one of our free newsletters-
The Daily Report
Start your day right with Asia Times' top stories
AT Weekly Report
A weekly roundup of Asia Times' most-read stories
Across the bloc, Malaysia's semiconductor ambitions, Vietnam's manufacturing expansion, Singapore's technology ecosystem and the Philippines' electronics industry could complement one another. That would require regional planning for skills, energy, transport, research, standards and suppliers, not simply competition to attract factories.
ASEAN does not have to choose between Washington and Beijing, but it should not mistake strategic autonomy for neutrality on every issue. Its task is to ensure that engagement with both powers builds regional capabilities rather than deepening fragmented dependencies. That means treating supply-chain resilience as a collective agenda rather than a collection of national investment campaigns.
The Digital Economy Framework Agreement offers one platform, but the agenda must reach further. ASEAN could coordinate critical-mineral policies, map vulnerabilities, develop regional suppliers, align investment incentives and negotiate common principles for data and technology partnerships. External agreements should widen the bloc's options, not create new monopolies of dependence.
ASEAN's centrality can no longer be measured only by the summits it hosts or the declarations its leaders issue. It must also be judged by whether the region can shape the terms on which capital, technology and production enter its economies.
The bloc's greatest vulnerability is not exposure to American or Chinese power as such, but the risk that its members will face that power separately, without the institutions or industrial capabilities to turn interdependence into collective leverage.
Ronny P Sasmita is a senior analyst at Indonesia Strategic and Economics Action Institution, a think tank specializing in geopolitical and geoeconomic studies in Indonesia.
Sign up here to comment on Asia Times stories OrThank you for registering!
-
Share on X (Opens in new window)
Share on LinkedIn (Opens in new window)
LinkedI
Share on Facebook (Opens in new window)
Faceboo
Share on WhatsApp (Opens in new window)
WhatsAp
Share on Reddit (Opens in new window)
Reddi
Email a link to a friend (Opens in new window)
Emai
Print (Opens in new window)
Prin
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment