


Your Medicare Plan Stops Covering A Specialist - Can You Keep Seeing The Same Doctor?


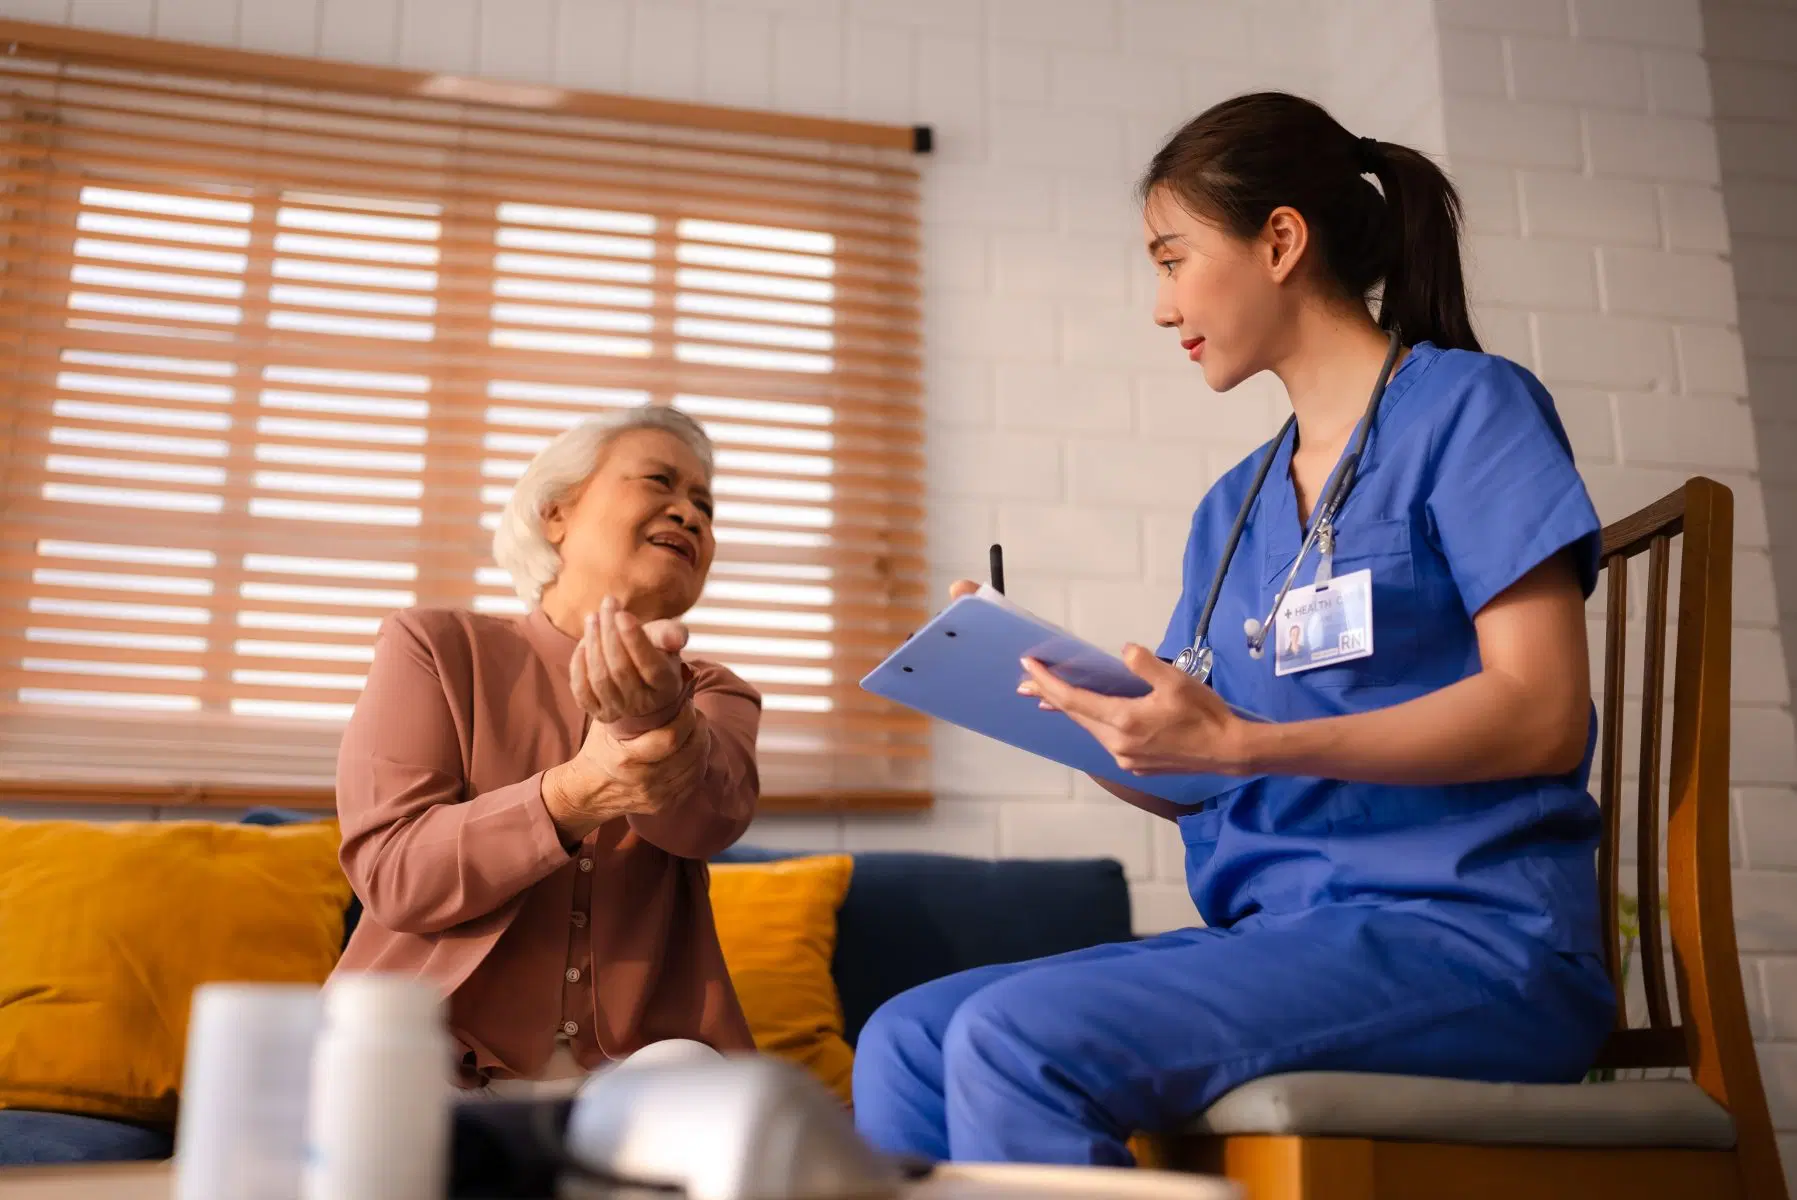
You've been seeing the same cardiologist for six years. They know your medical history, understand which treatments have worked, and have helped you manage a condition that requires regular attention. Then a letter arrives from your Medicare Advantage plan: Your specialist is leaving the network. Suddenly, an appointment you've attended for years could cost considerably more, or your insurance might not cover it at all. For retirees managing chronic conditions, this isn't simply an inconvenience. Finding another doctor can mean transferring records, repeating evaluations, delaying treatment, and potentially paying more for care.
The good news? Losing in-network access doesn't always mean you must immediately give up your doctor. Several options are worth exploring before making that decision.
Why Your Specialist Can Suddenly Leave the NetworkMedicare Advantage plans contract with physicians, hospitals, and other healthcare providers to establish their networks. Those agreements can change when contracts expire, negotiations break down, or either party decides to end the relationship. Under Medicare's provider network rules, insurers can add or remove participating providers during the year while remaining responsible for access to medically necessary covered services. The change can be particularly disruptive when a specialist has managed a patient's condition for several years. Unfortunately, choosing a plan because your doctor participates today doesn't guarantee that the arrangement will continue indefinitely.
Your Insurance Company Has Notification ResponsibilitiesPatients shouldn't have to discover a major network change when they arrive for an appointment. Medicare Advantage plans must provide notices to affected beneficiaries when certain providers leave their networks, with advance-notice requirements depending on the circumstances.
Federal Medicare Advantage regulations establish specific requirements for provider termination notifications, including information about alternative providers and continuing treatment. If you receive a notice, check the termination date, whether your upcoming appointments are affected, and what alternatives the insurer identifies. When the first warning comes from your doctor's office instead, contact your plan immediately and request the relevant information in writing.
Your HMO or PPO Coverage Makes a DifferenceNot every Medicare Advantage plan handles out-of-network specialists the same way. Health Maintenance Organization plans, commonly called HMOs, generally restrict nonemergency care to participating providers, subject to certain exceptions. Preferred Provider Organization plans, or PPOs, typically offer more flexibility to see out-of-network physicians, although the patient's share of the bill may be higher.
For example, a specialist appointment with a $40 in-network copayment might involve substantially greater cost-sharing outside the network, depending on the plan's terms. Before keeping your appointment, ask both the insurer and the specialist's billing department whether the visit will be covered and what you could owe.
Some Patients May Be Able to Continue Treatment TemporarilyA network change can be especially concerning when someone is undergoing chemotherapy, recovering from major surgery, or receiving ongoing treatment for a serious condition. Certain federal continuity-of-care protections may allow qualifying patients to continue receiving treatment from a departing provider temporarily, sometimes at in-network cost-sharing rates.
Some protections provide up to 90 days of transitional care, but eligibility depends on the coverage arrangement, circumstances of the provider's departure, and applicable law. These protections shouldn't be interpreted as an automatic 90-day extension for every Medicare Advantage specialist visit. Ask your insurer specifically what Medicare Advantage transition-of-care protections apply to your situation and request written confirmation of any approved arrangements.
Ask About an Out-of-Network Authorization Before PayingYour insurer may have options beyond requiring you to find another specialist immediately. If an appropriate in-network provider isn't available to deliver medically necessary covered treatment, the plan may need to arrange access to care outside its existing network. This could involve an out-of-network authorization, network exception, or other arrangement under the plan's procedures.
Your physician can help by documenting why the requested specialist or treatment is necessary and whether a change would disrupt ongoing care. Don't rely on a verbal assurance alone; request the authorization details, covered services, applicable dates, and expected cost-sharing in writing.
A Network Change Could Affect Your Retirement BudgetThe financial consequences can extend well beyond one specialist appointment. Consider someone who previously paid $45 for an in-network visit but would owe $175 under a hypothetical out-of-network arrangement. At six appointments annually, that difference adds up to $780 before considering testing, procedures, or additional treatment.
These figures are illustrative, and actual costs depend on your plan's benefits and provider arrangements. For retirees living primarily on Social Security or retirement savings, understanding the full cost of continuing care is essential before accepting a new billing arrangement.
Your Doctor Can Help if the Insurer Denies CoverageA network change and a coverage denial aren't necessarily the same thing. Your plan may still cover the medical treatment itself while requiring you to receive it from another participating provider. If the insurer denies a request for medically necessary care or refuses an applicable authorization, you may have the right to request a formal decision and appeal. Medicare's appeals process provides procedures for challenging qualifying adverse coverage decisions, including expedited reviews when medical circumstances justify them. Ask your specialist to document the treatment history, clinical risks of interruption, and reasons a proposed alternative may not meet your medical needs.
Could Switching Medicare Plans Let You Keep Your Specialist?Changing coverage may be worth considering when your current plan no longer includes an important physician. Medicare's Annual Open Enrollment Period runs from October 15 through December 7, allowing eligible beneficiaries to make coverage changes that generally take effect January 1. People already enrolled in Medicare Advantage also have a separate January 1 through March 31 enrollment opportunity, while certain circumstances may qualify for a Special Enrollment Period.
However, an individual doctor leaving a network doesn't automatically create a right to switch plans immediately; Medicare generally must determine that a network change qualifies or approve another applicable enrollment exception. Before switching, compare prescription coverage, hospitals, premiums, deductibles, specialist access, and the potential cost of supplemental insurance if you're considering Original Medicare.
This is also where an independent Medicare plan review can be useful. Chapter's licensed Medicare advisors can help beneficiaries compare available plans and investigate whether their preferred specialists participate, rather than focusing only on monthly premiums. The review is free, and there's no obligation to enroll through Chapter. You can reach Chapter at (864) 668-3280 to discuss your options before making a coverage decision or visit their website.
Original Medicare May Offer More Provider FlexibilityOriginal Medicare generally allows beneficiaries to visit any physician or specialist who accepts Medicare, without the same type of insurer-contracted provider network used by many Medicare Advantage plans. That flexibility can be valuable for patients who rely on several specialists or receive treatment at different healthcare systems. However, Original Medicare doesn't have the same annual out-of-pocket maximum for covered Part A and Part B services that Medicare Advantage plans must provide. Many beneficiaries purchase Medigap coverage to help manage certain expenses, but obtaining a policy after leaving Medicare Advantage may involve underwriting or eligibility restrictions outside protected enrollment periods. Switching coverage deserves a complete financial review rather than a decision based on one doctor's participation alone.
Don't Overlook Free Help With Medicare Coverage ProblemsPatients dealing with a network change don't have to navigate every insurance rule independently. The State Health Insurance Assistance Program offers free, unbiased Medicare counseling to beneficiaries and their families. Counselors can help you understand enrollment periods, coverage decisions, appeals, and available assistance programs. You can also call 1-800-MEDICARE if a network change threatens access to medically necessary care or you believe you may qualify for a special enrollment opportunity. Keep copies of every notice, authorization request, and written response so that you have documentation if the dispute continues.
Take These Steps Before Your Next Specialist AppointmentStart by confirming the exact date your specialist will leave the network and whether any existing treatment authorization remains valid. Next, ask the insurer about transitional care, an out-of-network authorization, and available participating specialists with comparable expertise. Contact your doctor's billing office for an estimate of what continued visits could cost under your current coverage. If the available options don't meet your medical needs or budget, explore whether another Medicare plan would provide better access without creating larger expenses elsewhere. Most importantly, don't cancel medically necessary treatment or assume you'll be responsible for the entire bill until you've clarified your coverage options.
Keeping Your Doctor May Be Possible, but Timing MattersLosing access to a trusted specialist can make an already complicated healthcare system feel even more difficult to navigate. Fortunately, provider network changes don't always eliminate every opportunity to continue treatment or find alternative coverage. The key is understanding your plan's rules, documenting medical necessity when appropriate, and checking your financial exposure before making a decision. Whether you pursue continued-care authorization, appeal a denial, or compare other Medicare plans, taking action early gives you more time to protect your care.
Have you ever lost access to a trusted specialist because of a Medicare Advantage network change, and were you able to keep seeing that doctor?
Drew BlankenshipDrew Blankenship is a seasoned personal finance and lifestyle writer with more than a decade of professional writing experience crafting clear, actionable advice that helps savers and investors over 40 protect their wealth and make smarter everyday decisions. His bylines appear regularly on SavingAdvice, CleverDude, and other respected outlets, where he draws on deep industry knowledge to deliver practical insights on cost control, smart spending, and long-term financial security.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment