


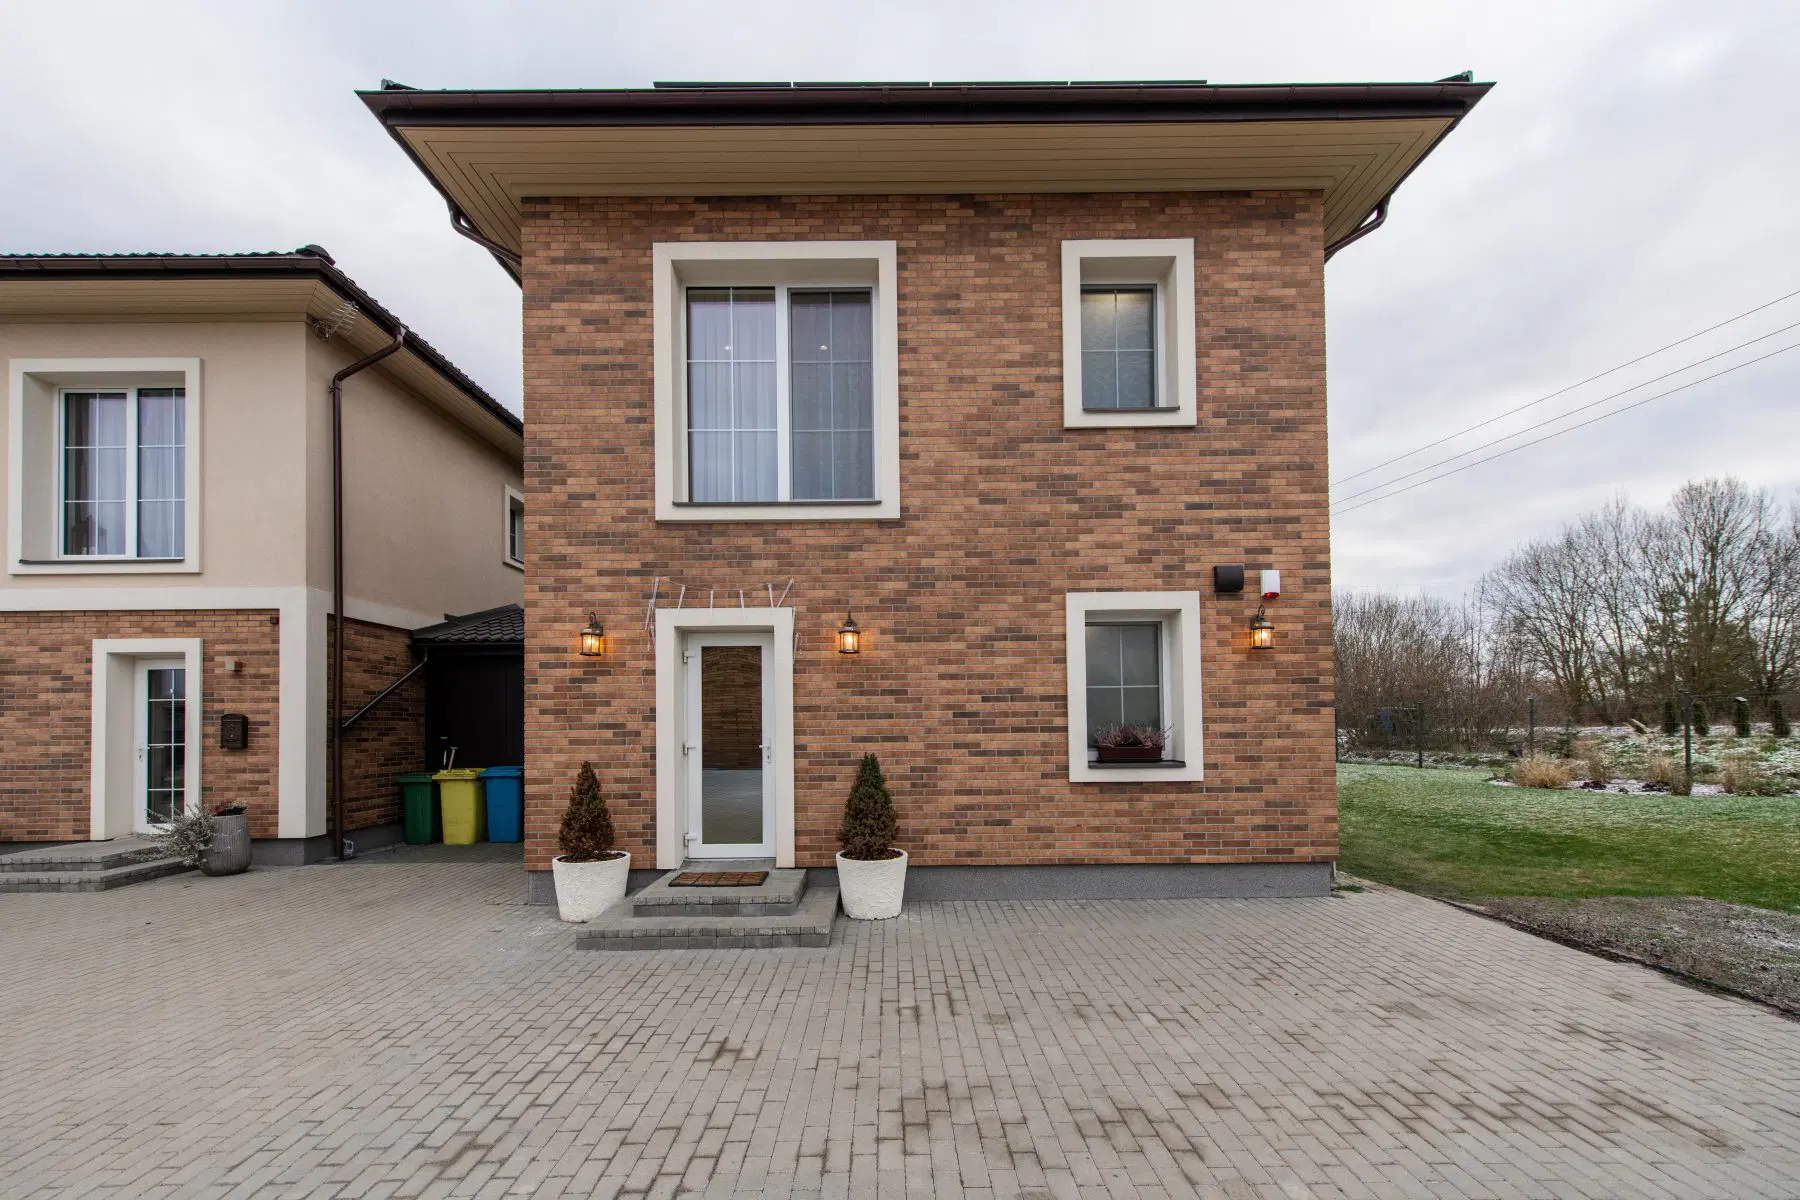
The Unexpected Cost Of Keeping A Parent's House After They Move Into Assisted Living


| Expense | Annual cost |
|---|---|
| Property taxes | $4,200 |
| Homeowners insurance | $2,100 |
| Utilities | $1,800 |
| Lawn care and maintenance | $2,400 |
| Repairs and unexpected expenses | $3,000 |
| Total annual cost | $13,500 |
That's $1,125 per month before HOA fees, major renovations, or assisted living expenses enter the picture. Over three years, the same annual spending would total $40,500, assuming expenses remained unchanged. These are illustrative figures rather than national averages, but they show why families need an actual budget before deciding to keep a property indefinitely.
Property Tax Exemptions Could Change After the MoveMany older homeowners receive property tax relief through homestead exemptions, assessment limits, senior programs, or disability-related benefits. Depending on state and local law, some of those benefits require the property to remain the owner's primary residence. Moving permanently into assisted living could affect eligibility, although certain jurisdictions allow exceptions for medical absences or continued ownership.
Losing an exemption may increase the tax bill even when the home's assessed value hasn't changed substantially. Contact the county assessor or local tax office to determine whether the move must be reported and which benefits can legally continue.
Renting the House Could Help, but It Introduces New RisksTurning the property into a rental may seem like an obvious way to offset assisted living expenses. However, gross rental income isn't the same as money available to pay for care once maintenance, vacancies, property management, insurance, and taxes are deducted. A house renting for $1,800 monthly could generate $21,600 annually before expenses, but repairs or several months without a tenant could reduce that amount considerably.
Renting may also affect the parent's tax situation, insurance needs, and eligibility for certain means-tested benefits. Before advertising the property, confirm that the person signing the lease has legal authority and calculate the realistic net income rather than relying on the advertised rent.
Medicaid Rules Can Make Keeping the Home ComplicatedSome families hold onto a parent's house because they believe it will be protected if Medicaid eventually helps pay for long-term care. While a primary residence may receive favorable treatment under certain Medicaid eligibility rules, the protections depend on state law, the owner's circumstances, and applicable equity limits. Medicaid also has estate recovery requirements for certain long-term care benefits, meaning a home that was excluded from eligibility calculations may still become relevant after the owner's death.
The federal Medicaid estate recovery rules include important protections for qualifying surviving spouses, children, and other circumstances. Gifting the house or transferring ownership without professional guidance can create additional problems, including Medicaid transfer penalties, so consult a qualified elder-law attorney before changing the deed.
Selling the Home May Offer Tax Benefits You Don't Want to LoseSelling a longtime primary residence can qualify for a substantial federal capital gains tax exclusion. Under IRS home-sale rules, eligible individuals may exclude up to $250,000 in gain, while certain married couples filing jointly may qualify for up to $500,000.
Generally, the homeowner must have owned and used the property as a primary residence for at least two of the five years preceding the sale, along with meeting other requirements. Waiting several years after moving out could affect eligibility if no exception applies. Before deciding to keep the house indefinitely, have a tax professional review the ownership history, potential taxable gain, and whether a future sale might become less favorable.
Moving Into Assisted Living Doesn't Always End the Home-Sale ExclusionThere's an important exception that families frequently overlook when a parent moves into long-term care. Under IRS Publication 523, a homeowner who becomes physically or mentally unable to care for themselves may count qualifying time spent in a licensed care facility toward the residence requirement.
To use this special provision, the person generally must have lived in the home as a primary residence for at least one year during the relevant five-year period and meet the other applicable conditions. This means some older homeowners may preserve eligibility for the capital gains exclusion even after spending an extended period in qualifying care. Not every assisted living arrangement automatically satisfies the exception, making the facility's licensing status and the parent's circumstances important details to verify.
Waiting Until Inheritance Changes the Tax CalculationFamilies sometimes delay selling because inherited property generally receives a new tax basis tied to its fair market value at the owner's death, subject to applicable exceptions. That adjustment can reduce taxable capital gains when heirs eventually sell the property. However, a potentially favorable inheritance tax outcome doesn't automatically justify years of carrying costs.
A family spending $13,500 annually to maintain a house for five years would pay $67,500 before major repairs, inflation, or the opportunity cost of money tied up in the property. Compare the potential tax savings with the actual financial burden rather than assuming waiting is always the better choice.
Make Sure Someone Has Legal Authority to Handle the PropertyAdult children don't automatically gain the right to sell, rent, or transfer a parent's house simply because that parent has moved into assisted living. If the parent remains mentally capable, they generally retain authority over decisions involving property they own. When someone else must act, a properly executed financial power of attorney, trust arrangement, or court appointment may be necessary, depending on state law and the proposed transaction.
Powers of attorney can also contain restrictions on gifting, self-dealing, or transferring property to family members. Review the legal documents before signing a lease, listing the home for sale, or making decisions that could affect the parent's assets.
Family Disagreements Can Create Another Layer of ExpenseA family home often carries emotional value that doesn't appear on a financial statement. One sibling may want to keep it, another may prefer selling to cover care expenses, and someone else may believe the property should eventually become their inheritance. Without a clear agreement, disagreements can arise over who pays the bills, maintains the property, or decides when selling becomes necessary.
These conflicts can lead to attorney fees, delayed decisions, and financial pressure on the parent whose money is supporting the arrangement. A written plan outlining responsibilities, expenses, decision-making authority, and a timeline for reconsidering ownership can prevent many disputes before they escalate.
Set a Deadline for Reconsidering the DecisionKeeping the house temporarily may be reasonable when a parent's long-term care needs are still uncertain. But an open-ended decision can turn into years of expenses without anyone deliberately choosing that outcome. Families might agree to review the situation after three or six months, using actual costs, the parent's health needs, and available financial resources to guide the discussion. That review should include whether returning home remains realistic, whether the property can generate meaningful income, and how long existing savings can support both housing arrangements. Setting a review date allows the family to respect emotional attachments without ignoring the financial consequences.
The Family Home Shouldn't Jeopardize the Parent's Financial SecurityThere may be good reasons to preserve a parent's house after they move into assisted living, particularly when a return home remains possible or the property has a practical long-term purpose. But keeping it shouldn't become an automatic decision simply because the mortgage is paid off or selling feels emotionally difficult. The real question is whether the home's ongoing expenses, tax implications, and potential value fit within the parent's overall financial plan. Before committing to years of maintenance, compare keeping, renting, and selling with the help of qualified legal or financial professionals when necessary.
Would you keep a parent's house after they moved into assisted living, or would you sell it to help pay for their care?
Drew BlankenshipDrew Blankenship is a seasoned personal finance and lifestyle writer with more than a decade of professional writing experience crafting clear, actionable advice that helps savers and investors over 40 protect their wealth and make smarter everyday decisions. His bylines appear regularly on SavingAdvice, CleverDude, and other respected outlets, where he draws on deep industry knowledge to deliver practical insights on cost control, smart spending, and long-term financial security.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment