


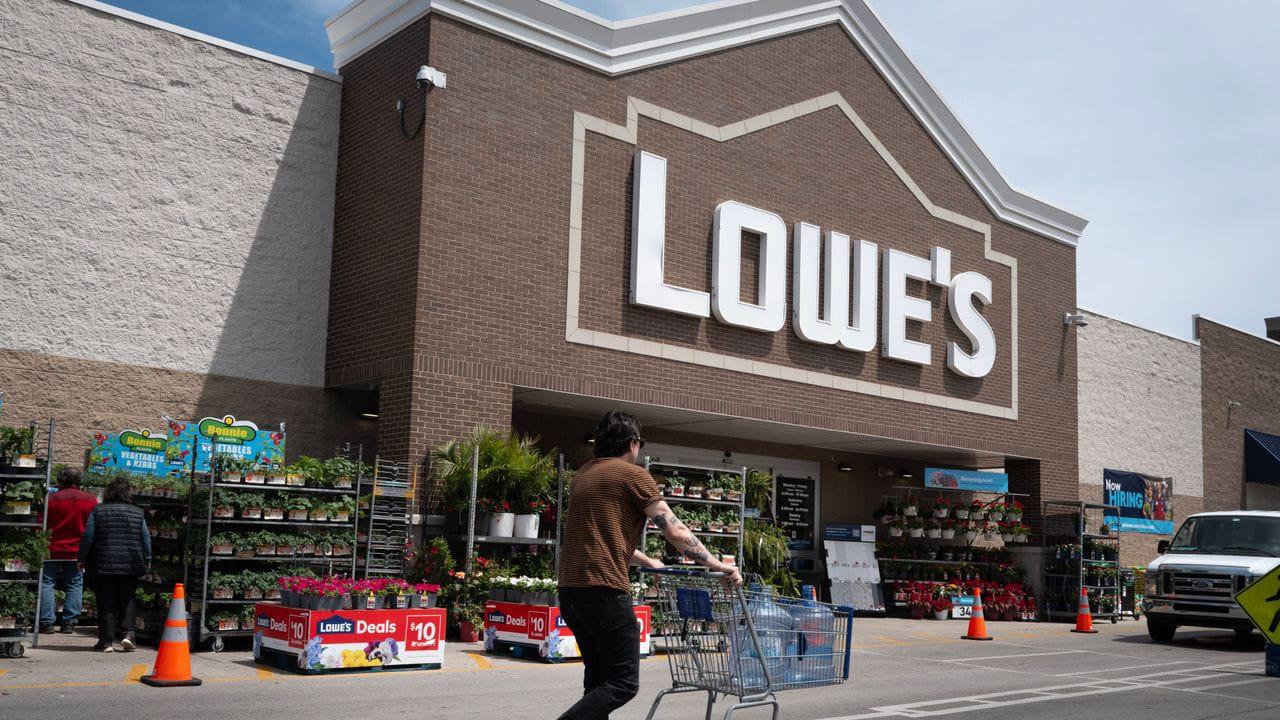
LOW Stock Gets Fresh Analyst Downgrade Ahead Of Q3 Earnings What Investors Need To Know


- The firm cited housing market weakness, expected margin pressure in fiscal 2027 and 2028, and structural challenges, including DIY weakness and increased competition. Stifel believes rival retailer Home Depot is better positioned, citing its stronger core business and appropriate investments, according to The Fly. Lowe's is scheduled to report fiscal third-quarter 2026 results on Nov.18. Analysts expect earnings of $2.87 per share on revenue of $22.36 billion, according to Fiscal.
Lowe's Companies (LOW) was downgraded by Stifel ahead of its fiscal third-quarter earnings report next week, with the firm citing housing market weakness, margin pressures and increased competition.
Analyst W. Andrew Carter downgraded Lowe's to 'Sell' from 'Hold' and lowered the firm's price target to $190 from $195, according to The Fly. The revised price target represents a potential downside of around 16.5% from the stock's Thursday's closing price.
LOW shares traded 1.9% lower in premarket trading at the time of writing.
Twenty-four of 35 analysts covering the stock rate it 'Buy' or 'Strong Buy,' whereas 10 rate it 'Hold' and one rates it 'Strong Sell,' according to Koyfin. Their 12-month price targets range from $191 to $290, with an average of $250.52.
Why Did Stifel Downgrade Lowe's?
Stifel cited a weaker housing backdrop in the second half of 2026, along with expectations of operating margin pressure in fiscal 2027 and 2028, according to The Fly.
The firm also highlighted structural challenges, including continued weakness in the do-it-yourself (DIY) category, uncertainty across housing-related product categories, and increased competition requiring additional investments, The Fly reported.
Stifel believes Home Depot (HD) is better positioned, citing its stronger core business and investments. In contrast, Lowe's is more exposed to these challenges and could require investments above investor expectations, according to The Fly.
Stifel's Valuation And Earnings Outlook
Stifel's operating margin estimate is also 20 basis points below the consensus expectation of a 34-basis-point increase, according to Investing.
The firm also believes Lowe's specialty trade platform requires another large acquisition. However, its leverage profile makes pursuing such a deal challenging. Stifel also flagged potential scrutiny of the existing platform's results because of its exposure to new residential construction, Investing reported.
Lowe's is scheduled to report its fiscal third-quarter 2026 results on Nov. 18, before the market opens. Analysts expect earnings of $2.87 per share on revenue of $22.36 billion, according to estimates compiled by Fiscal.
How Retail Views LOWE
On Stocktwits, retail sentiment around the stock turned 'bullish' from 'neutral', amid 'normal' message volumes in the past 24 hours.
LOW shares have dropped over 4% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment