


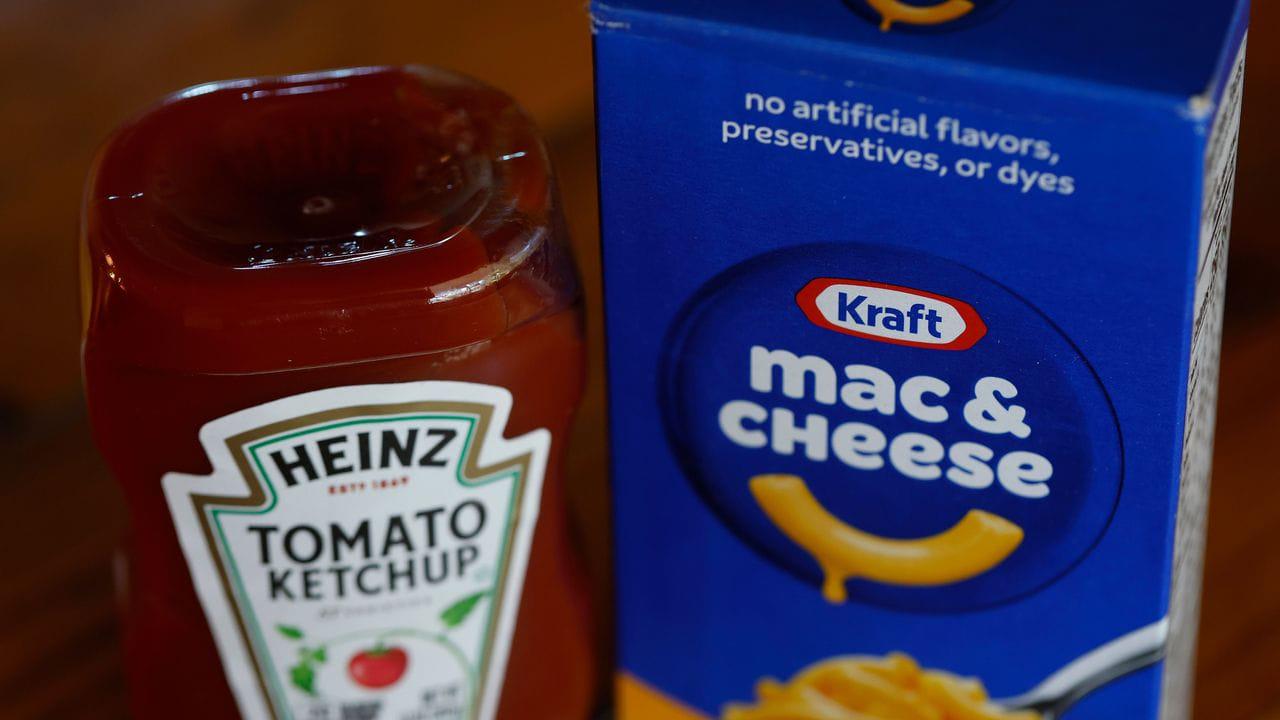
KHC Stock Forms Death Cross: Can Kraft Heinz's New Growth Plan Power A Turnaround?


- Kraft Heinz's latest death cross signals weakening momentum, following a similar pattern in July 2024. Kraft Heinz outlined a turnaround plan targeting a return to revenue and profit growth in late 2027. Morningstar maintained its $41 fair value estimate for Kraft Heinz, citing improvements in market share.
Kraft Heinz Co. (KHC) stock formed a so-called death cross this week, a bearish technical signal not seen since July 2024, just as the company unveiled a plan on Thursday promising a return to growth. The last one preceded a 33% slide in the shares over the next 20 months.
Kraft Heinz stock edged 0.5% higher overnight, ahead of Friday. The stock is down 0.5% so far this week.
KHC's Previous Death Cross Preceded A Steep Decline
A death cross occurs when a stock's 50-day moving average falls below its 200-day moving average. Traders read it as a sign that short-term momentum has faded relative to the longer-term trend. It is a lagging indicator, so it confirms weakness that has already happened and doesn't predict what comes next.
According to a Barchart X post, KHC's last cross, in July 2024, came with shares near $35. They ended up around $23.50 some 20 months later. This time the stock closed Thursday at $24.48, up 0.87%, after bottoming near $21 in March and rallying to about $28 in July.
KHC Targets Return To Sales And Profit Growth In 2027
At its 2026 Investor Day on Thursday, Kraft Heinz laid out a multiyear path to what it called sustainable, volume-led profitable growth.“The opportunity ahead of us is significant, and we have the brands, scale and capabilities to capture it,” CEO Steve Cahillane said.
Kraft Heinz plans to rein in market share losses and increase sales volumes across all regions in 2026. It expects revenue and profit growth to return in the second half of 2027. In 2028, the company aims to grow sales and improve profit margins. By 2029, it hopes to achieve sustained profit growth and give double-digit returns to shareholders.
KHC expects sales to remain mostly unchanged in 2027, while adjusted operating income could fall slightly. The company expects growth to return only in the second half of the year.
Kraft Heinz Q3 Sales And Profits Decline
Third-quarter results explain the caution. Net sales fell 2% to $6.1 billion, and organic sales slipped 1.1%, with North America volume weak in meats, sauces, and refreshment beverages. Adjusted operating income dropped 15.2%, and adjusted EPS fell to $0.53 from $0.61.
Kraft Heinz did raise the low end of its full-year organic sales outlook to a decline of 0.5% to 1.25%. It now expects adjusted EPS of $2.07 to $2.13, up from $2.03 to $2.09. But the guidance still implies adjusted operating income down 16% to 18% on a constant-currency basis, reflecting about $700 million in incremental investment.
According to a Wall Street Journal report, Cahillane, who took over nearly a year ago, has called the brands underinvested for more than a decade. This year's extra spending included $325 million for marketing, $250 million for lower prices, $75 million for personnel and $50 million for product and packaging innovation.
The pipeline is aimed at health and wellness. Spring arrivals in the U.S. include Jell-O pudding with 10 grams of protein, Crystal Light with added fiber and protein, Oscar Mayer Sandwich Bacon and Kraft Mac & Cheese Cheesy Ramen.
Not everything is working. Oscar Mayer and Kraft cheese continue to struggle, and Philadelphia cream cheese has been hurt as protein-hungry shoppers move to cottage cheese.
Analyst Sees Early Signs Of Kraft Heinz Turnaround
Morningstar's Erin Lash noted that the company acknowledged Philadelphia promotions fell flat, which she took as a sign that consumers want on-trend innovation, not just lower prices.
Morningstar reiterated a $41 fair value estimate, about 67% above the stock's last close. Lash pointed to early evidence that the investments are working. More than 30% of Kraft Heinz's sales base has held or gained market share this year, up from 21% in 2025, and returns on promotions and advertising have improved, she said.
Kraft Heinz is also reshaping the portfolio. Last week it agreed to sell a majority stake in its North America coffee business, including Maxwell House and Gevalia, to One Rock Capital Partners at an enterprise value of $650 million. It will keep a 30% stake. Net proceeds of about $500 million are earmarked for debt reduction, and the deal is expected to close in mid-2027.
KHC Stock: Retail View
On Stocktwits, retail sentiment around the stock turned 'neutral' from 'bearish'. The stock recorded an 800% surge in message volume over the past 24 hours.
A user said,“The path is clear now! Growth is here! As I said numerous times before, we would destroy the ER estimates and we did! Folks, this is so cheap it's insane!!! Rotation is here as well! AI bubble has popped, it's done!
Another user said,“Another great company sinking into the dirt. They should've sold the coffee division to KDP. Sooner or later the whole "Kraft Mac and Cheese" "Kraft Singles" and "Heinz Ketchup" labels will mean absolutely nothing cause the company behind said labels no longer has anything to do with it.”
KHC stock has gained nearly 1% year-to-date.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment