


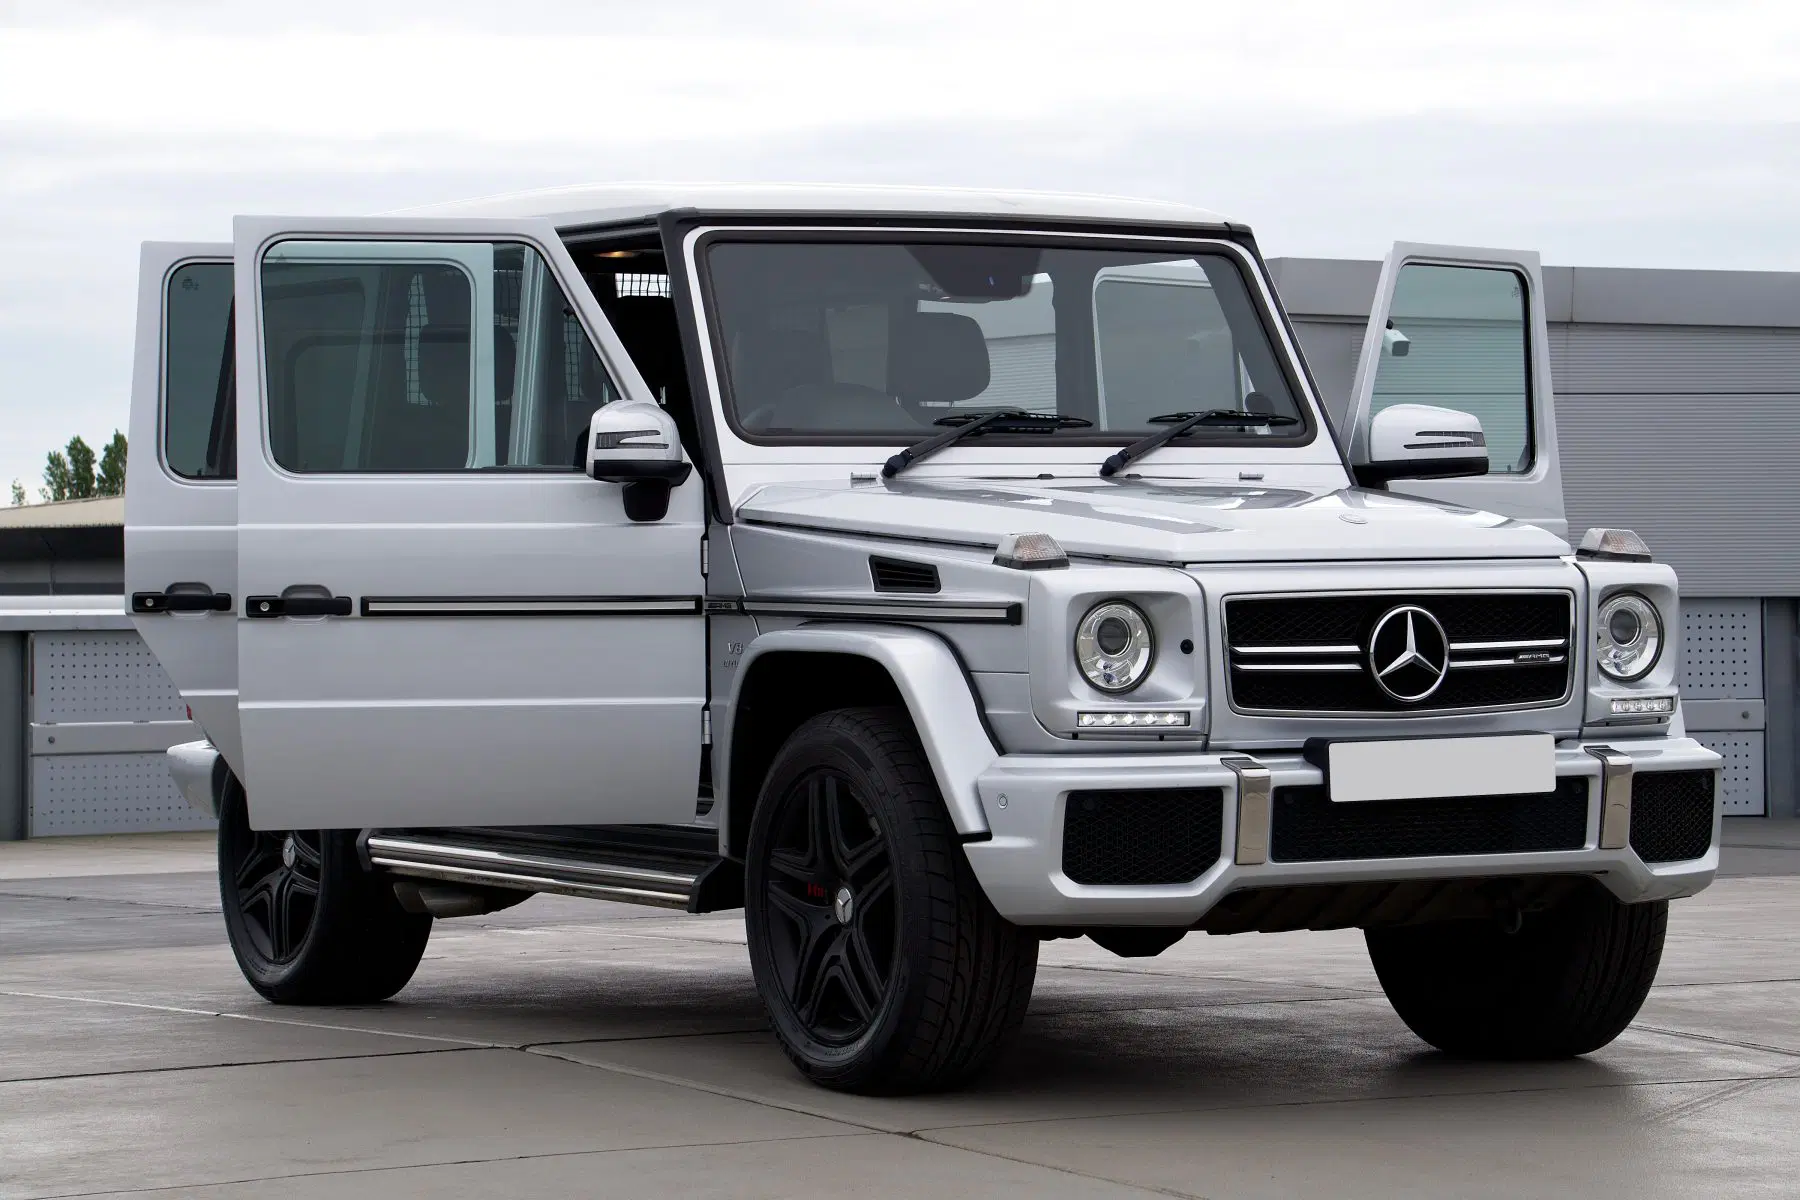
We Calculated What A $1,000 Monthly Car Payment Could Cost Over 10 Years


After all, newer vehicles offer advanced safety features, improved technology, and the comfort of a manufacturer's warranty. For some households, a large vehicle payment fits comfortably within the budget.
But there's a major difference between being able to make the monthly payment and understanding what that payment costs over time.
We calculated the cost of a $1,000 car payment over ten years, including what happens when a driver replaces one financed vehicle with another.
The results demonstrate how transportation decisions can influence long-term savings and financial flexibility.
The Basic Calculation Is $120,000The simplest calculation involves multiplying a $1,000 monthly payment by 120 months. That produces $120,000 in total payments over ten years. However, this doesn't necessarily mean someone purchased a single $120,000 vehicle or paid $120,000 in vehicle depreciation. Auto loan payments include repayment of borrowed principal and interest, and the driver may still own a vehicle with resale value at the end. The calculation represents cash paid toward financing over the decade, not the vehicle's total economic cost.
Two Consecutive Loans Can Create the Same ResultConsider someone who finances a vehicle with a $1,000 monthly payment for 60 months. Over five years, those payments total $60,000. If the driver then purchases another vehicle with the same monthly payment and loan term, another $60,000 is committed. The combined payments reach $120,000 over ten years, even though the driver may have owned two different vehicles. Down payments, trade-in values, sales taxes, financing terms, and remaining vehicle equity would affect the complete financial picture.
A $1,000 Payment Is Well Above the AverageRecent auto financing data provides useful context for understanding how unusual a four-figure payment may be. Experian's 2026 auto loan research reported an average monthly auto loan payment of approximately $697 as of March 2026. That means a $1,000 payment is roughly $303 higher than the reported average. Over 60 months, the difference amounts to $18,180 in additional payments, assuming both amounts remain constant. Average figures include a variety of loans and vehicles, so they shouldn't be mistaken for the typical cost of a particular new model.
Interest Rates Change What the Payment BuysA $1,000 monthly payment can finance very different loan amounts depending on the interest rate and repayment term. At a hypothetical 7% annual percentage rate over 60 months, a $1,000 monthly payment supports approximately $50,500 in principal. At 10% over the same term, the financed principal falls to approximately $47,100. The difference reflects the larger share of each payment devoted to interest at the higher rate. These examples exclude taxes, fees, down payments, and other charges that can change the amount financed.
The Vehicle Payment Isn't the Total Transportation CostAuto insurance, fuel, maintenance, repairs, registration, and parking add to the cost of owning a vehicle. A household paying $1,000 monthly toward financing might also spend $200 on insurance, $180 on fuel, and $100 in average monthly maintenance reserves. That creates an illustrative transportation budget of $1,480 per month before registration, taxes, parking, and other expenses. Over ten years, maintaining that spending level would require $177,600 in cash outlays. Actual expenses vary by vehicle, driving habits, insurance rates, and the number of years the owner keeps each car.
Depreciation Creates Another Financial ConsiderationVehicles generally lose market value as they age, although depreciation rates differ significantly by model and market conditions. A driver who purchases an expensive vehicle and trades it in after only a few years may repeatedly absorb substantial depreciation. Financing can make that cost less visible because the monthly payment remains the primary focus. However, the difference between the vehicle's market value and the outstanding loan balance determines whether the owner has positive or negative equity. Trading in a vehicle with negative equity can increase the amount borrowed on the next purchase.
What if You Invested the Difference Instead?The cost of a $1,000 car payment becomes more interesting when compared with a less expensive transportation option. Suppose a household chooses a $500 monthly payment instead, freeing $500 every month for other financial goals. Investing that $500 at the end of each month for ten years with a hypothetical 6% annual return compounded monthly would produce approximately $81,940. Of that amount, $60,000 would come from contributions and the remainder from hypothetical investment growth. Actual investment returns aren't guaranteed, and the comparison doesn't account for differences in down payments, repairs, insurance, or resale values.
Longer Loans Can Hide the True PriceExtending an auto loan can reduce the monthly payment while increasing total interest costs. Consider a hypothetical $50,000 loan at 8% APR. Over 60 months, the payment would be approximately $1,014, with total interest of about $10,829. Extending the same loan to 84 months reduces the payment to approximately $779 but increases total interest to about $15,460. The longer term costs roughly $4,600 more in interest and keeps the borrower in debt for an additional two years.
A $1,000 Payment Isn't Automatically a Bad DecisionSome households can afford expensive vehicles without compromising emergency savings, retirement contributions, or other financial priorities. A high payment may also reflect a short loan term rather than an unusually expensive vehicle. Someone financing a reliable work vehicle for business purposes may evaluate the expense differently from someone purchasing a luxury vehicle for personal use. The important question is whether the total transportation cost fits the household's long-term financial goals. A monthly payment alone doesn't provide enough information to determine affordability.
The Ten-Year Cost Deserves More Attention Than the Monthly PaymentOur calculation shows that maintaining a $1,000 car payment for ten consecutive years requires $120,000 in financing payments alone. Insurance, maintenance, fuel, and other ownership costs can push total cash spending substantially higher. However, resale value, loan terms, and the number of vehicles purchased affect the ultimate economic cost. Comparing financing alternatives and calculating the opportunity cost of higher payments can reveal trade-offs that aren't obvious at the dealership. Before committing to an expensive vehicle, consider what the same money could accomplish elsewhere in your financial life.
Would you ever feel comfortable with a $1,000 monthly car payment, or do you think that money is better used for savings, investments, or other priorities? Share your thoughts in the comments.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment