


Growth Intact But Under Pressure: 3 Calls For The Eurozone In 2027


With real wages under pressure and the labour market cooling, consumption is likely to start the year sluggishly, while the prospect of tighter fiscal policy in several member states adds another headwind.
Higher bond yields and the resulting tightening of financial conditions are set to weigh on investment, particularly in residential construction. Nevertheless, the eurozone should still achieve growth of around 1% in 2027.
Expansion in AI-related industries is expected to contribute around 0.1pp to GDP growth, while the drag from elevated energy prices should gradually fade as oil and gas prices normalise throughout the year, providing some relief for businesses and consumers alike. Meanwhile, Germany's fiscal stimulus remains an important growth driver, both domestically and via positive spillovers to the entire eurozone.
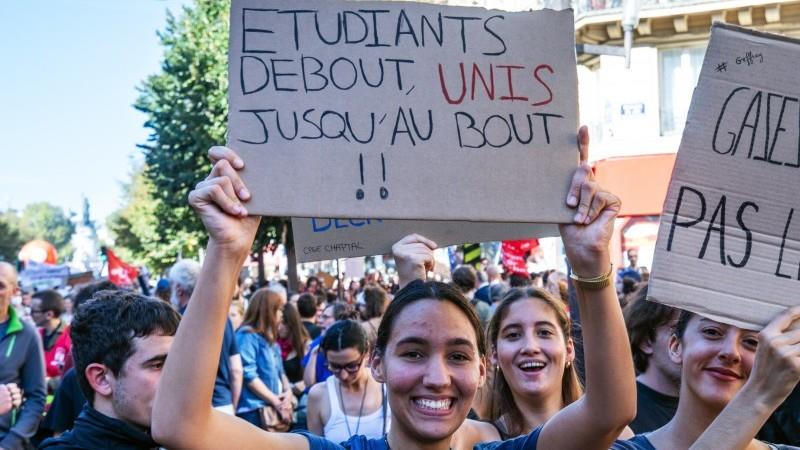
Risky call: Generational conflict pushes Europe further away from climate goalsProtests continue across many European cities, but their focus is shifting. After the climate-driven 'Fridays for Future' movement, younger Europeans are increasingly voicing concerns about more immediate economic pressures, particularly housing affordability and the cost of living.
For younger Europeans, climate change is a clear source of intergenerational tension. To paraphrase Bertolt Brecht,“first comes food, then comes climate change”. As a consequence of this boiling intergenerational conflict, there will be broader support across Europe and generations to further delay climate targets, providing some relief for European industry. The most prominent casualty could be ETS2, with a further postponement leading to lower inflation in 2028 than previously expected.
Bold call: New crisis within the eurozone forces the ECB to act decisivelyIn this scenario, France's political and social situation deteriorates further, with presidential and subsequent parliamentary elections failing to produce a government willing to address the country's budgetary challenges. Other highly indebted countries face similar problems as the population increasingly rejects austerity and elections result in greater political fragmentation, consequently leading to higher fiscal deficits as governments try to smooth fragmentation with more money.
Bond yields then rise further, triggering unfavourable debt spirals. Although banks are less vulnerable to a debt crisis than before, their shares would be hit hard, further tightening credit conditions and hampering economic growth. The ECB would ultimately be forced to intervene, lowering policy interest rates to 0.5% and restarting quantitative easing. These measures would limit the economic damage, but they would also keep inflation above 2% as fiscal dominance remains the only feasible alternative to austerity measures.

Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment