


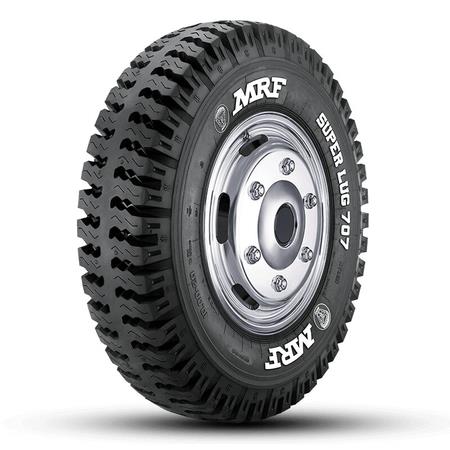
MRF Q2 Profit Drops Nearly 28 Pc To Rs 369 Crore


The company posted a consolidated net profit of Rs 369 crore in the second quarter of FY27, down 27.8 per cent from Rs 512 crore reported in the corresponding period last financial year (Q2 FY26), according to its stock exchange filing.
Revenue from operations, however, grew 17.6 per cent year-on-year (YoY) to Rs 8,524 crore, compared with Rs 7,250 crore in the year-ago quarter.
The company's operating performance came under pressure during the quarter. Earnings before interest, tax, depreciation and amortisation (EBITDA) fell 16.3 per cent to Rs 913 crore from Rs 1,090 crore a year earlier.
Consequently, EBITDA margin contracted sharply to 10.7 per cent from 15 per cent in the corresponding quarter of the previous fiscal, as per its regulatory filing.
The decline in earnings came despite higher sales, largely due to a significant increase in input costs.
Total expenses during the September quarter rose 21.8 per cent to Rs 8,269.77 crore, compared with Rs 6,788.55 crore in the same period last year.
A major contributor to the rise in expenditure was the surge in raw material costs. The company's spending on raw material consumption jumped nearly 43 per cent year-on-year to Rs 6,552.57 crore during the quarter, up from Rs 4,577.49 crore in the year-ago period.
The substantial increase in input costs eroded operating margins and weighed on overall profitability.
Reflecting the pressure on earnings, profit before tax (PBT) declined to Rs 521.81 crore from Rs 700.45 crore a year earlier. Earnings per share (EPS) also fell to Rs 912.46 from Rs 1,243.60 in the corresponding quarter of FY26.
Meanwhile, MRF's board approved an interim dividend of Rs 3 per share for FY27. The company has fixed November 17 as the record date for determining shareholders eligible to receive the dividend.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment