


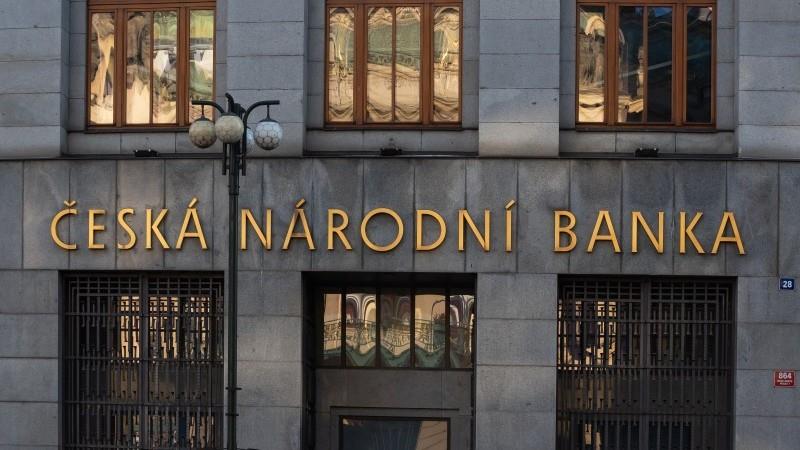
Czech National Bank Review: The New Neutral Normal


The CNB proceeded with a rate hike on Thursday, raising the base rate to 4%, which matches the expectations of market participants. The decision was taken in a split vote as four board members favoured a tighter monetary policy setup, while three policymakers opted for rate stability. The situation is perceived as inflationary, with persistently elevated core inflation, weaker exchange rate, and a still strong housing market, along with ample credit growth, seen as the main forces to keep in check through a tighter monetary policy stance. Robust wage growth and expansive fiscal policy are also assessed as risks to price stability. The decision and the mood of the press conference are in line with our expectations in both respects: i) one rate rise in November, and ii) concerns about economic performance putting a lid on further tightening.
CNB's real GDP path remains on the optimistic side Source: CNB, ING, Macrobond">
The new CNB staff projection points to slower economic expansion along with more elevated inflation, as we have foreseen. We must notice with some delight that the CNB inflation outlook is quite close to ING's view throughout the forecast horizon. Meanwhile, the CNB growth outlook remains a little optimistic compared with our view, especially for the coming year. As for short-term interest rate, the CNB forecast suggests a further increase up to 4.5% in the nearest future, followed by a gradual decline from 2Q27 to 3.5% at the end of 2028. We see such a trajectory rather as an alternative scenario, should inflation prove even stronger than in our forecast.
Forecast marriage in inflation Source: CNB, ING, Macrobond">The interesting thing is that the governor described the monetary conditions as very tight at this point, and even beforehand. Well, should our hypothesis about the need for much higher equilibrium rates in the brave new world be right, then 4% seems to be a neutral stance that just prevents inflation from systematically hovering above the target. And with the CNB rate projection landing at 3.5% at the very end of the forecasting horizon, we believe that the staff is perhaps starting to drift in the same direction, at least implicitly.
That said, interest rates are an endogenous variable in the CNB workhorse model, so you can argue that this particular rate path enables the 2.5% economic expansion, with inflation receding towards the target. But hey, would you really be cutting rated so swiftly, while having inflation still running above your target and the economy growing around its potential? I have some doubts, but will stick to the old good maxim in dubio pro reo.
The bank board will likely smooth out the rates path Source: CNB, ING, Macrobond">The infamous“all options are open” mantra was brought out of its shallow grave and into the daylight once again, but the dwindling real interest rate in the outlook does not suggest it stands on solid ground. Overall, we see 4% as the new neutral normal and believe that this will enable the CNB to ride out the wave of second-round effects, provided that our real GDP and inflation forecasts are right.
Our market viewThe main takeaway from the CNB meeting is the 4–3 split within the board, following a long period of strong majorities. The market interprets this as a dovish signal, suggesting the CNB is unwilling to hike rates further unless the inflation situation deteriorates significantly. For the first time since the onset of the US-Iran conflict, the CNB's forecast aligns closely with market pricing, with the PRIBOR rate peaking at around 4.55%. However, inflation is expected to worsen over the remainder of the year, approaching 3% and nearing 4% in the first quarter of 2027, bringing the new CNB outlook closer to our own forecast. We do not believe the current shift in energy prices justifies such a rally in CZK rates. The move appears excessive at this juncture. Consequently, we view two additional rate hikes as the minimum the market will tolerate, and, given today's rebound, we anticipate a hawkish repricing.
EUR/CZK is facing renewed upward pressure. Indeed, if we take the shift in rate differentials at face value, the rates point toward 24.450. However, as previously noted, rates are likely to correct, as the current rate differential is too tight. Furthermore, the koruna benefits from strong seasonal support in November and December, which should help temper the current weakening pressure following the dovish CNB meeting. We therefore anticipate a new range of 24.350–24.400, little changed from our pre-meeting expectations.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment