


Open Banking, AI And The Future Of Financial Inclusion In The GCC: Insights From Halala Plus


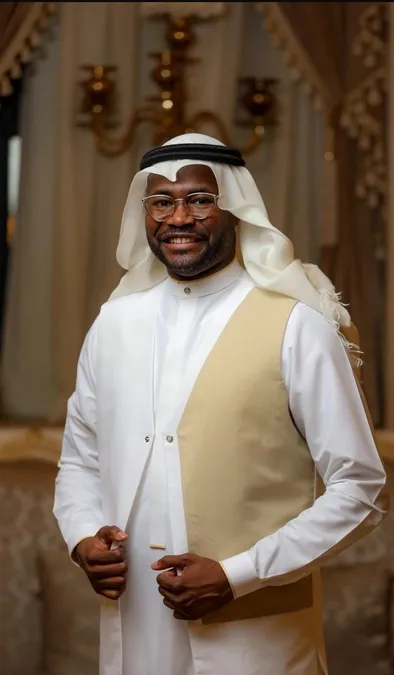
(MENAFN- Mid-East Info) Abdulhamid Ahmed, Co-founder and Technical Director of Halala Plus, discusses the evolution of digital financial services, the growing importance of open banking and artificial intelligence, and the innovations expected to shape the GCC's fintech landscape in 2027 and beyond.
Borderless Finance. AI-Native.
Your digital companion for smarter everyday choices. Built for how you live, earn, and grow. Move money at your pace with AI-powered finance, all in one tap.
Join the waiting list. Earn The financial services sector across the GCC and wider Middle East and North Africa (MENA) region is undergoing a significant transformation as open banking, artificial intelligence and digital innovation reshape how individuals manage their finances. With changing consumer expectations and evolving regulatory frameworks, fintech companies are introducing new solutions designed to make saving, investing and financial planning more accessible. However, challenges surrounding financial inclusion, data privacy, cybersecurity and consumer trust remain central to the industry's development. In this interview with Mid-East Information, Abdulhamid Ahmed, Co-founder and Technical Director of Halala Plus, shares his perspectives on the opportunities and challenges facing the region's fintech ecosystem, the role of technology in improving financial accessibility, and the trends expected to influence the future of digital finance. 1. How is open banking transforming the financial services landscape across the GCC, and the wider MENA region? Abdulhamid Ahmed: Open Banking is fundamentally transforming the region's financial paradigm, shifting it from closed institutional models to open ecosystem environments powered by APIs that place the customer at the center. Driven by forward-looking regulatory frameworks-such as those established by the Saudi Central Bank (SAMA) and regional central banks-Open Banking democratizes financial data securely. This empowers third-party providers to build secure, interconnected software layers on top of legacy banking infrastructure. Despite decades of traditional banking conservatism regarding customer data ownership and sharing, Open Banking has safely and authentically dismantled all legacy barriers. What was previously labeled as a data leak or security concern has now become a launchpad for innovative projects, unlocking advanced personal finance management, automated micro-investing, and seamless payment rails. This effectively transitions traditional banks from passive financial vaults into dynamic platforms for embedded financial innovation. 2. What are the biggest challenges preventing individuals and underserved communities from accessing financial services, and how can fintech innovation help address these gaps? Abdulhamid Ahmed: The primary barriers stem from high initial entry thresholds, strict regulatory requirements, complex traditional financial products, rigid credit scoring models, and psychological friction surrounding wealth management initiation. Consumers and individuals in underserved segments often feel that investing and financial planning require substantial capital reserves and deep market expertise. FinTech innovation bridges this gap by removing both technical and behavioral hurdles. Through automated micro-savings, zero-fee micro-investing, and alternative credit scoring via Open Banking, FinTech enables individuals to participate in the financial ecosystem using even fractional amounts (Halalas), transforming everyday spending into long-term investment assets. 3. How are changing consumer expectations influencing the development of digital banking and fintech solutions across the region? Abdulhamid Ahmed: The GCC boasts some of the highest smartphone penetration and digital connectivity rates globally. Consumer expectations are no longer benchmarked against traditional banking standards, but rather against fast-paced interactive digital apps that demand real-time responsiveness, hyper-personalization, and absolute ease of use. Today, consumers expect financial services to operate seamlessly and automatically in the background of their daily routines without requiring manual administrative overhead. This shift drives FinTech companies to build event-driven automated infrastructures where financial goals-such as saving, investing, or micro-insurance-happen automatically as an integral part of everyday retail transactions. Moreover, we have recently witnessed innovative fintech models emerge across the region that have outpaced traditional banks in total user adoption. 4. What role can open banking play in encouraging better financial management, savings habits, and greater financial inclusion? Abdulhamid Ahmed: Open Banking acts as a technical bridge providing comprehensive data visibility and frictionless real-time financial tracking. By enabling a unified and secure view of cash flows across multiple bank accounts, smart algorithms can dynamically analyze spending patterns. Rather than demanding users manually alter their lifestyles, Open Banking facilitates automated micro-savings mechanisms-such as transaction round-ups-where digital fractions (Halalas) are automatically swept into diversified investment portfolios or endowment vehicles, turning financial discipline into a sustainable, effortless habit. 5. How are artificial intelligence and data-driven technologies creating new opportunities for fintech companies and financial institutions? Abdulhamid Ahmed: Data is the fuel, and AI is the execution engine of modern FinTech. AI enables the transformation of operational Open Banking data into predictive intelligence, unlocking new horizons for: Predictive Robo-Advisory: Evolving from a standard market buzzword into a formal activity and licensed service granted by relevant authorities due to its critical role in managing investments and automatically balancing cash flows to channel surpluses into customized asset classes. Embedded & Customized Products: Providing immediate purchase coverage, insurance, or micro-coverages based on actual, real-time processed financial behavior rather than legacy credit scoring models. Early Fraud Detection: Protecting users in real-time via machine learning models that monitor suspicious activities across API endpoints. 6. What are the main challenges fintech startups face when navigating regulatory requirements, data privacy, and consumer trust? Abdulhamid Ahmed: The primary technical and operational challenge lies in balancing rapid go-to-market speed with strict compliance and data security. Dealing with Open Banking standards, regulatory sandboxes, and cybersecurity guidelines demands rigorous architectural discipline from day one. Furthermore, consumer trust in wealth management technologies requires absolute transparency; users must feel completely secure regarding data privacy and fund safety. We address this by implementing top-tier encryption standards (AES-256), strictly adhering to national data residency regulations within the Kingdom, and providing clear, granular consent frameworks for users. 7. How important is collaboration between fintech startups, traditional banks, and regulators in accelerating financial innovation? Abdulhamid Ahmed: Thanks to progressive regulations by relevant authorities mandating bank collaboration, partnerships have transitioned from being a mere choice to becoming the cornerstone of sustainable FinTech growth. Regulators provide the legislative frameworks ensuring security and consumer trust; traditional banks offer institutional stability and deep liquidity; while startups deliver technological agility, rapid development, and innovative user experiences. At Halala Plus, we view traditional financial institutions and merchants not as competitors, but as key ecosystem partners-true innovation happens when startup agility connects directly with enterprise infrastructure. 8. What inspired you to establish Halala Plus, and what specific financial challenges are you seeking to address through the platform? Abdulhamid Ahmed: Halala Plus originated from a fundamental observation: millions of digitally active individuals engage in daily transactions, yet most lack accessible, automated ways to build long-term wealth or contribute to social-impact assets (such as micro-awqaf/endowments). As software engineers and systems architects, we set out to build an engine that eliminates traditional savings and investment barriers. Using Open Banking and our proprietary automated payment processing engine, Halala Plus aggregates daily transaction fractions (Halalas and reward points) and converts these micro-amounts into automated savings and investment tools that grow individual wealth. 9. Looking ahead to 2027 and beyond, what emerging trends do you believe will shape the future of open banking and digital financial services in MENA? Abdulhamid Ahmed: Looking toward 2027, three main trends will reshape the sector: Transition from Open Banking to Open Finance: Expanding beyond bank accounts to include insurance, investments, and real estate financing, enabling comprehensive cross-asset automation. Autonomous Finance: Shifting financial decisions to operate entirely in the background, where AI agents manage liquidity, optimize savings yields, and execute micro-investments within pre-approved thresholds. Tokenization and Asset Fractionalization: Enabling retail consumers to own fractional shares of real-world assets and digital endowments through micro-transactions. 10. What advice would you offer to entrepreneurs seeking to build innovative fintech solutions that can contribute to a more inclusive financial ecosystem? Abdulhamid Ahmed: Design your product with absolute simplicity; the best financial tools conceal code complexity and algorithmic solutions behind an effortless user experience. Finally, partner early with regulators and financial institutions-building trust and alignment with the wider financial ecosystem is the true multiplier for your project's growth and expansion. Above all, focus primarily on solving concrete friction points rather than building technology for technology's sake. First, build your project on institutional-grade infrastructure from day one-regulatory compliance, cybersecurity, and data integrity cannot be retrofitted later.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment