


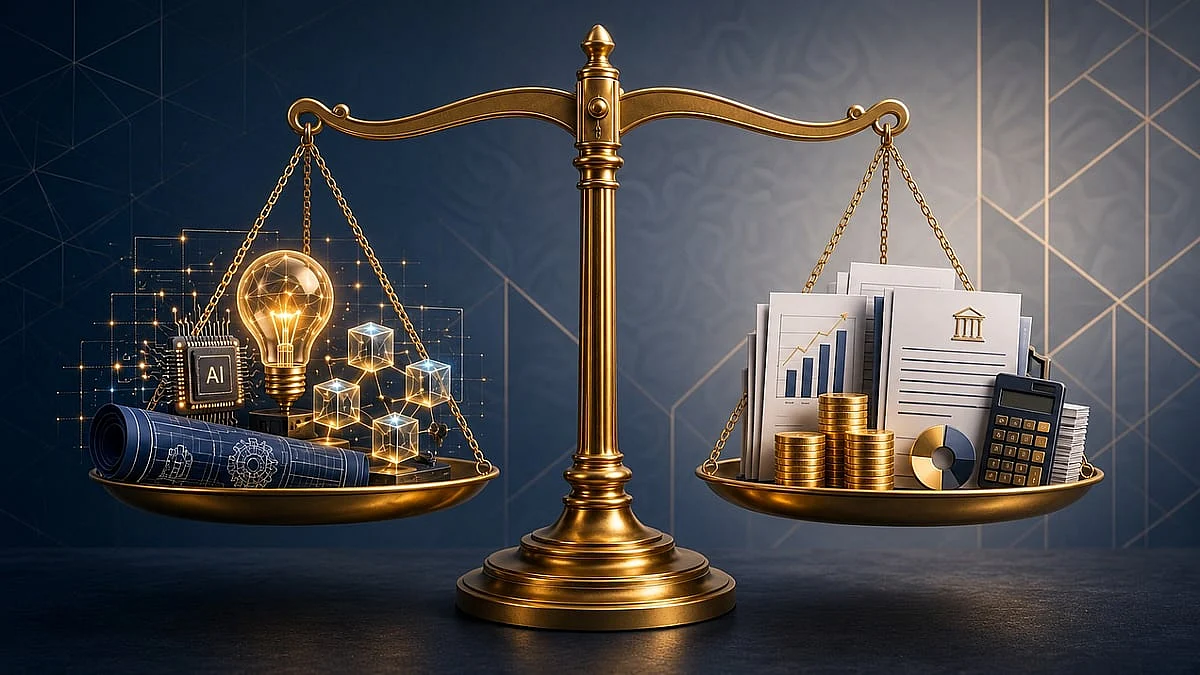
How R&D Costs Affect Your UAE Corporate Tax Bill In 2026


For Web3, blockchain and cryptocurrency businesses, that decision is whether development costs are capitalised or expensed. From 2026, the UAE's new R&D tax credit adds another consideration. The UAE has become a major destination for these businesses, drawing significant investment into software, digital platforms and technological infrastructure. Companies tend to focus on the business potential of that investment, while the accounting and tax implications receive less attention.
They deserve more. How R&D costs are recorded can make a considerable difference to taxable profit and to when the resulting tax becomes payable.
Research is expensed. Development may not be.
Under International Financial Reporting Standards (IFRS), the treatment of R&D spending depends on the nature and stage of the project.
Research means exploring new ideas, testing possibilities and assessing potential solutions. This spending is generally recognised as an expense when incurred. Development means turning an established concept into a product or system intended for use or sale. Under IAS 38, these costs must be capitalised once a company can demonstrate all six of the following conditions:
- The project is technically feasible.
Management intends to complete the project.
The company can use or sell the resulting product.Future economic benefits are reasonably expected.
Sufficient financial and technical resources are available.Development costs can be measured reliably.
Take a blockchain company experimenting with different security protocols. Its research costs would generally be expensed. Once it demonstrates that a proposed platform is technically achievable, commercially viable and adequately funded, qualifying development expenditure may need to be capitalised. That means recording those costs as an asset rather than immediately reducing reported profit.
Same investment. Dh72,000 more in first-year tax.
Consider a UAE technology company generating Dh2 million in profit before accounting for Dh1 million spent developing proprietary software.
If the expenditure qualifies as an immediate expense, taxable profit could fall to Dh1 million, resulting in Corporate Tax of Dh56,250 at the standard UAE rates.
If it must be capitalised, the outcome changes. Assuming the software is available for use and its cost is spread evenly over five years, the company recognises Dh200,000 a year. First-year taxable profit is Dh1.8 million, and Corporate Tax rises to Dh128,250.
That is Dh72,000 more in first-year Corporate Tax on the same Dh1 million investment. The example assumes no other tax adjustments, exemptions or credits.
This does not necessarily mean a higher lifetime tax burden. Capitalisation generally spreads deductions across future years, while immediate expensing can reduce the current year's liability. Earlier deductions may improve cash flow. Deferred deductions require businesses to anticipate future tax obligations.
But accounting treatment is not a discretionary tax-saving choice. Companies must follow the applicable accounting rules, record costs under the correct category and claim deductions only when they are allowed.
Why blockchain and crypto businesses should pay attention
Building a cryptocurrency exchange, digital asset custody platform, smart contract or blockchain system can involve considerable spending long before the business starts making money. The key is knowing at what point the work is no longer considered research and the development costs must be recorded as an asset.
Routine maintenance, marketing and ordinary operating costs should not automatically be classified as R&D. Reliable project records, development milestones and cost documentation can help establish the appropriate treatment and support future tax positions.
The UAE's new R&D tax credit
The UAE's Ministerial Decision No. 24 of 2026, applicable to tax periods beginning on or after 1 January 2026, introduces an additional consideration.
Eligible businesses may benefit from non-refundable tax credits at tiered rates of 15, 35 and 50 per cent, depending on qualifying expenditure and R&D staffing thresholds, subject to an Dh5 million annual qualifying expenditure ceiling and other approval requirements.
Certain capitalised development costs may also qualify, provided the relevant conditions are satisfied.
Plan for the tax, not just the technology
From my experience, good tax planning starts with knowing which costs can be deducted straight away and which must be capitalised.
For businesses working with new technologies, keeping proper records, classifying costs correctly and planning ahead can make a real difference to cash flow and overall financial performance. As more UAE companies invest in new technologies, they need to pay as much attention to the costs and financial impact of their projects as they do to developing the technology.
This article was contributed by Ezat Alnajm, CEO of Tulpar Global Taxation. He is based at Innovation City in the UAE and is an FTA Certified Tax Agent, Certified Transfer Pricing Expert and Anti-Money Laundering (AML) professional. His work focuses on UAE taxation, international reporting requirements and advisory services for digital asset businesses. He works with companies in Innovation City and other UAE free zones, helping them understand and meet their VAT, Corporate Tax and international reporting obligations, including CARF.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment