


Rates Spark: A Blue Wave In The US And Euro Inflation


The baseline case was a Democrat win, but the scale of the victory will give markets plenty to digest. A decisive victory helps ensure a smooth process, as there is little risk of the result being challenged. Trump is accepting the result, and in January we should have a new Congress taking office. We also avoid a gridlock situation with Congress split between Democrats and Republicans. These factors of relative stability should all help market sentiment.
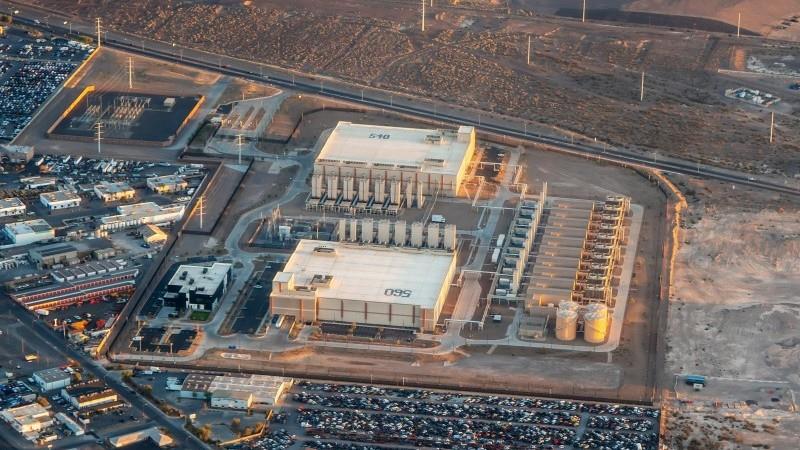
On the other hand, we should also place the Democrats' victory in the context of the current AI jitters in equity markets. Data centres have been a big topic in these elections, with the Democrats taking a firmer stance against the free market approach given to the AI sector by the government. Given much of US growth currently relies on the AI boom, stricter policy could start forming a headwind. Probably not something that will materialise in big changes in the near term, but definitely a trend to keep an eye on.
With Trump still in charge of foreign policy, inflation remains a bit of a wild card. The war with Iran is not over, and oil barely budged on the election results. Tariffs could make a return as one of Trump's favourite policy measures. Markets are sensitive to any inflation surprises in the data, and if another vector of inflation uncertainty were to be added, we could easily see rates rise further. Implied volatility measures suggest we should prepare for significant rate moves over the coming months.
Wednesday's events and market viewThe data highlight for the day in the eurozone is the flash CPI print for October. With most countries having reported their numbers already, headline inflation is seen rising to 4%. The core rate is expected to remain steady at 2.5%. The figures still point to another rate hike from the ECB in December. The ECB will publish its wage tracker and chief economist Lane, as well as France's Moulin, will speak.
The US will publish the ISM services, seen coming in only marginally softer at 54.8. Ahead of Friday's official US jobs data, markets will also eye the ADP employment change numbers. The trade balance and import/exports data round off the releases for the day.
In primary markets, Germany auctions 15y and 20y Bunds for a total of €2bn. The US Treasury makes its quarterly refunding announcement, where no changes to coupon issuance are expected.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment