


AB Inbev Reports Third Quarter 2026 Results


| Revenue +4.9% Revenue increased by 4.9% in 3Q26 with revenue per hl growth of 4.2% and by 5.4% in 9M26 with revenue per hl growth of 4.3%. Reported revenue increased by 9.1% in 3Q26 to 16 512 million USD and by 10.7% in 9M26 to 48 439 million USD, positively impacted by currency translation. 7.7% increase in combined revenues of megabrands in 3Q26, led by Corona, which grew by 20% outside of its home market. 35% increase in revenue of no-alcohol beer in 3Q26. 19% increase in revenue of Beyond Beer in 3Q26. 45% increase in Gross Merchandise Value (GMV) from sales of third-party products through BEES Marketplace to reach 1.4 billion USD in 3Q26. Volumes +0.4% Volumes increased by 0.4% in 3Q26, with beer volumes down by 0.1% and non-beer volumes up by 4.0%. Volumes increased by 0.7% in 9M26, with beer volumes up by 0.7% and non-beer volumes up by 0.3%. | Normalized EBITDA +3.9% Normalized EBITDA increased by 3.9% to 5 957 million USD in 3Q26, with a margin contraction of 34bps to 36.1%. Normalized EBITDA increased by 5.0% to 17 332 million USD in 9M26, with a margin contraction of 15bps to 35.8%. Underlying Profit 2 396 million USD Underlying Profit was 2 396 million USD in 3Q26 compared to 1 970 million USD in 3Q25 and was 6 710 million USD in 9M26 compared to 5 526 million USD in 9M25. Reported profit attributable to equity holders of AB InBev was 1 597 million USD in 3Q26 compared to 1 054 million USD in 3Q25 and was 7 910 million USD in 9M26 compared to 4 878 million USD in 9M25. Underlying EPS 1.21 USD Underlying EPS increased by 22.4% to 1.21 USD in 3Q26, compared to 0.99 USD in 3Q25, and increased by 22.2% to 3.40 USD in 9M26, compared to 2.78 USD in 9M25. On a constant currency basis, Underlying EPS increased by 13.9% in 3Q26 and by 12.0% in 9M26. |
| Capital Allocation 0.40 EUR interim dividend The AB InBev Board of Directors has approved an interim dividend of 0.40 EUR per share for the fiscal year 2026 compared to 0.15 EUR per share for the fiscal year 2025. A timeline showing the ex-dividend, record and payment dates can be found on page 13. |
| 1The enclosed information constitutes inside information as defined in Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse, and regulated information as defined in the Belgian Royal Decree of 14 November 2007 regarding the duties of issuers of financial instruments which have been admitted for trading on a regulated market. |
Management comments
Solid top- and bottom-line performance with volume growth, revenue up 4.9% and Underlying EPS up 22%
The consistent execution of our strategy, together with the strength of our diversified footprint, brand portfolio and best-in-class capabilities, delivered another quarter of compounding top- and bottom-line growth.
Revenue increased by 4.9%, with total volume growth of 0.4% and a revenue per hl increase of 4.2%, driven by revenue growth management and positive mix from premiumization and Beyond Beer. Overall beer volumes were flattish, as broad-based growth across our footprint was primarily offset by a challenging industry in China. We delivered record high third quarter volumes in 15 markets, including Colombia, Peru, Ecuador, South Africa, the Dominican Republic and India.
EBITDA increased by 3.9%, reflecting a step-up in sales and marketing investment to activate key mega platforms this quarter, as well as commodity cost headwinds, which were partially offset by disciplined overhead management. EBIT increased by 6.0% and Underlying EPS by 22%, as we continue to optimize the business and drive operating leverage through the P&L.
Key highlights from the quarter included: gaining or maintaining market share in an estimated two-thirds of our markets; continued momentum across our global premium brands, with Corona, Stella Artois and Michelob Ultra delivering revenue growth of 20%, 19% and 50%, respectively, outside of their home markets; continued growth across our Balanced Choices and Beyond Beer portfolios, with no-alcohol beer revenue increasing by 35% and Beyond Beer revenue by 19%; and BEES Marketplace quarterly GMV increasing by 45% to 1.4 billion USD.
Progressing our strategic priorities
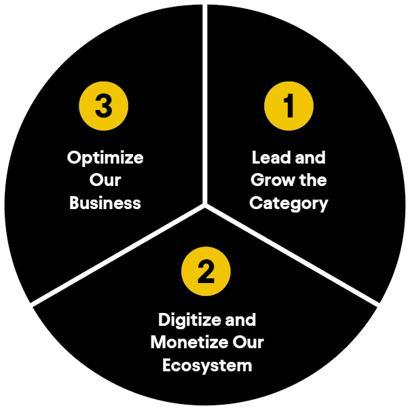
We are executing on three key strategic pillars to deliver consistent compounding growth and long-term value creation.
(1) Lead and grow the category:
We strengthened our portfolio brand power and estimate that we gained or maintained share in two-thirds of our markets in 3Q26, reflecting the effectiveness of our execution and consumer-focused investments.
(2) Digitize and monetize our ecosystem:
BEES Marketplace GMV increased by 45% versus 3Q25 to 1.4 billion USD from third-party products. Overall BEES GMV increased by 12% versus 3Q25 to 15.9 billion USD.
(3) Optimize our business:
Our stronger balance sheet and free cash flow generation provide increased flexibility in our capital allocation choices. The AB InBev Board of Directors has approved an interim dividend of 0.40 EUR per share compared to 0.15 EUR per share in FY25.
(1) Lead and grow the category
We are executing on our four category expansion levers to drive growth across our portfolio, expand occasions and increase participation. In 3Q26, we estimate that the number of legal drinking age consumers purchasing our portfolio increased, driven by gains in our premium, no-alcohol beer and Beyond Beer brands.
-
Core Superiority: Our mainstream beer portfolio delivered revenue growth of 2.1% in 3Q26, driven by double-digit growth in Colombia and Peru and high-single digit growth in Mexico and the Dominican Republic.
-
Premiumization: Our above core beer portfolio delivered an 8.6% revenue increase in 3Q26, led by Corona, Stella Artois and Michelob Ultra, which grew revenue by 20%, 19% and 50%, respectively, outside of their home markets. Corona delivered double-digit volume growth in 37 markets, and Michelob Ultra continued its expansion across Latin America, with 60% of its volume growth coming from markets outside of the US.
-
Balanced Choices: Our Balanced Choices portfolio, including low carb, low calorie, sugar free, gluten free and no-alcohol beer brands, delivered revenue growth of 19% in 3Q26. Our no-alcohol beer portfolio led performance, with revenue up by 35% and estimated share gains strengthening our leadership in no-alcohol beer by value, according to Nielsen.
-
Beyond Beer: Our portfolio delivered revenue growth of 19% in 3Q26, led by Cutwater in the US, which grew revenue by high-thirties, and the continued global expansion of Flying Fish.
(2) Digitize and monetize our ecosystem
-
Digitizing our relationships with more than 6 million customers globally: As of 30 September 2026, BEES was live in 30 markets with 73% of our revenues captured through B2B digital platforms. In 3Q26, BEES captured 15.9 billion USD in GMV, up 12% versus 3Q25.
-
Monetizing our route-to-market; approaching 1.5 billion USD in quarterly GMV: BEES Marketplace GMV increased by 45% versus 3Q25 to reach 1.4 billion USD, further monetizing our route-to-market and strengthening our digital ecosystem.
-
Leading the way in DTC solutions: Our digital DTC megabrands, Zé Delivery, TaDa Delivery and PerfectDraft, served 13 million active consumers and delivered 158 million USD in revenue, 9% growth versus 3Q25. Sales of third-party products through our DTC marketplace generated 49 million USD in GMV, a 57% increase versus 3Q25.
(3) Optimize our business
-
Maximizing value creation: Our stronger balance sheet and free cash flow generation provide increased flexibility in our capital allocation choices. The AB InBev Board of Directors has approved an interim dividend of 0.40 EUR per share compared to 0.15 EUR per share in FY25, consistent with our ambition for a progressive dividend over time. As of 26 October 2026, we have completed 2.6 billion USD of our 6 billion USD share buyback program announced on 30 October 2025.
-
Advancing our sustainability priorities: Our water use efficiency ratio improved to 2.3 hl per hl in 9M26 versus 2.4 hl per hl in 9M25. Our average energy efficiency globally improved to 81.2 MJ/hl in 9M26 versus 84.6 MJ/hl in 9M25. Our absolute Scopes 1 and 2 emissions were 2.3 million metric tons of CO2e in 9M26, a 1.8% decrease compared to 9M25.
Consistent execution and compounding growth
In 9M26, our business delivered revenue growth of 5.4%, EBITDA growth of 5.0% and an Underlying EPS increase of 22%, reflecting the momentum of our portfolio and the effectiveness of our commercial capabilities. We continued to invest in our megabrands, growth platforms and innovation to provide consumers with more choices across more occasions.
The strength of our ownership culture and execution, together with our best-in-class capabilities, reinforce our confidence in our ability to deliver our FY26 outlook. As we progress through the next phase of our strategy, we remain focused on creating superior shareholder value by delivering consistent, compounding results, investing to accelerate growth and increasing capital allocation flexibility.
2026 Outlook
(i) Overall Performance: We expect our EBITDA to grow in line with our medium-term outlook of between 4-8%. The outlook for FY26 reflects our current assessment of inflation and other macroeconomic conditions.
(ii) Net Finance Costs: Net pension interest expenses and accretion expenses are expected to be in the range of 190 to 220 million USD per quarter, depending on currency and interest rate fluctuations. We expect the average gross debt coupon in FY26 to be approximately 4%.
(iii) Effective Tax Rate (ETR): We expect the normalized ETR in FY26 to be in the range of 26% to 28%. The ETR outlook does not consider the impact of potential future changes in legislation.
(iv) Net Capital Expenditure: We expect net capital expenditure of between 3.5 and 4.0 billion USD in FY26.
| Figure 1. Consolidated performance | |||||||||
| in USD Mio, except EPS in USD per share and Volumes in thousand hls | 3Q25 | 3Q26 | Organic | ||||||
| growth | |||||||||
| Volumes | 142 319 | 142 313 | 0.4 | % | |||||
| Beer | 124 692 | 124 370 | (0.1 | )% | |||||
| Non-Beer | 17 627 | 17 943 | 4.0 | % | |||||
| Revenue | 15 133 | 16 512 | 4.9 | % | |||||
| Gross profit | 8 537 | 9 302 | 5.3 | % | |||||
| Gross margin | 56.4 | % | 56.3 | % | 20bps | ||||
| Normalized EBITDA | 5 594 | 5 957 | 3.9 | % | |||||
| Normalized EBITDA margin | 37.0 | % | 36.1 | % | (34)bps | ||||
| Normalized EBIT | 4 205 | 4 538 | 6.0 | % | |||||
| Normalized EBIT margin | 27.8 | % | 27.5 | % | 27bps | ||||
| Profit attributable to equity holders of AB InBev | 1 054 | 1 597 | |||||||
| Underlying Profit | 1 970 | 2 396 | |||||||
| Basic EPS | 0.53 | 0.81 | |||||||
| Underlying EPS | 0.99 | 1.21 |
| 9M25 | 9M26 | Organic | |||||||
| growth | |||||||||
| Volumes | 421 934 | 422 726 | 0.7 | % | |||||
| Beer | 367 697 | 369 796 | 0.7 | % | |||||
| Non-Beer | 54 237 | 52 930 | 0.3 | % | |||||
| Revenue | 43 764 | 48 439 | 5.4 | % | |||||
| Gross profit | 24 566 | 27 528 | 6.6 | % | |||||
| Gross margin | 56.1 | % | 56.8 | % | 65bps | ||||
| Normalized EBITDA | 15 750 | 17 332 | 5.0 | % | |||||
| Normalized EBITDA margin | 36.0 | % | 35.8 | % | (15)bps | ||||
| Normalized EBIT | 11 805 | 13 215 | 7.0 | % | |||||
| Normalized EBIT margin | 27.0 | % | 27.3 | % | 40bps | ||||
| Profit attributable to equity holders of AB InBev | 4 878 | 7 910 | |||||||
| Underlying Profit | 5 526 | 6 710 | |||||||
| Basic EPS | 2.46 | 4.01 | |||||||
| Underlying EPS | 2.78 | 3.40 |
| Figure 2. Volumes | ||||||||||||||||
| in thousand hls | 3Q25 | Scope |
Organic growth |
3Q26 |
Organic growth |
|||||||||||
| Total | Beer | |||||||||||||||
| North America | 21 896 | 165 | (541 | ) | 21 520 | (2.5 | )% | (2.2 | )% | |||||||
| Middle Americas | 36 915 | (596 | ) | 2 648 | 38 967 | 7.3 | % | 6.9 | % | |||||||
| South America | 36 922 | - | 291 | 37 213 | 0.8 | % | 0.4 | % | ||||||||
| EMEA | 24 149 | (67 | ) | 598 | 24 680 | 2.5 | % | 2.4 | % | |||||||
| Asia Pacific | 22 301 | (25 | ) | (2 454 | ) | 19 821 | (11.0 | )% | (11.0 | )% | ||||||
| Global Export and Holding Companies | 136 | 6 | (29 | ) | 112 | (20.8 | )% | (20.8 | )% | |||||||
| AB InBev Worldwide | 142 319 | (518 | ) | 512 | 142 313 | 0.4 | % | (0.1 | )% |
| 9M25 | Scope |
Organic growth |
9M26 |
Organic growth |
||||||||||||
| Total | Beer | |||||||||||||||
| North America | 64 115 | 286 | (1 320 | ) | 63 081 | (2.1 | )% | (2.0 | )% | |||||||
| Middle Americas | 110 818 | (1 958 | ) | 6 087 | 114 946 | 5.6 | % | 5.8 | % | |||||||
| South America | 112 011 | - | 632 | 112 643 | 0.6 | % | 1.6 | % | ||||||||
| EMEA | 69 073 | (297 | ) | 1 074 | 69 850 | 1.6 | % | 1.6 | % | |||||||
| Asia Pacific | 65 665 | (64 | ) | (3 646 | ) | 61 955 | (5.6 | )% | (5.5 | )% | ||||||
| Global Export and Holding Companies | 252 | 28 | (28 | ) | 251 | (10.1 | )% | (10.1 | )% | |||||||
| AB InBev Worldwide | 421 934 | (2 006 | ) | 2 798 | 422 726 | 0.7 | % | 0.7 | % |
Key Markets Performance
United States: Portfolio momentum drove continued market share gains in beer and Beyond Beer
-
Operating performance:
-
3Q26: Revenue declined by 1.2% with revenue per hl increasing by 1.5%, driven by revenue management and positive brand mix. Sales-to-retailers (STRs) declined by 3.1%, estimated to have outperformed a soft industry. Sales-to-wholesalers (STWs) declined by 2.7%. EBITDA decreased by 4.0%, reflecting increased investment in sales and marketing and elevated commodity and transportation costs.
9M26: Revenue increased by 0.8%, with revenue per hl increasing by 3.0%. STRs declined by 1.7% and STWs were down by 2.1%. Our STRs and STWs tend to converge on a full year basis. EBITDA decreased by 1.3%.
Mexico: Market share gain and margin expansion drove mid-single digit volume growth and double-digit bottom line growth
-
Operating performance:
-
3Q26: Revenue increased by high-single digits, with volumes growing by mid-single digits, driven by market share gain and industry growth. Revenue per hl increased by low-single digits, driven by revenue management. EBITDA grew by low-teens with margin expansion.
9M26: Revenue grew by high-single digits, with revenue per hl growth of mid-single digits and volume increasing by low-single digits, outperforming the industry. EBITDA grew by high-single digits with margin expansion.
Colombia: Record high volumes and margin expansion drove double-digit top- and bottom-line growth
-
Operating performance:
-
3Q26: Revenue increased by mid-teens, with volumes growing by mid-single digits and our portfolio estimated to have gained share of total alcohol. Revenue per hl increased by high-single digits, driven by revenue management and premiumization. EBITDA grew by high-teens with margin expansion.
9M26: Revenue grew by mid-teens with high-single digit revenue per hl growth. Volumes increased by high-single digits. EBITDA grew by mid-teens with margin expansion.
Brazil: Market share momentum and volume growth drove mid-single digit top- and bottom-line growth
-
Operating performance:
-
3Q26: Revenue increased by 5.3%, with total volume growth of 1.4% and revenue per hl growth of 3.9%, driven by revenue management and premiumization. Beer volumes increased by 0.5% and non-beer volumes increased by 3.6%. EBITDA increased by 6.1%, with margin expansion of 26bps as disciplined revenue and cost management more than offset increased sales and marketing investment.
9M26: Revenue grew by 7.1% with revenue per hl growth of 6.0%. Beer volumes grew by 2.1% and non-beer volumes declined by 1.7%, resulting in total volume growth of 1.1%. EBITDA increased by 10.6% with margin expansion of 106bps.
Europe: Market share gains and premiumization drove continued top-line growth
-
Operating performance:
-
3Q26: Volumes were flat, estimated to have gained or maintained share in a majority of our key markets. Revenue and revenue per hl grew slightly, driven by premiumization. EBITDA declined by mid-single digits, with top-line growth offset by increased sales and marketing investment and elevated commodity costs.
9M26: Volumes grew slightly, estimated to have gained or maintained share in a majority of our key markets. Revenue and revenue per hl increased by low-single digits driven by premiumization. EBITDA declined by mid-single digits.
South Africa: Record high volumes and premiumization drove high-single digit top-line growth
-
Operating performance:
-
3Q26: Revenue increased by high-single digits with revenue per hl growth of mid-single digits, driven by revenue management and premiumization. Volumes grew by low-single digits, estimated to have underperformed the industry, as we cycled a strong performance in 3Q25. EBITDA was flattish with top-line growth offset by elevated commodity and distribution costs and the phasing of sales and marketing investments.
9M26: Revenue and revenue per hl increased by mid-single digits. Volumes grew by low-single digits. EBITDA grew by low-single digits.
China: Top- and bottom-line declined, impacted by volume performance in a challenging industry
-
Operating performance:
-
3Q26: Volumes declined by 16.8%, as we managed inventory levels in a challenging industry, which was impacted by abnormal weather and continued weakness in the on-premise channel. We estimate the industry declined by low-teens in our footprint. Revenue per hl was flat, resulting in a revenue decline of 16.8%. EBITDA declined by 30.5%, impacted by top-line performance and operational deleverage.
9M26: Volumes declined by 9.7% in an industry that we estimate declined by mid-single digits. Revenue per hl decreased by 0.1% resulting in a revenue decline of 9.8%. EBITDA declined by 18.5%.
Highlights from our other markets
-
Canada: Our portfolio gained share of both beer and Beyond Beer in 3Q26, according to our estimates, remaining the #1 share gainer in both categories year-to-date. Revenue and revenue per hl grew by low-single digits, while volumes declined by low-single digits in a soft industry. Performance was led by Michelob Ultra, Busch and Corona, which were the top three share gainers in the beer industry, while our Beyond Beer portfolio delivered mid-single digit revenue growth.
Peru: Volumes grew by low-teens to reach a record high for the third quarter, with our portfolio estimated to have gained share of total alcohol. Performance was led by our mainstream beer brands and supported by triple-digit volume growth in our Beyond Beer portfolio. Revenue increased by mid-teens, with low-single digit revenue per hl growth.
Ecuador: Volumes grew by mid-teens to reach a record high for the third quarter, led by our above core beer portfolio. Revenue increased by high-teens, with mid-single digit revenue per hl growth driven by revenue management and premiumization.
Argentina: Volumes declined by mid-single digits in 3Q26, as overall consumer demand continued to be constrained by an unfavorable macro environment. Revenue grew by strong double-digits driven by revenue management.
Africa excluding South Africa: In 3Q26, Nigeria beer volumes grew by high-single digits, supported by an improved industry which cycled a soft performance in 3Q25. Revenue grew by low-teens.
In our other markets in Africa, revenue grew in aggregate by high-single digits and volumes by mid-single digits, with record high third quarter volumes in Mozambique, Tanzania and Uganda. South Korea: Volumes declined by low-single digits in 3Q26, estimated to have outperformed a soft industry, with performance led by our premium beer brands. We continued to expand our portfolio in Beyond Beer, with the launch of Nutrl and Chalrang Soju. Revenue and revenue per hl declined by low-single digits, impacted by channel and packaging mix.
Consolidated Income Statement
| Figure 3. Consolidated income statement | |||||||||
| in USD Mio | 3Q25 | 3Q26 | Organic | ||||||
| growth | |||||||||
| Revenue | 15 133 | 16 512 | 4.9 | % | |||||
| Cost of sales | (6 596 | ) | (7 210 | ) | (4.4 | )% | |||
| Gross profit | 8 537 | 9 302 | 5.3 | % | |||||
| SG&A | (4 535 | ) | (4 979 | ) | (4.1 | )% | |||
| Other operating income/(expenses) | 203 | 215 | (8.3 | )% | |||||
| Normalized EBIT | 4 205 | 4 538 | 6.0 | % | |||||
| Non-underlying items above EBIT | 55 | (11 | ) | ||||||
| Net finance income/(expense) | (1 165 | ) | (908 | ) | |||||
| Non-underlying net finance income/(expense) | (947 | ) | (791 | ) | |||||
| Share of results of associates | 110 | 97 | |||||||
| Income tax expense | (726 | ) | (952 | ) | |||||
| Profit | 1 532 | 1 973 | |||||||
| Profit attributable to non-controlling interest | 478 | 376 | |||||||
| Profit attributable to equity holders of AB InBev | 1 054 | 1 597 | |||||||
| . | |||||||||
| Normalized EBITDA | 5 594 | 5 957 | 3.9 | % | |||||
| Underlying Profit | 1 970 | 2 396 |
| 9M25 | 9M26 | Organic | |||||||
| growth | |||||||||
| Revenue | 43 764 | 48 439 | 5.4 | % | |||||
| Cost of sales | (19 198 | ) | (20 912 | ) | (3.9 | )% | |||
| Gross profit | 24 566 | 27 528 | 6.6 | % | |||||
| SG&A | (13 347 | ) | (14 897 | ) | (5.7 | )% | |||
| Other operating income/(expenses) | 585 | 584 | (9.2 | )% | |||||
| Normalized EBIT | 11 805 | 13 215 | 7.0 | % | |||||
| Non-underlying items above EBIT | (39 | ) | 3 | ||||||
| Net finance income/(expense) | (3 210 | ) | (3 015 | ) | |||||
| Non-underlying net finance income/(expense) | (580 | ) | 1 242 | ||||||
| Share of results of associates | 246 | 244 | |||||||
| Non-underlying share of results of associates | 9 | - | |||||||
| Income tax expense | (2 130 | ) | (2 656 | ) | |||||
| Profit | 6 100 | 9 033 | |||||||
| Profit attributable to non-controlling interest | 1 222 | 1 123 | |||||||
| Profit attributable to equity holders of AB InBev | 4 878 | 7 910 | |||||||
| Normalized EBITDA | 15 750 | 17 332 | 5.0 | % | |||||
| Underlying Profit | 5 526 | 6 710 |
Non-underlying items above EBIT & Non-underlying share of results of associates
| Figure 4. Non-underlying items above EBIT & Non-underlying share of results of associates | ||||||||||||
| in USD Mio | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||||||
| Restructuring | (20 | ) | (23 | ) | (68 | ) | (56 | ) | ||||
| Business and asset disposals (including impairment losses) | 94 | 12 | 47 | 73 | ||||||||
| Claims and legal costs | (18 | ) | - | (18 | ) | - | ||||||
| Acquisition-related costs (business combinations) | - | - | - | (14 | ) | |||||||
| Non-underlying items in EBIT | 55 | (11 | ) | (39 | ) | 3 | ||||||
| Non-underlying share of results of associates | - | - | 9 | - |
Normalized EBIT excludes negative non-underlying items of 11 million USD in 3Q26 and positive non-underlying items of 3 million USD in 9M26.
Net finance income/(expense)
| Figure 5. Net finance income/(expense) | ||||||||||||
| in USD Mio | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||||||
| Net interest expense | (675 | ) | (600 | ) | (1 959 | ) | (1 796 | ) | ||||
| Accretion expense and interest on pensions | (228 | ) | (145 | ) | (580 | ) | (558 | ) | ||||
| Other financial results | (262 | ) | (163 | ) | (672 | ) | (662 | ) | ||||
| Net finance income/(expense) | (1 165 | ) | (908 | ) | (3 210 | ) | (3 015 | ) |
Non-underlying net finance income/(expense)
| Figure 6. Non-underlying net finance income/(expense) | |||||||||||
| in USD Mio | 3Q25 | 3Q26 | 9M25 | 9M26 | |||||||
| Mark-to-market | (947 | ) | (800 | ) | (608 | ) | 1 233 | ||||
| Gain/(loss) on bond redemption and other | - | 10 | 29 | 10 | |||||||
| Non-underlying net finance income/(expense) | (947 | ) | (791 | ) | (580 | ) | 1 242 |
Non-underlying net finance income includes mark-to-market gains or losses on derivative instruments entered into in order to hedge our share-based payment programs and shares issued in relation to the combinations with Grupo Modelo and SAB.
The number of shares covered by the hedging of our share-based payment program, the deferred share instrument and the restricted shares are shown below, together with the opening and closing share prices.
| Figure 7. Non-underlying equity derivative instruments | ||||||||
| 3Q25 | 3Q26 | 9M25 | 9M26 | |||||
| Share price at the start of the period (Euro) | 58.24 | 72.66 | 48.25 | 54.90 | ||||
| Share price at the end of the period (Euro) | 50.80 | 65.32 | 50.80 | 65.32 | ||||
| Number of equity derivative instruments at the end of the period (in million) | 100.5 | 90.5 | 100.5 | 90.5 |
Income tax expense
| Figure 8. Income tax expense | ||||||||
| in USD Mio | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||
| Income tax expense | 726 | 952 | 2 130 | 2 656 | ||||
| Effective tax rate | 33.8% | 33.7% | 26.7% | 23.2% | ||||
| Normalized effective tax rate | 25.1% | 26.9% | 25.4% | 26.1% |
The 9M26 effective tax rate was positively impacted by non-taxable gains from derivatives related to the hedging of share-based payment programs and the hedging of the shares issued in a transaction related to the combinations with Grupo Modelo and SAB, while the 9M25 effective tax rate was negatively impacted by non-deductible losses from these derivatives. The increase in Normalized ETR in 3Q26 and 9M26 compared to 3Q25 and 9M25 was mainly driven by country mix.
Underlying EPS
| Figure 9. Underlying EPS | ||||||||||||
| in USD per share, except number of shares in million | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||||||
| Normalized EBITDA | 2.82 | 3.02 | 7.93 | 8.78 | ||||||||
| Depreciation, amortization and impairment | (0.70 | ) | (0.72 | ) | (1.99 | ) | (2.09 | ) | ||||
| Normalized EBIT | 2.12 | 2.30 | 5.94 | 6.70 | ||||||||
| Net finance income/(expense) | (0.59 | ) | (0.46 | ) | (1.62 | ) | (1.53 | ) | ||||
| Income tax expense | (0.38 | ) | (0.49 | ) | (1.10 | ) | (1.35 | ) | ||||
| Associates & non-controlling interests | (0.16 | ) | (0.14 | ) | (0.47 | ) | (0.45 | ) | ||||
| Hyperinflation impacts | 0.01 | 0.01 | 0.03 | 0.03 | ||||||||
| Underlying EPS | 0.99 | 1.21 | 2.78 | 3.40 | ||||||||
| Weighted average number of ordinary and restricted shares | 1 986 | 1 973 | 1 986 | 1 973 |
Reconciliation of IFRS and Non-IFRS Financial Measures
Profit attributable to equity holders and Underlying Profit
| Figure 10. Underlying Profit | ||||||||
| in USD Mio | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||
| Profit attributable to equity holders of AB InBev | 1 054 | 1 597 | 4 878 | 7 910 | ||||
| Net impact of non-underlying items on profit | 898 | 777 | 593 | (1 258) | ||||
| Hyperinflation impacts | 18 | 23 | 54 | 57 | ||||
| Underlying Profit | 1 970 | 2 396 | 5 526 | 6 710 |
Basic and Underlying EPS
| Figure 11. Basic and Underlying EPS | ||||||||||
| in USD per share, except number of shares in million | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||||
| Basic EPS | 0.53 | 0.81 | 2.46 | 4.01 | ||||||
| Net impact of non-underlying items | 0.45 | 0.39 | 0.30 | (0.64 | ) | |||||
| Hyperinflation impacts | 0.01 | 0.01 | 0.03 | 0.03 | ||||||
| Underlying EPS | 0.99 | 1.21 | 2.78 | 3.40 | ||||||
| FX translation impact | - | (0.08 | ) | - | (0.28 | ) | ||||
| Underlying EPS in constant currency | 0.99 | 1.13 | 2.78 | 3.12 | ||||||
| Weighted average number of ordinary and restricted shares | 1 986 | 1 973 | 1 986 | 1 973 |
Profit attributable to equity holders and Normalized EBITDA
| Figure 12. Reconciliation of Normalized EBITDA to Profit attributable to equity holders of AB InBev | ||||||||
| in USD Mio | 3Q25 | 3Q26 | 9M25 | 9M26 | ||||
| Profit attributable to equity holders of AB InBev | 1 054 | 1 597 | 4 878 | 7 910 | ||||
| Non-controlling interests | 478 | 376 | 1 222 | 1 123 | ||||
| Profit | 1 532 | 1 973 | 6 100 | 9 033 | ||||
| Income tax expense | 726 | 952 | 2 130 | 2 656 | ||||
| Share of results of associates | (110) | (97) | (246) | (244) | ||||
| Non-underlying share of results of associates | - | - | (9) | - | ||||
| Net finance (income)/expense | 1 165 | 908 | 3 210 | 3 015 | ||||
| Non-underlying net finance (income)/expense | 947 | 791 | 580 | (1 242) | ||||
| Non-underlying items above EBIT (incl. impairment losses) | (55) | 11 | 39 | (3) | ||||
| Normalized EBIT | 4 205 | 4 538 | 11 805 | 13 215 | ||||
| Depreciation, amortization and impairment | 1 390 | 1 419 | 3 945 | 4 117 | ||||
| Normalized EBITDA | 5 594 | 5 957 | 15 750 | 17 332 |
Normalized EBITDA, Normalized EBIT and Underlying Profit are non-IFRS financial measures used by AB InBev to reflect the company's underlying performance. Underlying EPS and constant currency Underlying EPS are non-IFRS financial measures that AB InBev believes are useful to investors because they facilitate comparisons of EPS from period to period.
Normalized EBITDA is calculated by adjusting profit attributable to equity holders of AB InBev to exclude: (i) non-controlling interest; (ii) income tax expense; (iii) share of results of associates; (iv) non-underlying share of results of associates; (v) net finance income or cost; (vi) non-underlying net finance income or cost; (vii) non-underlying items above EBIT; and (viii) depreciation, amortization and impairment.
Underlying Profit is calculated by adjusting profit attributable to equity holders of AB InBev to exclude: (i) non-underlying items and (ii) hyperinflation impacts. Underlying EPS is calculated as Underlying Profit divided by the weighted average number of ordinary and restricted shares. Constant currency Underlying EPS is calculated as Underlying EPS excluding the effects of foreign currency translation by translating current period figures using the exchange rates from the same period in the prior year.
Normalized EBITDA, Normalized EBIT and Underlying Profit are not accounting measures under IFRS and should not be considered as an alternative to profit attributable to equity holders as a measure of operational performance, or an alternative to cash flow as a measure of liquidity. Underlying EPS and constant currency Underlying EPS are not accounting measures under IFRS and should not be considered as alternatives to earnings per share as a measure of operating performance on a per share basis. These non-IFRS financial measures do not have a standard calculation method and AB InBev's definition of Normalized EBITDA, Normalized EBIT, Underlying Profit, Underlying EPS and constant currency Underlying EPS may not be comparable to that of other companies.
Interim 2026 dividend
The AB InBev Board of Directors has approved an interim dividend of 0.40 EUR per share for the fiscal year 2026. In line with the Company's financial discipline and deleveraging objectives, the interim dividend balances the Company's capital allocation priorities and dividend policy while returning cash to shareholders. A timeline showing the ex-dividend, record and payment dates can be found below:
| Interim dividend timeline | ||||||
| Ex-dividend date | Record Date | Payment date | ||||
| Euronext | 19 November 2026 | 20 November 2026 | 23 November 2026 | |||
| MEXBOL | 19 November 2026 | 20 November 2026 | 23 November 2026 | |||
| JSE | 18 November 2026 | 20 November 2026 | 23 November 2026 | |||
| NYSE (ADR program) | 20 November 2026 | 20 November 2026 | 16 December 2026 | |||
| Restricted Shares | 19 November 2026 | 20 November 2026 | 23 November 2026 |
Notes
To facilitate the understanding of AB InBev's underlying performance, the analyses of growth, including all comments in this press release, unless otherwise indicated, are based on organic growth and normalized numbers. In other words, financials are analyzed eliminating the impact of changes in currencies on translation of foreign operations, and scope changes. Since 1Q24, the definition of organic revenue growth has been amended to cap the price growth in Argentina to a maximum of 2% per month (26.8% year-over-year). Corresponding adjustments are made to all income statement related items in the organic growth calculations through scope changes. Scope changes also represent the impact of acquisitions and divestitures, the start or termination of activities or the transfer of activities between segments, curtailment gains and losses and year over year changes in accounting estimates and other assumptions that management does not consider as part of the underlying performance of the business. Effective 1 January 2026, Cervecería Bucanero S.A., a Cuban company in which we indirectly hold a 50% equity interest through our subsidiary Ambev, is accounted for as an associate using the equity method of accounting. Furthermore, the company performed changes in classification in 3Q26 compared to 3Q25. The impact of these changes in presentation are reflected as scope changes. Beer volumes and revenue include primarily beer, no-alcohol beer, other malt-based alcohol beverages and spirits-based beverages. Non-beer volumes and revenue include primarily carbonated soft drinks and energy drinks. In addition, beer and non-beer categories include not only brands that we own or license, but also third-party brands that we brew and sell, and third-party products that we sell through our distribution network. The organic growth of our global brands, Budweiser, Stella Artois, and Corona excludes exports to Australia for which a perpetual license was granted to a third party upon disposal of the Australia operations in 2020. All references per hectoliter (per hl) exclude US non-beverage activities. Whenever presented in this document, all performance measures (EBITDA, EBIT, profit, tax rate, EPS) are presented on a“normalized” basis, which means they are presented before non-underlying items. Non-underlying items are either income or expenses which do not occur regularly as part of the normal activities of the Company. They are presented separately because they are important for the understanding of the underlying sustainable performance of the Company due to their size or nature. Normalized measures are additional measures used by management and should not replace the measures determined in accordance with IFRS as an indicator of the Company's performance. We are reporting the results from Argentina applying hyperinflation accounting since 3Q18. The IFRS rules (IAS 29) require us to restate the year-to-date results for the change in the general purchasing power of the local currency, using official indices before converting the local amounts at the closing rate of the period. In 3Q26, we reported a negative impact from hyperinflation accounting on the profit attributable to equity holders of AB InBev of 23 million USD. The impact in 3Q26 Basic EPS was 0.01 USD. Values in the figures and annexes may not add up due to rounding. 3Q26 and 9M26 EPS is based upon a weighted average of 1 973 million shares compared to a weighted average of 1 986 million shares for 3Q25 and 9M25.
Legal disclaimer
This release contains“forward-looking statements”. These statements are based on the current expectations and views of future events and developments of the management of AB InBev and are naturally subject to uncertainty and changes in circumstances. The forward-looking statements contained in this release include statements other than historical facts and include statements typically containing words such as“will”,“may”,“should”,“believe”,“intends”,“expects”,“anticipates”,“targets”,“ambition”,“estimates”,“likely”,“foresees” and words of similar import. All statements other than statements of historical facts are forward-looking statements. You should not place undue reliance on these forward-looking statements, which reflect the current views of the management of AB InBev, are subject to numerous risks and uncertainties about AB InBev and are dependent on many factors, some of which are outside of AB InBev's control. There are important factors, risks and uncertainties that could cause actual outcomes and results to be materially different, including, but not limited to the risks and uncertainties relating to AB InBev that are described under Item 3.D of AB InBev's Annual Report on Form 20-F filed with the SEC on 3 March 2026. Many of these risks and uncertainties are, and will be, exacerbated by any further worsening of the global business and economic environment, including as a result of foreign currency exchange rate fluctuations and ongoing geopolitical instability. Other unknown or unpredictable factors could cause actual results to differ materially from those in the forward-looking statements. The forward-looking statements should be read in conjunction with the other cautionary statements that are included elsewhere, including AB InBev's most recent Form 20-F and other reports furnished on Form 6-K, and any other documents that AB InBev has made public. Any forward-looking statements made in this communication are qualified in their entirety by these cautionary statements and there can be no assurance that the actual results or developments anticipated by AB InBev will be realized or, even if substantially realized, that they will have the expected consequences to, or effects on, AB InBev or its business or operations. Except as required by law, AB InBev undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, future events or otherwise. The nine month 2026 (9M26) financial data set out in Figure 1 (except for the volume information), Figures 3 to 6, 8, 10 and 12 of this press release have been extracted from the group's unaudited condensed consolidated interim financial statements as of and for the nine-month period ended 30 September 2026, which have been reviewed by our statutory auditors PwC Bedrijfsrevisoren BV/Réviseurs d'Entreprises SRL in accordance with the standards of the Public Company Accounting Oversight Board (United States). The third quarter 2026 (3Q26) financial data set out in Figure 1 (except for the volume information), Figures 3 to 6, 8, 10 and 12, and the financial data included in Figures 7, 9 and 11 of this press release have been extracted from the underlying accounting records as of and for the nine-month period ended 30 September 2026. References in this document to materials on our websites, such as , are included as an aid to their location and are not incorporated by reference into this document.
Conference call and webcast
Investor Conference call and webcast on Thursday, 29 October 2026:
2.00pm Brussels / 1.00pm London / 9.00am New York
Registration details:
Webcast (listen-only mode):
AB InBev 3Q26 Results Webcast
To join by phone, please use one of the following two phone numbers:
Toll-Free: +1-877-407-8029
Toll: +1-201-689-8029
About AB InBev
Anheuser-Busch InBev (AB InBev) is a publicly traded company (Euronext: ABI) based in Leuven, Belgium, with secondary listings on the Mexico (MEXBOL: ANB) and South Africa (JSE: ANH) stock exchanges and with American Depositary Receipts on the New York Stock Exchange (NYSE: BUD). As a company, we dream big to create a future with more cheers. We are always looking to serve up new ways to meet life's moments, move our industry forward and make a meaningful impact in the world. We are committed to building great brands that stand the test of time and to brewing the best beers using the finest ingredients. Beer is the drink for moderation, and for over a century, AB InBev has championed responsible drinking. We are committed to providing our consumers with Balanced Choices to enjoy on any occasion. We also invest in marketing that aims to reinforce positive behaviors, and we work with communities, customers, and partners to promote responsible consumption through evidence-based initiatives.
Our diverse portfolio of well over 400 beer brands includes global brands Budweiser®, Corona®, Stella Artois® and Michelob Ultra®; multi-country brands Beck's®, Hoegaarden® and Leffe®; and local champions such as Aguila®, Antarctica®, Bud Light®, Brahma®, Cass®, Castle®, Castle Lite®, Cristal®, Harbin®, Jupiler®, Modelo Especial®, Quilmes®, Victoria®, Sedrin®, and Skol®. Our brewing heritage dates back more than 600 years, spanning continents and generations. From our European roots at the Den Hoorn brewery in Leuven, Belgium. To the pioneering spirit of the Anheuser & Co brewery in St. Louis, US. To the creation of the Castle Brewery in South Africa during the Johannesburg gold rush. To Bohemia, the first brewery in Brazil. Geographically diversified with a balanced exposure to developed and developing markets, we leverage the collective strengths of approximately 137 000 colleagues based in more than 40 countries worldwide. For 2025, AB InBev's reported revenue was 59.3 billion USD (excluding JVs and associates).
Annex 1: Segment reporting (3Q)
| AB InBev Worldwide | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 142 319 | (518 | ) | - | 512 | 142 313 | 0.4 | % | ||||||||||
| Revenue | 15 133 | (19 | ) | 662 | 736 | 16 512 | 4.9 | % | ||||||||||
| Cost of sales | (6 596 | ) | (39 | ) | (284 | ) | (291 | ) | (7 210 | ) | (4.4 | )% | ||||||
| Gross profit | 8 537 | (58 | ) | 378 | 446 | 9 302 | 5.3 | % | ||||||||||
| SG&A | (4 535 | ) | (91 | ) | (167 | ) | (187 | ) | (4 979 | ) | (4.1 | )% | ||||||
| Other operating income/(expenses) | 203 | 23 | 6 | (17 | ) | 215 | (8.3 | )% | ||||||||||
| Normalized EBIT | 4 205 | (126 | ) | 217 | 242 | 4 538 | 6.0 | % | ||||||||||
| Normalized EBITDA | 5 594 | (125 | ) | 274 | 213 | 5 957 | 3.9 | % | ||||||||||
| Normalized EBITDA margin | 37.0 | % | 36.1 | % | (34)bps | |||||||||||||
| North America | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 21 896 | 165 | - | (541 | ) | 21 520 | (2.5 | )% | ||||||||||
| Revenue | 3 765 | 81 | (12 | ) | (33 | ) | 3 801 | (0.9 | )% | |||||||||
| Cost of sales | (1 500 | ) | (31 | ) | 4 | (12 | ) | (1 540 | ) | (0.8 | )% | |||||||
| Gross profit | 2 264 | 50 | (8 | ) | (45 | ) | 2 261 | (2.0 | )% | |||||||||
| SG&A | (1 121 | ) | (30 | ) | 5 | (3 | ) | (1 150 | ) | (0.3 | )% | |||||||
| Other operating income/(expenses) | 3 | 0 | 0 | 3 | 6 | - | ||||||||||||
| Normalized EBIT | 1 146 | 20 | (3 | ) | (45 | ) | 1 117 | (4.0 | )% | |||||||||
| Normalized EBITDA | 1 323 | 23 | (4 | ) | (46 | ) | 1 296 | (3.5 | )% | |||||||||
| Normalized EBITDA margin | 35.1 | % | 34.1 | % | (93)bps | |||||||||||||
| Middle Americas | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 36 915 | (596 | ) | - | 2 648 | 38 967 | 7.3 | % | ||||||||||
| Revenue | 4 325 | (64 | ) | 454 | 518 | 5 232 | 12.1 | % | ||||||||||
| Cost of sales | (1 527 | ) | (16 | ) | (151 | ) | (83 | ) | (1 777 | ) | (5.4 | )% | ||||||
| Gross profit | 2 797 | (80 | ) | 303 | 435 | 3 454 | 16.0 | % | ||||||||||
| SG&A | (960 | ) | (8 | ) | (98 | ) | (92 | ) | (1 158 | ) | (9.5 | )% | ||||||
| Other operating income/(expenses) | 1 | 0 | (1 | ) | 2 | 2 | - | |||||||||||
| Normalized EBIT | 1 838 | (88 | ) | 204 | 344 | 2 299 | 19.7 | % | ||||||||||
| Normalized EBITDA | 2 170 | (85 | ) | 234 | 325 | 2 644 | 15.6 | % | ||||||||||
| Normalized EBITDA margin | 50.2 | % | 50.5 | % | 151bps | |||||||||||||
| South America | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 36 922 | - | - | 291 | 37 213 | 0.8 | % | |||||||||||
| Revenue | 2 802 | 1 | 122 | 255 | 3 180 | 9.1 | % | |||||||||||
| Cost of sales | (1 413 | ) | (19 | ) | (83 | ) | (93 | ) | (1 608 | ) | (6.5 | )% | ||||||
| Gross profit | 1 389 | (18 | ) | 38 | 162 | 1 572 | 11.8 | % | ||||||||||
| SG&A | (841 | ) | (5 | ) | (49 | ) | (56 | ) | (951 | ) | (6.7 | )% | ||||||
| Other operating income/(expenses) | 100 | 26 | 6 | (0 | ) | 131 | (0.4 | )% | ||||||||||
| Normalized EBIT | 648 | 3 | (6 | ) | 106 | 751 | 16.6 | % | ||||||||||
| Normalized EBITDA | 881 | 13 | 11 | 121 | 1 025 | 13.8 | % | |||||||||||
| Normalized EBITDA margin | 31.5 | % | 32.3 | % | 135bps |
| EMEA | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 24 149 | (67 | ) | - | 598 | 24 680 | 2.5 | % | ||||||||||
| Revenue | 2 524 | (41 | ) | 78 | 100 | 2 660 | 4.0 | % | ||||||||||
| Cost of sales | (1 244 | ) | 27 | (43 | ) | (69 | ) | (1 329 | ) | (5.7 | )% | |||||||
| Gross profit | 1 280 | (15 | ) | 35 | 31 | 1 331 | 2.4 | % | ||||||||||
| SG&A | (760 | ) | 2 | (15 | ) | (36 | ) | (809 | ) | (4.8 | )% | |||||||
| Other operating income/(expenses) | 59 | (3 | ) | (0 | ) | (6 | ) | 50 | (10.2 | )% | ||||||||
| Normalized EBIT | 579 | (15 | ) | 20 | (11 | ) | 572 | (2.0 | )% | |||||||||
| Normalized EBITDA | 859 | (11 | ) | 29 | (12 | ) | 866 | (1.4 | )% | |||||||||
| Normalized EBITDA margin | 34.0 | % | 32.5 | % | (177)bps | |||||||||||||
| Asia Pacific | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 22 301 | (25 | ) | - | (2 454 | ) | 19 821 | (11.0 | )% | |||||||||
| Revenue | 1 533 | 4 | 21 | (145 | ) | 1 412 | (9.5 | )% | ||||||||||
| Cost of sales | (718 | ) | 1 | (11 | ) | 31 | (697 | ) | 4.3 | % | ||||||||
| Gross profit | 814 | 5 | 10 | (114 | ) | 715 | (14.0 | )% | ||||||||||
| SG&A | (546 | ) | (28 | ) | (7 | ) | 37 | (544 | ) | 6.8 | % | |||||||
| Other operating income/(expenses) | 32 | (0 | ) | 1 | (13 | ) | 21 | (39.5 | )% | |||||||||
| Normalized EBIT | 300 | (24 | ) | 4 | (89 | ) | 192 | (29.8 | )% | |||||||||
| Normalized EBITDA | 452 | (20 | ) | 9 | (102 | ) | 339 | (22.4 | )% | |||||||||
| Normalized EBITDA margin | 29.5 | % | 24.0 | % | (426)bps | |||||||||||||
| Global Export and Holding Companies | 3Q25 | Scope |
Currency Translation |
Organic Growth |
3Q26 |
Organic Growth | ||||||||||||
| Volumes | 136 | 6 | - | (29 | ) | 112 | (20.8 | )% | ||||||||||
| Revenue | 185 | 1 | (0 | ) | 42 | 227 | 22.3 | % | ||||||||||
| Cost of sales | (194 | ) | (1 | ) | (0 | ) | (65 | ) | (259 | ) | (33.4 | )% | ||||||
| Gross profit | (8 | ) | 0 | (1 | ) | (23 | ) | (32 | ) | (295.2 | )% | |||||||
| SG&A | (307 | ) | (22 | ) | (2 | ) | (36 | ) | (367 | ) | (10.9 | )% | ||||||
| Other operating income/(expenses) | 8 | (0 | ) | (1 | ) | (2 | ) | 5 | (29.3 | )% | ||||||||
| Normalized EBIT | (306 | ) | (22 | ) | (3 | ) | (62 | ) | (393 | ) | (18.8 | )% | ||||||
| Normalized EBITDA | (91 | ) | (45 | ) | (5 | ) | (73 | ) | (214 | ) | (54.0 | )% |
Annex 2: Segment reporting (9M)
| AB InBev Worldwide | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 421 934 | (2 006 | ) | - | 2 798 | 422 726 | 0.7 | % | ||||||||||
| Revenue | 43 764 | (125 | ) | 2 445 | 2 355 | 48 439 | 5.4 | % | ||||||||||
| Cost of sales | (19 198 | ) | 32 | (1 010 | ) | (737 | ) | (20 912 | ) | (3.9 | )% | |||||||
| Gross profit | 24 566 | (92 | ) | 1 435 | 1 618 | 27 528 | 6.6 | % | ||||||||||
| SG&A | (13 347 | ) | (139 | ) | (653 | ) | (758 | ) | (14 897 | ) | (5.7 | )% | ||||||
| Other operating income/(expenses) | 585 | 13 | 38 | (52 | ) | 584 | (9.2 | )% | ||||||||||
| Normalized EBIT | 11 805 | (218 | ) | 820 | 808 | 13 215 | 7.0 | % | ||||||||||
| Normalized EBITDA | 15 750 | (228 | ) | 1 040 | 770 | 17 332 | 5.0 | % | ||||||||||
| Normalized EBITDA margin | 36.0 | % | 35.8 | % | (15)bps | |||||||||||||
| North America | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 64 115 | 286 | - | (1 320 | ) | 63 081 | (2.1 | )% | ||||||||||
| Revenue | 10 973 | 140 | 15 | 98 | 11 225 | 0.9 | % | |||||||||||
| Cost of sales | (4 447 | ) | (38 | ) | (5 | ) | 18 | (4 472 | ) | 0.4 | % | |||||||
| Gross profit | 6 525 | 103 | 10 | 116 | 6 753 | 1.8 | % | |||||||||||
| SG&A | (3 295 | ) | (65 | ) | (6 | ) | (111 | ) | (3 478 | ) | (3.4 | )% | ||||||
| Other operating income/(expenses) | 26 | 0 | (0 | ) | (2 | ) | 24 | (6.3 | )% | |||||||||
| Normalized EBIT | 3 256 | 37 | 3 | 3 | 3 300 | 0.1 | % | |||||||||||
| Normalized EBITDA | 3 781 | 48 | 4 | (33 | ) | 3 801 | (0.9 | )% | ||||||||||
| Normalized EBITDA margin | 34.5 | % | 33.9 | % | (60)bps | |||||||||||||
| . | ||||||||||||||||||
| Middle Americas | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 110 818 | (1 958 | ) | - | 6 087 | 114 946 | 5.6 | % | ||||||||||
| Revenue | 12 449 | (219 | ) | 1 312 | 1 286 | 14 827 | 10.5 | % | ||||||||||
| Cost of sales | (4 393 | ) | 67 | (434 | ) | (276 | ) | (5 036 | ) | (6.4 | )% | |||||||
| Gross profit | 8 055 | (152 | ) | 878 | 1 010 | 9 791 | 12.8 | % | ||||||||||
| SG&A | (2 858 | ) | 18 | (299 | ) | (260 | ) | (3 399 | ) | (9.1 | )% | |||||||
| Other operating income/(expenses) | 15 | 1 | (1 | ) | (20 | ) | (5 | ) | - | |||||||||
| Normalized EBIT | 5 212 | (134 | ) | 578 | 731 | 6 387 | 14.4 | % | ||||||||||
| Normalized EBITDA | 6 177 | (129 | ) | 669 | 694 | 7 411 | 11.5 | % | ||||||||||
| Normalized EBITDA margin | 49.6 | % | 50.0 | % | 43bps | |||||||||||||
| . | ||||||||||||||||||
| South America | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 112 011 | - | - | 632 | 112 643 | 0.6 | % | |||||||||||
| Revenue | 8 309 | 10 | 549 | 713 | 9 581 | 8.6 | % | |||||||||||
| Cost of sales | (4 176 | ) | (36 | ) | (281 | ) | (233 | ) | (4 727 | ) | (5.6 | )% | ||||||
| Gross profit | 4 132 | (27 | ) | 268 | 480 | 4 854 | 11.6 | % | ||||||||||
| SG&A | (2 553 | ) | (13 | ) | (163 | ) | (190 | ) | (2 920 | ) | (7.4 | )% | ||||||
| Other operating income/(expenses) | 302 | 24 | 32 | 28 | 386 | 9.9 | % | |||||||||||
| Normalized EBIT | 1 881 | (15 | ) | 136 | 318 | 2 320 | 17.2 | % | ||||||||||
| Normalized EBITDA | 2 580 | 3 | 185 | 333 | 3 101 | 13.0 | % | |||||||||||
| Normalized EBITDA margin | 31.1 | % | 32.4 | % | 125bps |
| EMEA | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 69 073 | (297 | ) | - | 1 074 | 69 850 | 1.6 | % | ||||||||||
| Revenue | 6 978 | (110 | ) | 475 | 268 | 7 611 | 3.9 | % | ||||||||||
| Cost of sales | (3 523 | ) | 64 | (245 | ) | (98 | ) | (3 802 | ) | (2.8 | )% | |||||||
| Gross profit | 3 454 | (46 | ) | 230 | 170 | 3 809 | 5.0 | % | ||||||||||
| SG&A | (2 131 | ) | (9 | ) | (136 | ) | (114 | ) | (2 389 | ) | (5.3 | )% | ||||||
| Other operating income/(expenses) | 159 | (11 | ) | 4 | (29 | ) | 123 | (19.5 | )% | |||||||||
| Normalized EBIT | 1 483 | (66 | ) | 99 | 27 | 1 543 | 1.9 | % | ||||||||||
| Normalized EBITDA | 2 283 | (52 | ) | 156 | 25 | 2 412 | 1.1 | % | ||||||||||
| Normalized EBITDA margin | 32.7 | % | 31.7 | % | (87)bps | |||||||||||||
| Asia Pacific | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 65 665 | (64 | ) | - | (3 646 | ) | 61 955 | (5.6 | )% | |||||||||
| Revenue | 4 641 | 13 | 91 | (211 | ) | 4 534 | (4.6 | )% | ||||||||||
| Cost of sales | (2 174 | ) | 3 | (38 | ) | 72 | (2 138 | ) | 3.3 | % | ||||||||
| Gross profit | 2 466 | 16 | 53 | (139 | ) | 2 397 | (5.6 | )% | ||||||||||
| SG&A | (1 487 | ) | (40 | ) | (27 | ) | (5 | ) | (1 559 | ) | (0.3 | )% | ||||||
| Other operating income/(expenses) | 73 | (1 | ) | 3 | (27 | ) | 48 | (37.4 | )% | |||||||||
| Normalized EBIT | 1 053 | (25 | ) | 28 | (171 | ) | 885 | (16.3 | )% | |||||||||
| Normalized EBITDA | 1 508 | (13 | ) | 43 | (209 | ) | 1 329 | (13.8 | )% | |||||||||
| Normalized EBITDA margin | 32.5 | % | 29.3 | % | (316)bps | |||||||||||||
| . | ||||||||||||||||||
| Global Export and Holding Companies | 9M25 | Scope |
Currency Translation |
Organic Growth |
9M26 |
Organic Growth | ||||||||||||
| Volumes | 252 | 28 | - | (28 | ) | 251 | (10.1 | )% | ||||||||||
| Revenue | 416 | 41 | 3 | 200 | 660 | 47.7 | % | |||||||||||
| Cost of sales | (484 | ) | (28 | ) | (6 | ) | (219 | ) | (737 | ) | (45.2 | )% | ||||||
| Gross profit | (68 | ) | 14 | (3 | ) | (19 | ) | (76 | ) | (28.7 | )% | |||||||
| SG&A | (1 023 | ) | (29 | ) | (22 | ) | (77 | ) | (1 151 | ) | (7.4 | )% | ||||||
| Other operating income/(expenses) | 11 | - | 1 | (3 | ) | 8 | (27.1 | )% | ||||||||||
| Normalized EBIT | (1 079 | ) | (15 | ) | (25 | ) | (99 | ) | (1 219 | ) | (9.0 | )% | ||||||
| Normalized EBITDA | (580 | ) | (85 | ) | (16 | ) | (41 | ) | (722 | ) | (6.2 | )% |
View source version on businesswire:
Permalink
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment