


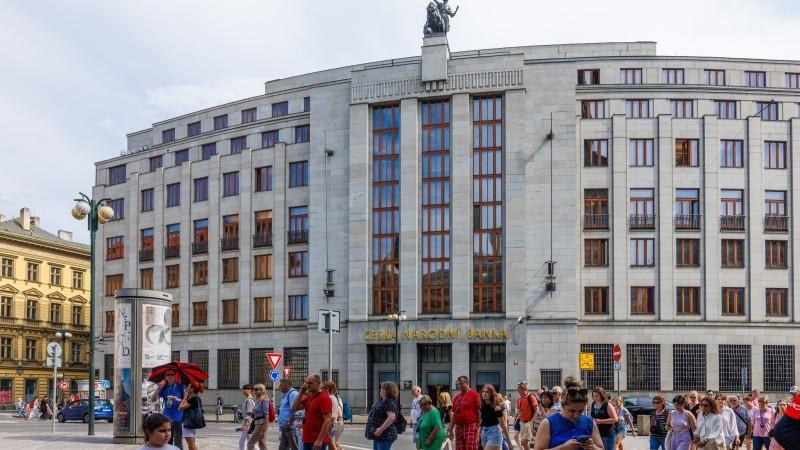
Czech National Bank Preview: Another Hike, More On The Horizon


| 4.00% | CNB key rate 25bp rate hike expected |
The CNB's new forecast is expected to feature a series of hawkish upgrades. Headline and core inflation have run slightly above the forecast in recent months, which marginally raises the starting point. External assumptions are also likely to undergo a significant hawkish revision. In the new forecast, eurozone CPI and PPI are expected to be significantly higher, while the EURIBOR projection-based on forward rates-has shifted upward by roughly 80bp on average across the entire horizon of the CNB's forecast compared to the August outlook. Based on current forward prices, the CNB's forecast for oil prices will have to be raised by 21% for next year and by 11% for 2028 relative to the August forecast. The outlook for gas prices is even more pronounced, with an upward revision of 80% for next year and 60% for 2028. Furthermore, the CNB must incorporate the government's draft budget for next year, which anticipates a 6.8% average increase in public sector wages and an 11.2% hike in the minimum wage.
Collectively, these factors should lead to a notable revision of the inflation outlook for next year; in the August version, the CNB had projected an average of 2.8% for the first quarter of 2027, with a subsequent slowdown. At the same time, faster wage growth and robust consumption are expected to push core inflation higher than previously anticipated. This should also be reflected in a higher interest rate path-noting that the current outlook does not factor in any further rate hikes. The only 'dovish' signal in the new forecast is likely the lower GDP growth, which, for 2Q26, came in 0.4 percentage points below the CNB's previous expectations. Nevertheless, the overall tone of the forecast is expected to be 'hawkish,' pointing toward further rate hikes in the future.
Higher energy prices work their way through the price chain Source: Macrobond, ING"> We remain more hawkish on inflation than the CNB and the rest of the marketAll the aforementioned adjustments to the CNB's forecast align with our own projections. We expect GDP growth of 1.8% this year and 2.3% next year, well below the CNB's figures of 2.2% and 2.7%, respectively. At the same time, we anticipate inflation to average 3.9% in the first quarter of 2027 and 3.4% for the entirety of next year, well above the CNB and rest of the market estimates. This is driven primarily by a turnaround in food prices, which had previously helped keep headline inflation in check, as well as higher energy costs, which will feed into the CPI via regulated prices, particularly in January during the annual price adjustments.
Overall, we expect a rate hike at the November meeting, and we remain open to incorporating further hikes into our forecast, depending on the CNB's communication next week. In any case, we believe that, following the November meeting, the December and, most notably, the February meetings remain 'live' for further tightening, contingent upon incoming inflation data, especially the January print.
Our market viewsAlthough we have been bearish on CEE currencies since the beginning of September, the koruna stands out as an outlier. It should remain supported by the central bank's hawkish stance and we remain bullish. The CNB is the only central bank in the CEE region that has already responded to the onset of the US-Iran conflict with rate hikes, and according to our forecast, it will continue to do so in the coming months. The market is pricing in more than 100bp of rate hikes, and we do not expect this to change, given the continued rise in energy prices on global markets. This should continue to provide a sufficient buffer for the CZK, shielding it from the global pressures currently weighing on its CEE peers. Furthermore, the Czech Republic stands out within the region in terms of fiscal indicators, which should help insulate it from spillovers originating in the eurozone bond market. On the other hand, following the CZK rally in October, we believe that EUR/CZK is currently fairly priced in the 24.300–24.350 range, barring any significant surprise from the CNB relative to our already hawkish expectations. We maintain our view that the CZK should outperform its CEE peers, unless there is a substantial easing of global risk premiums supporting the region.
A rate hike by the CNB in November is almost fully priced in, and the market is anticipating another hike at the February meeting, with a terminal rate of 5.00% expected over a horizon of roughly a year and a half. Even relative to our own hawkish forecast, this is significantly higher than expected. This sets the bar for a hawkish surprise very high; in fact, CNB meetings this year have typically resulted in a dovish adjustment to market pricing. Global energy prices remain the primary driver for local rates pricing, with the CNB exerting only limited influence; consequently, we do not anticipate a significant impact on that front. For the time being, the yield curve is more likely to steepen from current levels before shifting toward a flattening phase early next year, coinciding with an expected jump in inflation. Furthermore, we believe the CZK market should price in the most aggressive rate hikes within the region, and that the spread against the PLN is set to widen further, reflecting a distinct reaction function.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment