


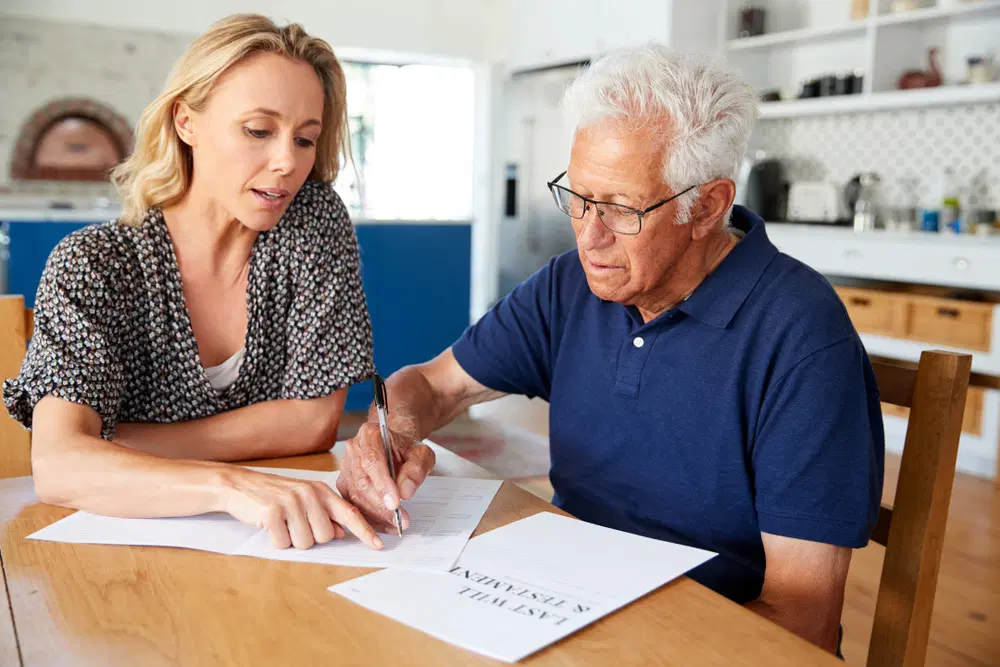
Why You Should Never Put Your Adult Children's Names On Your House Deed (And What To Do Instead)


Unfortunately, that seemingly harmless decision can create financial and legal problems while you're still alive.
Depending on how the deed is structured, transferring ownership to a child could expose part of your property to creditors, complicate a future sale, create unexpected tax consequences, or interfere with long-term care planning.
Before adding children to a house deed, homeowners should understand seven potential consequences and the estate-planning alternatives that may accomplish the same goals with fewer risks.
1. Your Child's Financial Problems Could Put Your Home at RiskWhen you add an adult child to your deed as a co-owner, you're giving them a legal ownership interest in your property. Depending on state law and the type of ownership, that interest could become vulnerable if your child faces a lawsuit, bankruptcy, judgment, or divorce. Imagine adding your son to your $400,000 home, only to discover several years later that his creditors are pursuing assets he legally owns. Although creditors don't automatically gain control of your entire house, claims against your child's ownership interest could create serious complications. Before transferring property, ask an estate-planning attorney how your state's laws protect or expose jointly owned real estate.
2. You Could Leave Your Children With a Bigger Capital Gains Tax BillOne of the most expensive mistakes homeowners can make involves overlooking the difference between gifting property during their lifetime and leaving it through an inheritance. According to the Internal Revenue Service, inherited property generally receives a tax basis equal to its fair market value at the owner's death, while property received as a lifetime gift generally carries over the original owner's adjusted basis for calculating gains. Imagine purchasing your home for $150,000 and watching its value climb to $450,000, creating $300,000 in appreciation before accounting for improvements and other adjustments. If your child inherits the entire property with a $450,000 basis and sells it shortly afterward for that amount, there may be little or no taxable capital gain, whereas receiving the entire property as a lifetime gift could produce a much larger taxable gain upon sale. Adding a child to a deed doesn't automatically eliminate the basis adjustment for the entire house, because the outcome depends on ownership structure, estate inclusion, and other tax rules, making professional advice especially important.
3. You May Lose the Freedom to Sell or Refinance Your HomeHomeownership provides financial flexibility, particularly for retirees who may eventually need to downsize, relocate, or access accumulated equity. However, adding an adult child as a co-owner can make certain decisions more complicated because selling or refinancing the entire property will generally require cooperation from everyone with an ownership interest. Imagine wanting to sell your house and move closer to family, only to discover that your daughter disagrees with the sale or cannot be reached to sign the necessary paperwork. A child's divorce, bankruptcy, incapacity, or death could introduce additional parties and legal complications, depending on how the property is titled. Maintaining sole ownership during your lifetime may preserve more flexibility if your retirement plans or financial circumstances change.
4. Adding Your Child Could Trigger Gift Tax Reporting RequirementsTransferring part of your home's ownership to an adult child without receiving fair market value may constitute a taxable gift for federal reporting purposes. The IRS confirms that the annual gift tax exclusion is $19,000 per recipient in 2026, meaning a transfer exceeding that amount may require filing Form 709. For example, giving your child a 50% interest in a $400,000 home could represent a substantial gift, depending on the property's valuation and any liabilities involved. Fortunately, filing a gift tax return doesn't automatically mean you'll owe gift taxes, because larger gifts may be covered by the lifetime federal gift and estate tax exclusion, which is $15 million per person in 2026. Nevertheless, homeowners should understand the reporting requirements and potential state-level consequences before changing their deeds.
5. You Could Create an Inheritance Dispute Between SiblingsAdding one adult child to a deed can unintentionally create conflict when multiple children expect to inherit the family home. Suppose you have three children but add only your oldest daughter's name because she lives nearby and helps manage household responsibilities. Depending on the deed's ownership provisions, she could eventually receive a larger ownership interest than her siblings or become the surviving owner of the entire property. Your will may not override a valid survivorship arrangement, meaning your intended inheritance plan could produce a different result from what you expected. Discussing your estate-planning goals with your family and documenting them through appropriate legal instruments can help prevent misunderstandings that become expensive disputes later.
6. You Could Complicate Medicaid Long-Term Care EligibilityLong-term care expenses are another important consideration for homeowners who want to transfer property to their children. According to Medicaid, transferring assets for less than fair market value during the five years before applying for certain Medicaid long-term services and supports can trigger a period of ineligibility. Adding an adult child to your house deed may count as such a transfer, although exceptions can apply, including certain transfers involving a spouse, a disabled child, or an adult child who provided qualifying care. For someone who eventually needs nursing home care, an improperly planned transfer could create a serious financial problem when assistance is needed most. Because Medicaid rules, exemptions, home ownership protections, and estate recovery requirements are complicated, homeowners should consult an elder-law attorney before transferring property as part of a long-term care strategy.
7. Your Property Taxes and Insurance Could Become More ComplicatedChanging ownership can have consequences beyond federal taxes and inheritance planning. Some states and local governments provide property tax exemptions, assessment limits, or other benefits based on an owner's age, disability status, residency, or ownership arrangement. Adding another person to a deed could affect eligibility for certain benefits or trigger reassessment under applicable local rules, although parent-child transfers may qualify for exemptions in some jurisdictions. Homeowners should also notify their insurance company before changing ownership because the policy needs to accurately reflect the property's owners and their insurable interests. A conversation with your county assessor and insurance agent before signing a deed could help prevent unexpected expenses or coverage complications.
What Should You Do Instead of Adding Your Child to the Deed?A revocable living trust may allow homeowners to retain control of their property during their lifetime while establishing instructions for transferring it after death. Another option is a transfer-on-death deed, which is recognized in many states and can allow real estate to pass to a named beneficiary without making that person a current co-owner. These arrangements may help avoid probate, but they aren't interchangeable, and their effectiveness depends on state law, proper execution, and the homeowner's circumstances. A properly structured estate plan may also preserve favorable tax treatment, although neither a trust nor a transfer-on-death deed automatically eliminates creditor claims, Medicaid issues, or every other financial risk. An estate-planning attorney can help determine whether a trust, beneficiary deed, will, or another arrangement offers the best balance of control, cost, and protection.
The Cost of Planning Is Often Smaller Than the Cost of Fixing a MistakeHomeowners sometimes avoid professional estate planning because they assume adding a child's name to a deed is cheaper and easier. However, the potential costs of correcting an ownership mistake can include attorney fees, title complications, tax preparation expenses, and disputes between family members. A homeowner who transfers property without understanding the consequences might later need additional legal documents, cooperation from the child, or even court involvement to resolve the situation. Before making changes, compare the cost of establishing an appropriate estate plan with the financial risks of transferring ownership prematurely. Spending money on sound legal advice today may help protect a home that represents hundreds of thousands of dollars in retirement wealth.
Protect Your Home Without Giving Up Control Too SoonAdding children to a house deed may seem like a loving gesture, but it can create financial consequences that extend far beyond simplifying an inheritance. From potential creditor claims and capital gains taxes to Medicaid eligibility and family disputes, the risks deserve careful consideration before any paperwork is signed. Fortunately, estate-planning tools such as revocable living trusts and transfer-on-death deeds may provide alternatives that preserve more control during your lifetime. The right choice depends on your state's laws, your financial situation, your family relationships, and what you ultimately want to happen to your property. Your home may be your most valuable retirement asset, so protecting it should involve more than adding another name to a legal document.
Have you considered adding an adult child to your house deed, or have you seen this decision create unexpected problems for a family? Share your experience in the comments.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment