


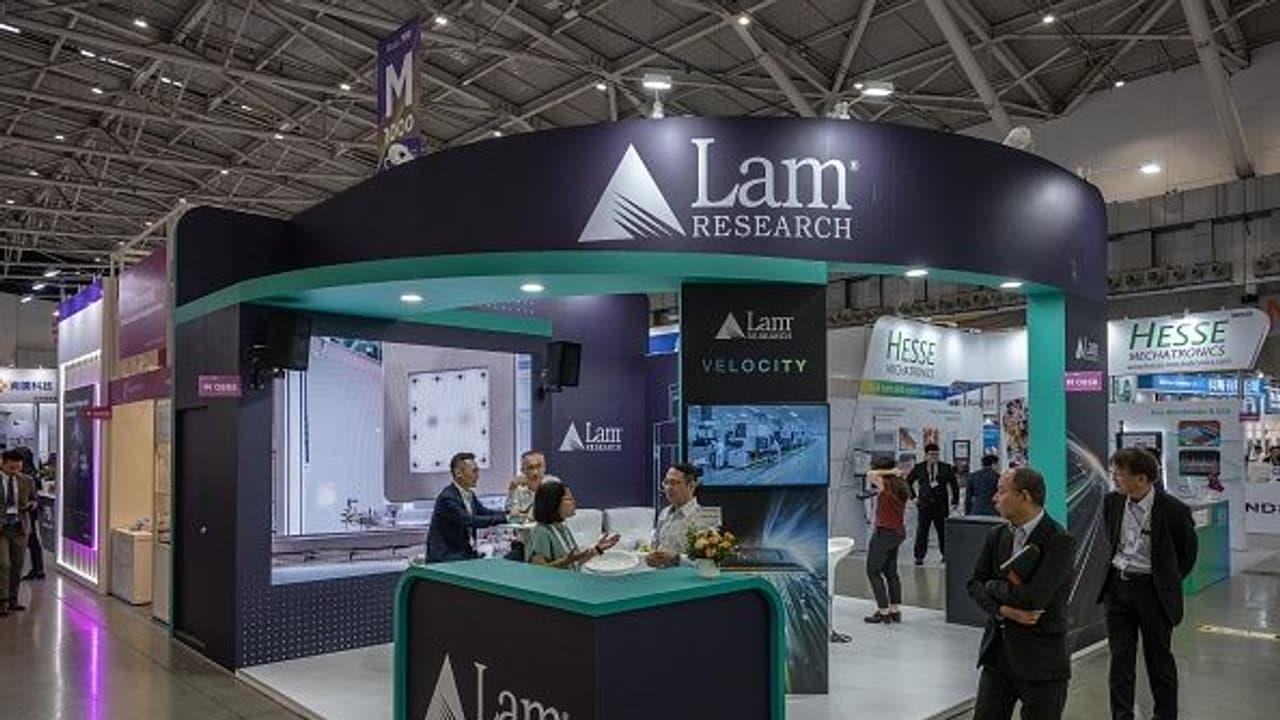
LRCX Stock Sinks As Analysts Trim Targets, See Supply Constraints But Longer-Term Bull Case Remains


Firm | Rating | Previous Target | New Target | Change Vs. Last Close |
Citi | Buy | $450 | $435 | +66.8% |
Mizuho | Outperform | $365 | $360 | +38.0% |
BofA | Buy | $385 | $345 | +32.3% |
Morgan Stanley | Overweight | $385 | $339 | +30.0% |
Needham | Buy | $390 | $290 | +11.2% |
What Lam's Latest Earnings Revealed
Lam's fiscal first-quarter revenue surged 22% sequentially to a record $8.22 billion, beating FiscalAI's consensus estimate of $8.14 billion. Adjusted EPS came in at $2.20, topping expectations of $2.18.
The company reported a non-GAAP gross margin of 52.4% and an operating margin of 40.2%. Management expects the global wafer fabrication equipment market to exceed $200 billion in calendar 2027, compared with an estimated mid-$150 billion range in 2026.
What Retail Thinks of LRCX Stock
On Stocktwits, retail investors' sentiment around LRCX stock remained in 'extremely bullish' territory amid extremely high message volume.
So far this year, LRCX stock has rallied nearly 41%. By comparison, the VanEck Semiconductor ETF (SMH) and the State Street Technology Select Sector SPDR ETF (XLK), which hold the stock, have rallied around 49% and 31%, respectively, over this period.
See Also: Meta's Muse AI Momentum Wins Over Analysts - But $140B Spending Outlook Raises Funding Questions
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment