


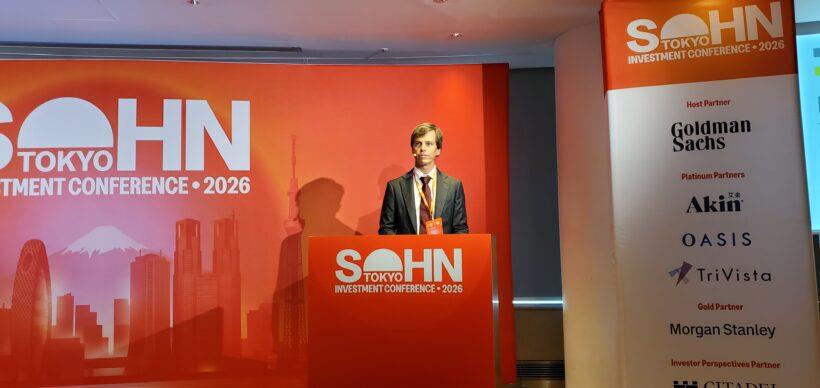
Pertento Partners' Eduardo Marques: Long This Korean Defense Holding Company And Short This Battery Materials Holdco


Table of Contents
Toggle- The chaebol discount, and why it is so random Howitzers inside a holdco The BYD of land defense The father, the son and the law A commodity business dressed as a tech company Leverage on questionable profits Heads for Hanwha, tails for Ecopro Why the gap exists Mind the gap
Marques is as comfortable on the short side as the long. He started out in 2004 as an analyst at 3G Capital in New York, then spent 13 years at Valiant Capital Management in San Francisco, where as a Managing Partner he ran the firm's single stock short book. In February 2021 he set up Pertento Partners, where he works with a team of five research analysts and around $5 billion AUM according to SEC filings.
The chaebol discount, and why it is so randomMarques shifted the attention from Japan to a market that is earlier in its governance reforms, and added a warning to the usual disclaimers: Korean stocks are not for the faint of heart, so investors might want to consult a physician alongside their financial advisor.
The reasons Korean chaebol holding companies trade at a deep discount to the sum of their parts are well known, he said. Minority shareholders rarely see cash, corporate actions tend to dilute them, they have no seat on the board, and activists struggle to force change. The government's Value-Up program is meant to tackle this, but the discounts remain large and, in Marques's view, close to random. His chart of thirteen Korean-listed holding companies showed twelve averaging 0.50 times NAV, with one at 0.36 times and one far out on its own at 1.77 times.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment