


US Midterm Elections: 3 Scenarios For Markets


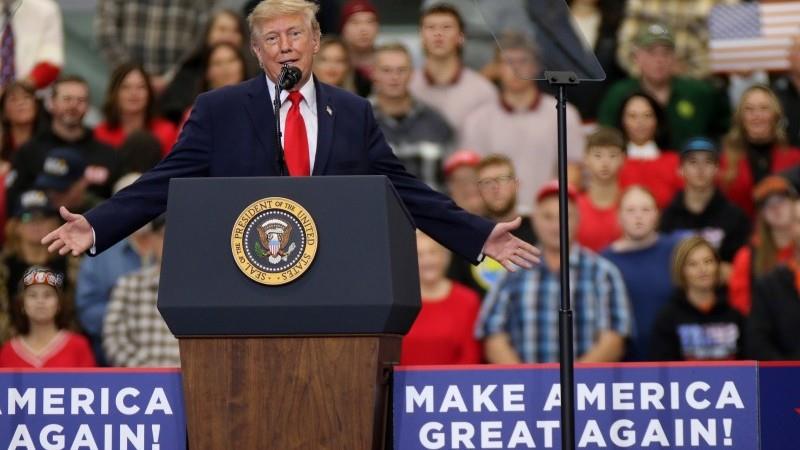
The US midterm elections are on 3 November, with all 435 House of Representatives seats and 35 of the 100 Senate seats up for election. Worries about the cost of living and the impact of AI on job security are regularly cited as key factors driving sentiment, while support for the conflict with Iran has wavered. Opinion polls currently suggest the Democrats lead by around eight percentage points nationally, and President Donald Trump's own approval rating has hit new lows, leading to Republican Party concerns about a demotivated electoral base.
Pollsters and prediction markets anticipate a Democrat takeover of Congress, but surprises do happen in US politics. While the midterms rarely lead to radical changes in policy direction, the result could significantly constrain President Trump, putting more focus on foreign and trade policy. We look at what the possible outcomes could mean.
Midterm election scenarios Source: ING"> Scenario 1: A Republican revivalRepublicans retain control of both the House and the Senate
This is seemingly the least likely outcome at the current juncture, given the state of the opinion polls. Nonetheless, if it happens, President Trump will see it as justification for his America First strategy. With re-election no longer a consideration, Trump's final two years are likely to focus on his legacy, entrenching what he views as his defining achievements.
We are looking at a further strengthening of border enforcement with expanded deportations. Tariff policy is likely to be increasingly focused on incentivising foreign partners to align with US international policy, together with more defence spending demanded of NATO members. Trump will also feel emboldened to push hard economically and militarily against Iran with demands that other countries contribute to those efforts. Deregulation is likely to be a theme, while fast-tracking AI/technology innovation and incentivising manufacturing and energy production (both fossil and nuclear) will be the main policies aimed at boosting economic growth.
Fiscal worries are likely to intensify, though. While few expect the president to follow through with his promise of $5,000 checks for returning Republicans to Congress, more defence spending will not be fully offset by efficiency savings or lower healthcare expenditure. Fiscal sustainability fears will intensify. At the same time, an escalation of military action in the Middle East could prompt significant energy market disruption, resulting in higher prices. Should the president force through“Trump dividend” payments, the Federal Reserve will come under even more market pressure to respond with higher interest rates, raising fears of a boom-bust cycle.
The market response to this outcome would be upward pressure on bond yields right along the curve. The front end reflects an intensification in the rate hike risk. The back end is spooked by the prospect of a further widening in the fiscal deficit and reactive tightening by the Fed. The 10yr yield likely pops above 5.5% and stays above, while the 2yr yield rises too and holds at around 5%. There is a contrarian possibility here that an emboldened Republican Party decides to act on the fiscal deficit, ultimately helping drive bond yields back down. But it's more likely that such an action would require a bad pain trade first for Treasuries to trigger such action.
Cyclically, this would be the most positive for the dollar on the back of the looser fiscal, tighter monetary policy outcome. Higher bond yields would continue to pressure-test the global financial system, with emerging market currencies and perhaps the euro too, via French government bonds, coming under further pressure.
Scenario 2: Trump constrainedDemocrats win control of the House, Republicans retain the Senate
The House, where officials serve two-year terms, is currently split between 219 Republicans and 214 Democrats, with 2 seats vacant. Pollsters and prediction markets appear confident the Democrats will win here with relative ease. The Senate, currently split between 53 Republicans and 45 Democrats with 2 independents who vote with the Democrats, is a much closer call. The Democrats need to flip 4 of the 22 Republican seats and hold on to all 13 of their seats that are up for election to gain control of the Senate.
Even if the Democrats fail to win the Senate, they will stifle President Trump's legislative agenda over his final two years in power. Spending and tax proposals will be gridlocked while many Democrats will use the House victory to justify stalling data centre construction in their constituencies. There will be more scrutiny of technology companies and AI development, with hearings before Congress being demanded. Fossil fuel producers may face similar challenges.
A key question is whether a constrained President Trump, entering the final phase of his tenure, becomes more willing to accept political or market disruption in pursuit of his objectives. Given the gridlock in Congress, the president will only be able to implement policy where he can use Executive Powers: 1) Foreign policy and diplomacy, including trade policy, 2) national security and defence, 3) law enforcement and regulatory policy, 4) appointments of personnel, and 5) administration and management policy. This suggests Iran and tariffs/trade policy are likely to be the focus for the president, but the Democrats could use Congressional power to try and restrain his actions.
Fiscal dynamics will remain a concern, although hitting the debt ceiling could act as a temporary brake. It will likely be an issue by mid-summer 2027 with little ground for compromise between the two sides in Congress. This risks an extended government shutdown, potentially exceeding last October's shutdown, which depressed GDP growth in 4Q 2025 by a full percentage point. The Federal Reserve risks“flying blind” again with no government economic statistics being collated or released.
It is the House where impeachment proceedings are started and a new round of action is possible. To be impeached, 67 of 100 Senators must vote in favour, which is likely not going to happen given there won't be enough Democrats (and supportive Republicans) to force it through. Nonetheless, the Democrats could use it as a way to constrain the president, but it risks toxifying the political situation in the US. Rather than the president facing such action, it has been mooted that the Democrats could launch investigations into members of his cabinet.
This outcome is broadly in line with the central market discount. The Democrats have one foot in the door, but remain broadly powerless to make meaningful change. Policy stasis leaves the bond market to balance the trade-off between a still elevated fiscal deficit and perhaps some taming of inflation concerns. We will probably see front-end yields easing lower while back-end yields maintain an upside bias, albeit within our preferred 5.25% to 5.5% range.
The dollar broadly prices in this scenario and a split Congress probably will not be significant enough to drag attention away from elevated inflation and a Fed intent on delivering at least one more rate hike. A prolonged government shutdown could start to weigh on the dollar in the second half of 2027, however.
Scenario 3: Democrat clean sweepDemocrats win control of both the House and the Senate
Given the polling and President Trump's poor personal approval ratings, this is the most likely outcome priced in prediction markets, although political analysts remain on the fence between this and scenario 2.
The implications are similar to scenario 2, but Democrats would likely feel even more confident about pushing back against President Trump's policies on Iran, support of Israel and any escalation of tariffs. They will be applying pressure on the president to sound tougher towards Russia and to provide support to Ukraine. Domestically, Democrats in Congress will try and pass legislation that improves healthcare access in return for some acquiescence surrounding the president's demands for higher defence spending – a government shutdown could reflect badly on the Democrats if they have control of both the House and the Senate. Fiscal concerns will persist.
A very strong showing for the Democrats that leads to a sizeable majority would heighten the chances of a third impeachment of President Trump, although it would need a sweeping victory to offer any chance of a conviction.
More fundamentally, a heavy defeat in the House and Senate could prompt figures within the Republican Party to take the view that it is time to open the debate on its future direction. With President Trump's influence set to fade, leading lights within the party, most notably JD Vance and Marco Rubio, may attempt to shore up support for their own campaigns as they look to the 2028 presidential election. Similarly, a large Democrat victory will intensify speculation over whether the party's candidate should be a traditionalist or whether the Left have the momentum to provide the 2028 candidate.
This outcome is not dramatically different from the previous scenario. Here, the Democrats have a mandate to secure some change, but will remain constrained by an obstructive executive branch. Front-end yields come under upside pressure. Back-end yields possibly see a silver lining from more tariffs acting as a tax hike, but at the same time pressured by inflation. The 10yr risks getting towards 5.5%, but without breaking above.
The dollar could see a little weakness here as an emboldened Democratic Party takes greater issue with Republican policy, including deregulation and the AI build-out.
What it means for Europe and ChinaShould Republicans pull off a huge surprise and retain control of Congress, political pressure on Europe will increase. The risk of a forced deal between Russia and Ukraine, to the disadvantage of Ukraine and Europe, increases and could undermine economic sentiment in Europe. A new escalation in the Middle East would push up energy prices and harm the European economy. Europe's latest shift towards more protectionist trade policies could bring new global trade tensions.
Should there be a split Congress with the Democrats controlling the House, and Trump does indeed focus on foreign and trade policy, volatility and uncertainty in the global economy could increase. This will clearly affect Europe. At the same time, with only two years left in office, the TACO (Trump Always Chickens Out) phenomenon could be an increasing part of Europe's considerations. The risk of an unwarranted economic accident increases as Trump's policies become more aggressive vis-à-vis Europe and Europe's own stance hardens (hoping for TACO and an end to Trump's term in office).
If there is a Democrat clean sweep, the sense that Trump's time is coming to an end could be all the greater and, under this scenario, some European countries could choose to slow the pace of defence spending increases given domestic fiscal considerations.
Regardless of the election outcome, China's main response will be wait-and-see, as it will react to actual policy changes rather than just potential shifts within Congress. The main potential trigger points would be Taiwan arms sales, tariffs and other trade/investment restrictions.
Personal ties between the two leaders appear good and if the Republicans retain control of Congress, Trump's attention will be spread across a broader range of issues. This would make rocking the boat with China appear a little less likely. However, if President Trump is constrained by a Democrat-controlled Congress, then his focus will be channelled towards foreign and trade policy, meaning China could end up in the crosshairs again. The trade truce is set to expire in January, and it seems like both sides are not interested in going back to the mutually destructive peak tariff scenario we had in 2025, but it cannot be ruled out. If the Democrats win both the House and the Senate, it would send a signal to China that it is time to start looking beyond 2028, triggering a revaluation of its long-term US strategy.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment