

Polish Rate Hike Odds Are Rising, But Policymakers Are In No Rush


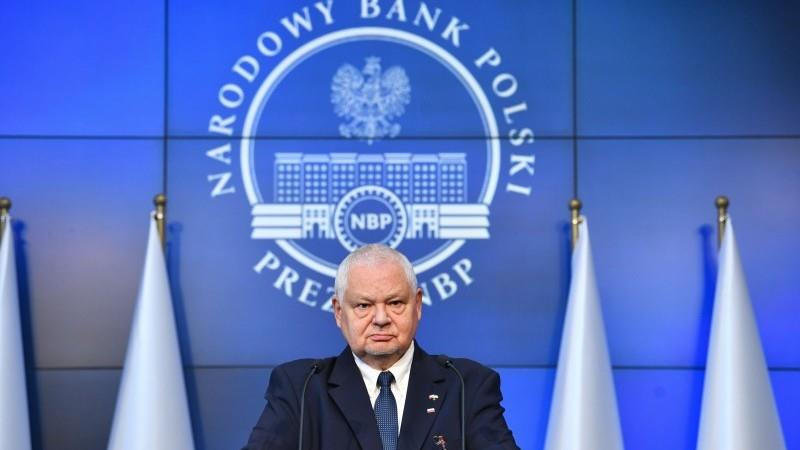
During his October press conference, National Bank of Poland (NBP) Governor Adam Glapiński highlighted growing risks to the inflation outlook. At the same time, however, he stressed that the rise in prices so far has been driven by an external supply shock and that there is little evidence of higher energy costs spreading broadly to the prices of other goods and services.
Global sources of inflationExplaining the rationale behind the October decision to leave interest rates unchanged, NBP Governor Adam Glapiński stressed that the global economy is facing an energy shock resulting from the conflict in the Middle East. The conflict is becoming more protracted, and its inflationary effects are intensifying. Polish inflation rose above the upper bound of the NBP's tolerance band around its target in September (2.5%; +/-1 percentage point), but it should return to that range in October.
Local inflationary factors are in playIn the governor's view, the inflation outlook is subject to greater uncertainty due to the geopolitical tensions. Moreover, the cuts to fuel excise duty and VAT are temporary and, at present, are expected to remain in place until the end of 2026.
Adam Glapiński also listed a number of risk factors that could contribute to broader-based price increases:
Consumer demand is solid, while wage growth in the corporate sector is running at around 6% year-on-year. Economic conditions are improving in Poland's external environment, including in Germany. Global agricultural commodity prices are rising, which could lift inflation in Poland in the future. Fiscal policy remains expansionary. Strong growth in producers' prices (PPI) may signal mounting cost pressures.He therefore reiterated that the main Monetary Policy Council (MPC) objective is to prevent higher fuel prices from spilling over into other prices across the economy.
Inflation still primarily driven by a supply shock, no second-round effectsBalancing the risks outlined above, the MPC chairman also emphasised that almost all the increase in inflation to date has resulted from higher fuel prices. In September, energy accounted for 60% of inflation, while the pass-through from energy prices to other prices has remained limited. The increase in core inflation excluding food and energy since the beginning of the year has been modest, and core inflation probably edged down slightly in September. There are also currently no signs of second-round effects.
Monetary policy guidanceFuture central bank decisions will depend on incoming data and the shape of the November macroeconomic projection. Governor Glapiński does not currently see a need for an interest rate increase at the next meeting in November, although he did not rule one out entirely. He added that the MPC stands ready to act should inflation risks continue to mount.
Our rates view still assumes 50bp hikes in 1Q27The tone of the governor's press conference suggests that the MPC remains patient and is not inclined towards a rapid and decisive tightening of monetary policy for as long as inflation continues to be driven by an external shock and there are no visible signs of higher energy prices feeding more broadly into the prices of other goods and services.
In our view, the Council still has time to respond, and the tone of the October conference was in line with our monetary scenario. If the energy shock proves more persistent, interest rate increases could come in the first quarter of 2027, when we expect two 25bp hikes. We see a risk of a modest increase in core inflation around the turn of 2026-27, which in our view would warrant a precautionary rise in interest rates.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment