


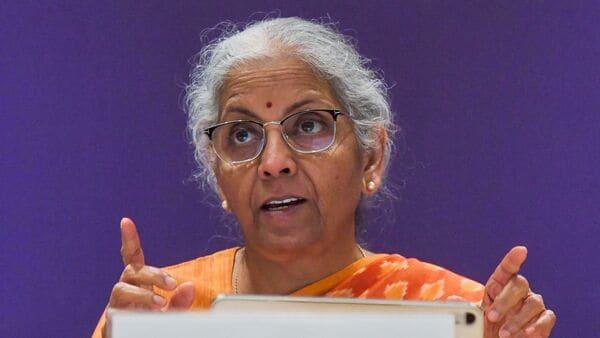
GST Council Approves Concept Note For Optional Quarterly Tax Payment For Small Businesses


Under the proposed scheme, eligible businesses would be required to file only one annual return while making tax payments on a quarterly basis.
The detailed framework of the proposed scheme will be placed before the GST Council for consideration at its next meeting, Sitharaman said.
Quick answers to key questions
.5 QUESTIONS1Who is eligible for the proposed optional GST quarterly payment scheme?⌵The proposed scheme is for businesses with annual turnover of up to ₹5 crore that supply exclusively to consumers.
2How would GST returns and tax payments work under the proposed scheme?⌵Eligible businesses would file one annual return and make GST payments quarterly.
3Is the quarterly GST payment scheme mandatory for small businesses?⌵No. The scheme has been proposed as an optional compliance scheme.
4Has the GST quarterly payment scheme been finalised?⌵No. The GST Council approved a concept note, and the detailed framework is due to be considered at its next meeting.
5Why has the GST Council proposed a quarterly payment scheme for small businesses?⌵The proposal is part of measures aimed at simplifying GST administration and reducing compliance burdens for small businesses.
In a post on X, Sitharaman said:“Today, we have distributed a concept note on an optional scheme for businesses with a turnover of up to ₹5 crore, supplying only to consumers. So, this will entail filing only one annual return with quarterly tax payments. The detailed framework will come for a decision before the next Council meeting.”
Also Read | NRI home loan after RBI rate hike: Should borrowers increase down payment? 57th GST Council meeting: Major GST process changes approvedThe decisions were taken at the 57th GST Council meeting, where the Centre and states approved a series of changes aimed at simplifying GST administration and reducing compliance burdens.
Among the key decisions, the Council approved measures to remove GST officers' power to arrest taxpayers in cases covered by the reform, raise the threshold for criminal prosecution to ₹5 crore and speed up the processing of most GST refunds.
The Council also approved measures to simplify GST registration for small suppliers seeking to sell through e-commerce platforms. The reforms include an easier procedure for making amendments to GST registration details and a reduction in penalties.
GST refund process to become fasterThe Council has approved changes aimed at reducing the time taken to process GST refund applications.
Under the revised process, the acknowledgement period will be reduced from 15 days to 10 days, Sitharaman said.
If neither an acknowledgement nor a deficiency memo is issued within 10 days, the refund claim will be treated as acknowledged.
"Based on risk assessment, it is expected that the system will sanction 90 per cent of all the claims within 3 working days of acknowledgement," Sitharaman added.
The government expects the new framework to enable faster refunds, with most eligible claims targeted for processing within three days under the broader reform package.
Also Read | UPI MDR: Who decides implementation and enforcement of MDR caps? Committee to examine protection for genuine buyersThe GST Council has also decided to set up a Committee of Officers to examine the transition towards invoice matching for input tax credit claims.
The committee, which is expected to submit its report within three months, will examine how genuine buyers can be protected when they possess a valid invoice, have received the goods and have made full payment to their suppliers.
The move is aimed at addressing concerns faced by businesses that have complied with their obligations but could potentially face difficulties because of issues on the supplier's side.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment