


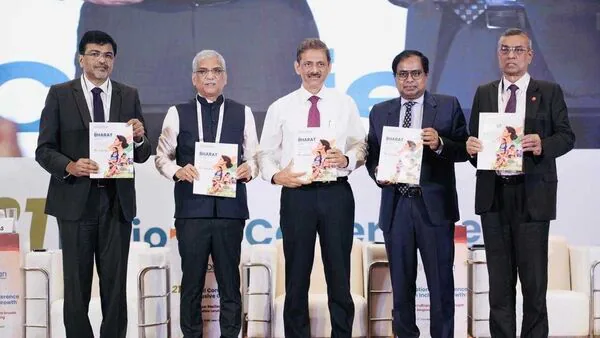
Microfinance Shows Early Recovery Signs, But Legacy Bad Loans Weigh On Sector


Sa-Dhan is an RBI-appointed self-regulatory organisation (SRO) for microfinance institutions.
The report, however, cautioned that the recovery remains tentative. While stress in the current loan book has eased sharply, legacy stressed assets continue to weigh on the sector, with the share of loans overdue by 180 days or more rising to 17.04% in March 2026 from 10.67% a year earlier.
The report said the number of loan accounts fell 21% to 10.40 crore at the end of March 2026, from 13.18 crore a year earlier. The contraction in loan accounts, alongside the 11% decline in outstanding credit, reflects the cautious approach adopted by micro-lenders following two years of high credit stress, concerns over household indebtedness and borrowers taking loans from multiple lenders.
Also Read | Finance ministry to review financial inclusion schemes with PSU bank chiefs“FY2025–26 can be characterised as a period of consolidation and recalibration, with lenders focusing on strengthening portfolio quality, controlling borrower indebtedness, improving collections and restoring sustainable credit growth. The third set of guardrails from industry leaders and SROs, issued in April 2026, have strengthened credit discipline. The sectoral outlook is expected to further improve in the current financial year," said Jiji Mammen, executive director and chief executive officer (CEO), Sa-Dhan.
At the same time, the report said the rise in outstanding loans in the January-March quarter indicates that new lending has begun to exceed repayments, marking the onset of a fresh growth phase.
Asset quality improvementAsset quality also showed a sharp improvement in the current book. Portfolio at risk (PAR) of 30-179 days past due declined to 2.34% in March 2026 from 6.63% a year earlier, while PAR of 90-179 days stood at 1.45%, down from 3.92%.
In microfinance, a loan is typically considered at risk after 30 days of missed payment due to the lack of physical collateral.
However, the improvement does not represent a complete resolution of the sector's stress, the report said. PAR of 180 days and above increased to 17.04% from 10.67%, pointing to an ageing pool of legacy defaults even as repayment performance on the current book improved.
“The portfolio dynamics between March 2026 and March 2025 reveal a clear structural split,” the report said, describing a rapid recovery in active repayment behaviour alongside an accumulation of legacy defaulted loans.
Also Read | Irdai not in favour of delaying insurance commission caps: Swaminathan IyerThe report also points to a significant reduction in borrower-level multiple lending. Restrictions limiting borrowers to no more than three micro-lenders and capping total household indebtedness at ₹2 lakh resulted in 92.6% of unique active borrowers being associated with two or fewer lenders in March 2026, compared with 90.5% a year earlier.
More significantly, the share of borrowers associated with five or more lenders fell to 0.1% from 1.6%, suggesting that the tighter lending guardrails have materially reduced high-risk multiple borrowing.
The adjustment has been broad-based. Loan accounts declined in 33 states and Union territories, with some of the largest microfinance markets seeing particularly sharp contractions. Karnataka recorded a 28% decline, followed by West Bengal at 24%, Tamil Nadu at 23%, Bihar at 22% and Uttar Pradesh at 17%.
More cautious assessmentThe report's assessment of the next phase is more cautious. It said the improvement during FY26 was supported by better harvests, food disinflation, stronger employment and remittances, monetary easing and credit guarantees. These factors helped improve household incomes, funding conditions and portfolio quality.
But several of those favourable conditions cannot be assumed to persist, the report cautioned. Inflation has begun rising again, the 2026 monsoon has been below normal in districts with high borrower density and the guarantee facility has expired.
Also Read | Easy money era is ending, interest rates to stay high: French economist LandauClimate variability has emerged as a particularly important medium-term risk because its impact can be simultaneous across borrowers in a district, unlike conventional credit risk, which is generally dispersed across individual borrowers. Through 12 August 2026, cumulative rainfall was 12% below the long-period average, with the eastern and north-eastern regions-where borrower density is high-facing materially larger shortfalls than the national figure.
The report also highlights the uneven financial performance of micro-lenders. Operating cost stood at 8.47% in 2026, up from 7.09% in 2025. Larger institutions demonstrated stronger capacity to absorb costs and generate returns, while several smaller and mid-sized institutions remained under pressure on profitability, return on assets and return on equity.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept
any responsibility or liability for the accuracy, content, images,
videos, licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright
issues related to this article, kindly contact the provider above.


Comments
No comment