

RBI's Tighter Policy Sinks Sensex 300 Pts, Nifty Below 22,550


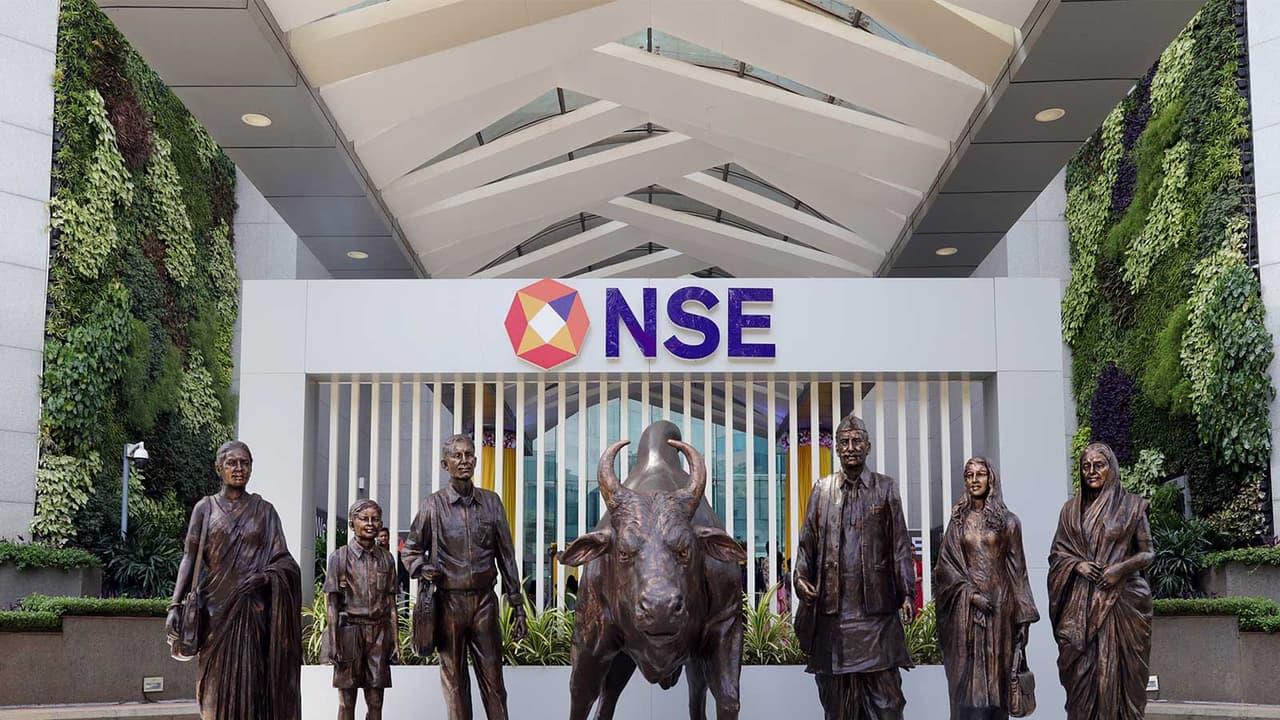
Indian benchmark indices opened on a subdued note on Thursday following the RBI's policy announcements, with the Sensex slipping over 300 points and the Nifty tumbling below the 22,550 level, as the central bank's shift towards tighter monetary policy weighed on investor sentiment.
Nifty opened with a marginal gap-down at 22,599.05 and was trading at around 22,487.05, down 116 points or 0.51 per cent against the previous close of 22,603.05 at the time of reporting. Sensex, on the other hand, opened at 72,668 and was trading at around 72,303.45, down 335.25 points or 0.46 per cent against the previous close of 72,638.70 at the same time.
Sectoral Performance
All broad market indices traded in the red; among sectoral indices, Nifty IT emerged as the major gainer, surging 1.93 per cent followed by Telecom (1.39 per cent) during early morning trade, while most other indices traded in the red. On the other hand, Nifty Realty and Financial Services emerged as top drags, declining over a per cent.
Top Movers on Exchanges
On NSE, TCS, Tech Mahindra, HCL Tech, Infosys, Sun Pharma, Titan, Trent, Cipla, HSFC Life, Bharti Airtel, among others were the top gainers. SBI Life, Bajaj Finance, Bajaj Finserv, NTPC, Coal India, Eternal, TMPV, among others, were the top laggards.
On BSE, TCS, Tech Mahindra, HCL Tech, Infosys, Sun Pharma, Trent, Titan, Bharti Airtel, among others, were top gainers. Bajaj Finance, ITC, BEL, Bajaj Finserv, Adani Ports, Indi Go, M & M, Tata Steel, SBIN, LT, among others, were the top drags.
Commodity Market Update
In the commodity market, Brent crude was trading at around USD 102.34 per barrel while crude oil was trading at around 89.81 per barrel, at the time of reporting.
Expert Commentary: Cautious Outlook
Ponmudi R, CEO, Enrich Money, noted,“The outlook for Indian equities remains cautious after the RBI raised its repo rate to 5.50%, tightening domestic financial conditions at a time when global markets are already contending with elevated Treasury yields and geopolitical uncertainty. Tighter domestic financial conditions and a fragile global risk backdrop could keep investors defensive.”
As per Ponmudi, currency weakness remains another headwind.“The rupee continues to trade under pressure, while the U.S. 10-year Treasury yield remains elevated near multi-decade highs, keeping global financial conditions restrictive,” he said, adding,“Foreign investors have also remained persistent sellers for several weeks, limiting the support that could otherwise cushion the impact of tighter domestic monetary policy. Unless FII flows show signs of stabilizing or US yields retreat, domestic equities are likely to remain vulnerable to further selling pressure, particularly if expectations of additional RBI tightening build.”
Market analyst Vipin Dixena noted, Indian equities are likely to remain under pressure today after the RBI raised the repo rate by 25 bps to 5.5% and shifted its stance from neutral to“calibrated tightening.”
“The other concern for me is the continued foreign selling. The market now enters the Q2 earnings season, with TCS kicking it off today,” Dixena added.
Technical Levels to Watch
Technically, as per the analyst, 22,500–22,400 is the immediate support zone.“A break below this can bring 22,200 back into focus. On the upside, 22,800 remains the key hurdle; only a decisive breakout above this level would improve the short-term structure and open the way towards 23,000,” he said. (ANI)
(Except for the headline, this story has not been edited by Asianetnews Editorial staff and is published from a syndicated feed.)
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment