

France's National Rally Fiscal Plan Faces Major Delivery Risks


As discussed in our previous article, the government's proposed budget would limit the deterioration in the public finances in 2027, but it would not stabilise the debt ratio or provide a lasting solution. Attention is therefore increasingly turning to the fiscal policies that could follow the presidential election. With the National Rally (RN) currently well ahead in first-round polls, its programme matters not only as an opposition proposal, but as a possible framework for policy after 2027.
Figures that are often difficult to justifyThe programme's detailed breakdown is an improvement on previous proposals and confirms that the National Rally recognises the need for fiscal consolidation. However, several measures lack a clearly defined base or mechanism, or depend on legal changes and international agreements.
Fraud estimates illustrate the issue. The programme assigns €18bn a year to a new VAT collection mechanism, although the total VAT gap is estimated at €9bn to €15bn and includes errors, omissions and bankruptcies, not only recoverable fraud. Other figures are similarly uncertain. The plan projects €4.2bn in annual savings from an unspecified reform of short-term Treasury bill management and €4.4bn in motorway revenue from 2028, although the main concessions expire only between 2031 and 2036 and an early buyout would cost an estimated €45bn to €50bn.
State rationalisation is expected to yield almost €28bn from 2027, but closing public bodies, reorganising departments and reducing staff take time and entail transition costs. The proposed cut in France's EU budget contribution – €11bn in 2027 and around €19bn annually thereafter – could not be decided unilaterally. Changing the EU's own-resources system would require unanimous agreement and ratification by all member states.
The plan targets €37bn in social security savings, although the detail and deliverability of this amount remain uncertain. Pensions are another major uncertainty. The RN expects €15bn in savings from tightening the contribution period required to validate a quarter, which it says would offset the €10bn cost of lowering the retirement age to 60 or 62. Independent estimates, however, put the cost of the age change alone at €25bn to €35bn per year.
Overall, some savings appear plausible, but not all of them and the largest items are also the least well documented. This matters all the more because the RN's plan combines fiscal consolidation with €69.3bn of tax cuts and new spending in 2027 alone. This includes €53.2bn in revenue cuts, notably lower taxes on energy and essential goods and the removal of several production taxes, as well as €16.1bn in new expenditure. Delivering a large improvement in the fiscal balance while financing measures of this scale therefore requires the savings and additional revenues to materialise rapidly and almost in full.
Overly optimistic macroeconomic assumptionsThe programme's main weakness, however, lies in the macroeconomic framework into which it is incorporated. Almost half of the adjustments would be delivered in 2027, with a net improvement in the fiscal balance of around €66bn in a single year. Fiscal tightening on this scale would inevitably weigh on demand and economic activity and, in turn, on tax revenue.
Yet the programme assumes GDP growth of 0.9% in both 2026 and 2027, followed by an acceleration to 1.8% in 2028, despite most of the fiscal adjustment taking place at the beginning of the presidential term. This trajectory appears difficult to achieve. It assumes that the fiscal shock would have almost no effect on activity in 2027 and that any consequences would fade very quickly thereafter.
Indeed, the document assumes a cumulative contractionary effect of only 0.5 percentage points from the spending cuts. This implies a fiscal multiplier of around 0.13, well below the range of 0.5 to 1.5 generally found in the economic literature. Under more conventional assumptions, the negative effect could amount to several percentage points of GDP. Part of the initial savings would then be partially offset by lower tax revenue and higher social expenditure.
At the same time, the programme assumes that tax cuts, purchasing power measures and competitiveness reforms would add 2.8 percentage points to cumulative growth over five years (2027-32). After a contractionary effect of only 0.5 points, this produces a net gain of 2.3 points over five years. This is an unusually favourable combination of small and short-lived fiscal costs with large and rapid supply-side benefits.
The interest-rate assumptions are also favourable. The programme assumes an average refinancing rate of 4.5% in 2026 and 2027, falling to 3.8% from 2028. It also assumes that restored fiscal credibility will reduce the OAT-Bund spread to between 40 and 50 basis points, lowering France's financing costs by 90 basis points. However, such an improvement would not be automatic. It would depend on the government's ability to secure approval for the programme and implement it, its relationship with the European Union, the response of economic growth and the broader interest-rate environment.
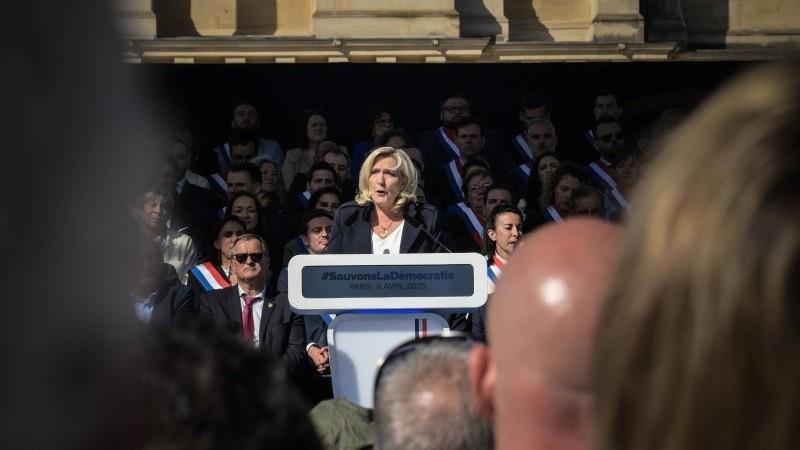
Le Pen also said that France should enter into discussions with the ECB on an intervention to ease its interest-rate burden once the public finances had been brought under control. The nature of the requested intervention remains unclear, however, and sits uneasily with the programme's assumption that fiscal credibility alone would mechanically reduce the OAT-Bund spread by around 90 basis points.
A potentially reassuring fiscal ruleOne potentially constructive element is the proposed constitutional“golden rule”. If approved by referendum, it would require the deficit to remain below the level needed to stabilise the debt-to-GDP ratio, and a further 0.5 percentage points below that threshold for as long as public debt remained above 60% of GDP.
Such a rule could strengthen France's fiscal framework and help reassure markets by imposing a constraint on future deficits. But it would not generate the required savings by itself. Its effectiveness would depend on its legal design, approval and enforcement, as well as on the government's ability to adopt measures consistent with the rule.
A trajectory subject to substantial delivery risksOverall, the document sets out a sizeable fiscal consolidation objective and identifies a broad range of potential savings. Nevertheless, the plan in its current form would probably not be sufficient to resolve France's public-finance challenges. A significant share of the announced savings is unlikely to be realised in full or within the stated timeframe, owing to legal, institutional and implementation constraints as well as the macroeconomic effects of the adjustment. The resulting improvement in the fiscal balance would therefore probably be smaller than projected, especially as the RN's plans also incorporate additional spending.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment