

403
Sorry!!
Error! We're sorry, but the page you were looking for doesn't exist.
US Markets Watch Oil Prices, Services Data And Fed Signals Elevate Financial Services Market Report


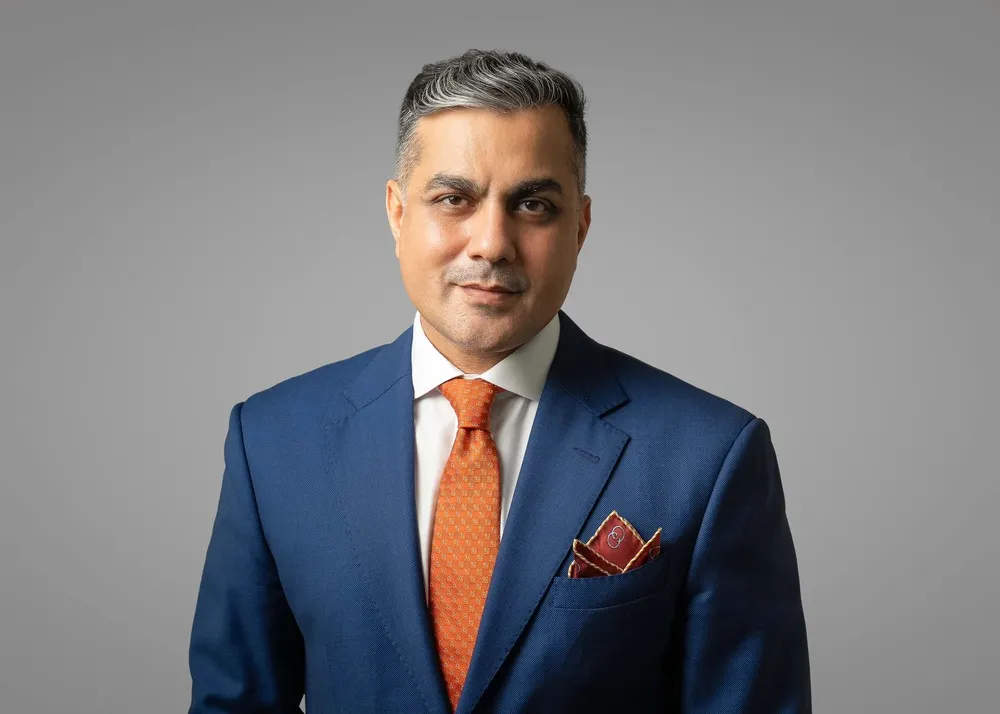
(MENAFN- Mid-East Info) Madhur Kakkar, Founder & CEO, Elevate Financial Services
Borderless Finance. AI-Native.
Your digital companion for smarter everyday choices. Built for how you live, earn, and grow. Move money at your pace with AI-powered finance, all in one tap.
Join the waiting list. Earn Key Market Themes This Week:-
Oil prices remain a key inflation risk: Supply conditions, Middle East developments and US crude inventories could influence energy prices, inflation expectations and Treasury yields.
Services data takes centre stage: ISM Services and final S&P Global Services PMI will provide fresh signals on business activity, prices and the strength of the US economy.
FOMC minutes offer policy clues: The September meeting minutes will provide further insight into policymakers' views on inflation, energy prices and labour-market conditions.
Treasury auctions test demand: The 3-year, 10-year and 30-year Treasury auctions could provide signals on investor demand and pressure on longer-term yields.
Labour-market data remains important: Initial jobless claims will offer another read on employment conditions as investors assess the pace of labour-market moderation.
Inflation expectations remain in focus: The University of Michigan's inflation expectations data could influence views on the Fed's policy path and rate-sensitive assets.
Earnings provide consumer signals: Constellation Brands, Levi Strauss, PepsiCo and Delta Air Lines results will offer insights into consumer demand, pricing, travel and corporate margins.
China's Golden Week may affect liquidity: Reduced activity across Asian markets could limit liquidity early in the week, with potential catch-up moves as regional markets reopen.
-
Lower oil prices could ease inflation concerns, support lower Treasury yields and benefit rate-sensitive sectors.
Higher crude prices could lift inflation expectations and Treasury yields, creating pressure on high-valuation technology stocks and other growth sectors.
Energy stocks could benefit from sustained oil-price strength, while higher input costs could weigh on consumer and transport businesses.
Further geopolitical or supply disruptions could increase short-term market volatility.
-
Strong services activity alongside contained prices could support equities and reinforce expectations for a soft landing.
Strong activity combined with elevated prices paid could push Treasury yields higher and increase pressure on rate-sensitive sectors.
Weaker services activity could raise concerns around economic growth, particularly if employment indicators also deteriorate.
The combination of services growth and price pressures will remain important for expectations around the Fed's policy path.
-
Greater confidence around moderating inflation and a cooling labour market could support expectations for eventual policy easing.
Concern around energy-driven inflation or persistent services prices could reinforce a cautious Fed stance.
A hawkish interpretation of the September meeting could lift Treasury yields and weigh on growth and other rate-sensitive sectors.
Fed commentary alongside incoming data will remain important for expectations around the timing and pace of future rate moves.
-
Strong auction demand could help contain Treasury yields and support rate-sensitive equities.
Weak demand could push yields higher, particularly at the long end of the curve.
Higher long-term yields could place pressure on high-multiple technology stocks, homebuilders, utilities and REITs.
Auction results will also provide insight into how investors are positioning around inflation and the Fed's policy outlook.
-
Higher claims could support lower Treasury yields initially as markets price weaker labour conditions.
A sharp deterioration in employment indicators could increase concerns around economic growth and corporate earnings.
Stable or lower claims would support the view that labour-market conditions remain resilient.
The broader interpretation will depend on how claims interact with services activity, inflation and Fed policy signals.
-
Contained inflation expectations could support Treasury yields and reinforce expectations for gradual policy easing.
Higher inflation expectations could increase concerns around persistent price pressures and support a more cautious Fed stance.
Weak consumer sentiment alongside rising inflation expectations could raise concerns around household purchasing power and economic growth.
-
Lower oil prices, softer ISM prices-paid and contained inflation expectations: Treasury yields and the US dollar may decline, supporting the Nasdaq, semiconductors, REITs, small caps, utilities and gold.
Strong services activity with elevated prices-paid: Treasury yields may rise, creating pressure on high-multiple technology stocks and other rate-sensitive sectors.
Hawkish FOMC minutes or weak Treasury-auction demand: Longer-term yields could move higher, weighing on growth stocks, homebuilders, utilities and REITs.
Higher jobless claims and weak consumer or Delta guidance: Bonds could rally initially, while banks, airlines, industrials and small caps could face pressure from growth concerns.
Higher Michigan inflation expectations alongside higher oil prices: Markets could price a more cautious Fed stance, supporting energy stocks while creating broader pressure across equities.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment