

The Philippines' Inflation Battle Is Far From Over


Philippine inflation surprised sharply to the upside in September, accelerating to 7.2% YoY from 6.1% in August and exceeding our already above-consensus forecast of 6.8%. The surge was overwhelmingly driven by food prices, with non-rice food inflation accounting for roughly 75% of the 1.1 percentage point increase in headline CPI. Rice and transport inflation contributed around 10% each, suggesting that the latest upside surprise was largely the result of renewed supply-side pressures rather than a broad-based demand-driven inflation shock. While core inflation also accelerated, it remained relatively contained at 4.7% YoY.
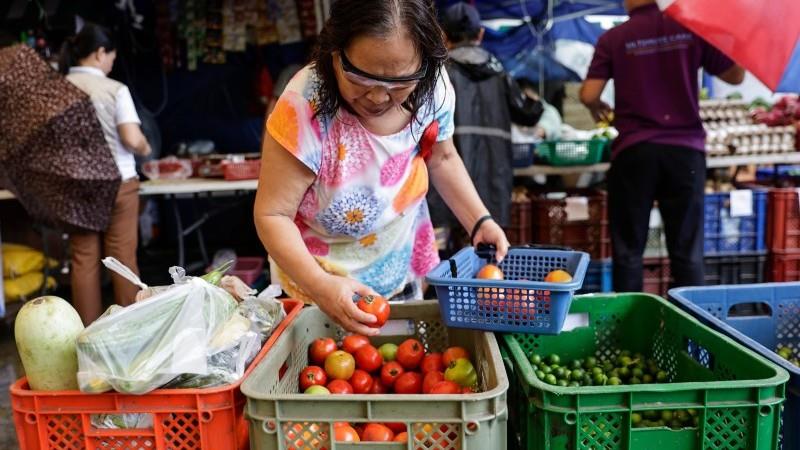
The Philippines' CPI basket is particularly sensitive to movements in food and fuel prices, with food and transport together accounting for around 50% of total CPI weights. Food inflation accelerated to 6% YoY as early as April and has remained elevated in the 6-7% range since then. Rice inflation has also proven sticky despite efforts to stabilise domestic supply conditions. More notable, however, was the sharp rebound in non-rice food inflation in September. The rebound points to a broadening of food price pressures beyond rice, with stronger inflation transmission to cereal and related food products.
Food accounted for a large part of the increase in inflation Source: CEIC, ING Research"> El Niño and fuel pass-through keep inflation risks elevated
This suggests that food inflation is becoming increasingly broad-based. While El Niño-related weather disruptions are contributing to higher food prices, a significant share of the inflation transmission appears to be occurring through higher transportation and production costs linked to elevated fuel prices. External factors are also adding to pressures, including Black Sea supply disruptions and higher global corn prices resulting from weaker crop yields in the US and Europe.
As a result, inflationary pressures are spreading across a wider range of food categories rather than remaining concentrated in rice. We think the full impact of El Niño is yet to be felt and is likely to become more evident at the end of 2026 and early 2027, increasing the risk that food inflation remains elevated for longer and entrenching a more persistent inflation cycle.
What stands out when comparing the Philippines with its regional peers is the much stronger pass-through from global oil prices to domestic fuel prices. While countries such as Indonesia and India have experienced far smaller increases in retail fuel prices, the Philippines has seen a much larger transmission of higher global energy costs to consumers. As a result, fuel inflation has been a more significant driver of headline CPI in the Philippines, amplifying second-round effects on other goods and services, whereas these spillover effects have remained more contained in neighbouring economies.
Gasoline price hikes across the region Source: CEIC, ING Research"> A rate hike is likely in October's policy reviewWe maintain our call for Bangko Sentral ng Pilipinas to hike rates by 25bp in the fourth quarter of this year. Today's strong inflation print has shifted the balance in favour of an earlier hike in October.
The inflation outlook remains skewed to the upside amid lingering uncertainty over El Niño-related food supply disruptions, elevated energy prices, PHP weakness, and potential second-round effects from higher wages and food costs. BSP is likely to err on the side of caution and maintain a tightening bias to contain inflation expectations until it is confident that inflation is on a durable path back to target.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment