

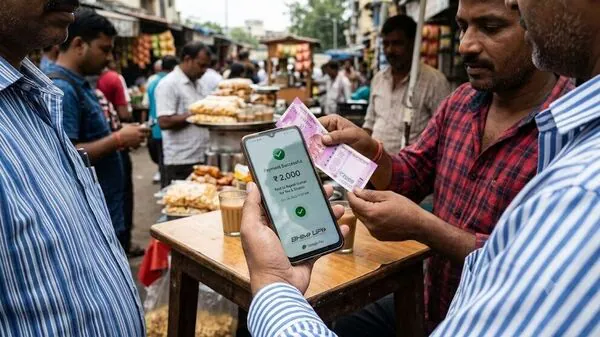
UPI Sets Charges For Merchant Payments Above ₹2,000, Caps Fee At ₹300


For transactions of ₹75,000 and above, the MDR will be capped at ₹300 per transaction, the ministry said in a statement.
The announcement brings to a close months of discussions over charges for higher-value UPI transactions. The new framework follows the government's decision on Monday to keep UPI transactions of up to ₹2,000 free of MDR, with banks and payment system providers barred from imposing direct or indirect charges on such transactions.
Only 4% of merchant transactions will be affected by the introduction of MDR, according to the statement, as most transactions either fall below the ₹2,000 threshold or qualify for zero MDR under the P2PM framework for small merchants. Also Read | NPCI set to break UPI AutoPay lock-in
“P2P transactions constitute 37% of the total UPI transactions in volume terms and 70% in value terms," the finance ministry said in a release. It added that the decision followed deliberations by NPCI's UPI steering committee on operational parameters, fee distribution models and category caps.
The ministry also clarified that no transaction fee, platform fee or other charge can be imposed on individuals sending or receiving money through UPI. Small merchants, including street vendors and neighborhood shops, receiving up to ₹1 lakh a month through UPI QR codes under the person-to-person-merchant (P2PM) category will continue to be covered by the zero-MDR framework.
Further, auto-debit recurring payments like utility bills or mutual fund subscriptions, known as UPI Mandates or AutoPay, will not carry the prescribed MDR transaction charges.
The new MDR framework and threshold structure will come into effect from 15 October, giving acquiring banks, payment aggregators, fintech applications and corporate accounting platforms time to update their software engines and billing systems, according to the statement.
While the framework is a step towards building a sustainable revenue model for UPI, the more important question is whether that revenue is shared fairly across all the players involved, said Kunal Jhunjhunwala, founder of Airpay Payment Services.
“Fintechs, in particular, have driven digital payments deep into the merchant base, often in segments banks found harder to reach, and have invested heavily in the technology and infrastructure that made that possible. That contribution needs to be recognized in how the model is structured, not treated as a footnote.”Jhunjhunwala said fintechs have just a month to explain the new cost to merchants, help them get comfortable with it, and make the backend changes needed to support it.“That's a short runway for a change with this much reach.”
Quick answers to key questions
.5 QUESTIONS1What is the new Merchant Discount Rate (MDR) for UPI transactions above ₹2,000?⌵The new MDR for person-to-merchant (P2M) UPI transactions above ₹2,000 is set at 0.4%, capped at ₹300 for transactions of ₹75,000 and above.
2Why has the government introduced MDR on higher-value UPI transactions now?⌵The introduction of MDR aims to create a sustainable funding mechanism for the UPI system, as the operational costs have previously been borne by banks and payment service providers.
3How will the MDR be distributed among UPI ecosystem participants?⌵The MDR will be distributed among various stakeholders, including banks and payment service providers, to support infrastructure investments, cybersecurity, and customer service enhancements.
4Will person-to-person (P2P) UPI transactions continue to be free?⌵Yes, person-to-person (P2P) UPI transactions will remain free of any charges, even with the introduction of MDR for higher-value merchant transactions.
5What impact will the MDR changes have on small merchants using UPI?⌵Small merchants receiving up to ₹1 lakh monthly through UPI QR codes will continue to benefit from the zero-MDR framework, ensuring their transactions remain free.
India's UPI platform processed 241.6 billion transactions worth ₹314.2 lakh crore in FY26, up 30% from a year earlier in volume and 21% in value. UPI had more than 55 crore users as of August 2026, according to NPCI data.
The platform processed 24.5 billion transactions worth ₹29.8 lakh crore in August 2026, up 22% in volume and 20% in value from a year earlier. P2M transactions accounted for 30% of total UPI transaction value in August, with transactions of up to ₹500 accounting for 16% and those between ₹501 and ₹2,000 for 17%.
In volume terms, P2M transactions accounted for 63% of UPI transactions, of which 86% were below ₹500 and another 10% were between ₹501 and ₹2,000, according to the latest NPCI data.
“UPI's success was built on zero-cost adoption by consumers, small shopkeepers, and micro-enterprises, and the notified MDR framework preserves that foundation. We are reassured that small-value transactions up to ₹2,000 comprising over 95% of UPI P2M volume remain zero MDR, ensuring everyday payments stay free for consumers,” said Girish Krishnan, director, payments, rewards and merchant services, Amazon Pay India.
Also Read | 10 years of UPI: India's digital payment revolution continues at rapid pace Cost competitivenessTransactions above ₹2,000 in essential and thin-margin sectors, including railways, telecommunications, insurance, fuel, utility-bill payments, educational fees and agricultural inputs, will attract a flat MDR of ₹5 per transaction. Payments relating to mutual funds, securities, stockbrokers and dealers will attract an MDR of 0.02%, capped at ₹300 per transaction.
The ministry clarified that MDR is neither a tax nor a charge collected by the government or NPCI. It will instead be distributed among ecosystem participants, including banks, payment service providers and UPI application providers.
Vishwas Patel, managing director and CEO, AvenuesAI, and chairman, Payments Council of India (PCI) called the move an important step towards a viable economic model.“UPI needs a sustainable economic model to support its scale. The continued growth of UPI requires banks, fintech companies, payment aggregators and other ecosystem participants to make sustained investments in infrastructure, cybersecurity, fraud prevention, technology and customer service,” he said.
According to the NPCI FAQ, the MDR will be used to invest in infrastructure resilience, innovation, cybersecurity and customer service. The intent is to keep UPI accessible and convenient for everyday transactions while supporting the long-term sustainability of the ecosystem.
Individuals will continue to have unlimited free usage of UPI, with no monthly quotas, volume restrictions or tiered caps on free transactions.
The UPI MDR is structured to be much lower than traditional card-based transaction fees. Standard credit card MDRs typically range from 1.5% to 2.5% per transaction, while debit card MDRs are capped at up to 0.90%.
“UPI remains the most affordable digital payment acceptance tool for commercial enterprises. This cost difference helps merchants lower their payment processing expenses while accepting digital transactions,” NPCI said.
Dedicated fund for small merchantsNPCI also notified that 5% of the total MDR earned will be set aside in a dedicated fund for small merchants. The fund will be used to subsidize and accelerate digital payment infrastructure in Tier 3-6 centres, including the North-East states, Jammu & Kashmir and Ladakh, as well as in Tier 1 and 2 centres.
The fund will also support some notified central government schemes.
Also Read | VCs look past payment figures to spot 'dead users' hiding in UPI autoPay metrics“This fund will also be utilized to extend financial assistance to the ecosystem players for merchant onboarding and incentivize growth of UPI transactions among existing small merchants,” NPCI said.
The fund will provide incentives for UPI transactions originating from small merchants, particularly in rural areas and Tier 3 centres and beyond, to encourage sustained usage, increase digital payment penetration and accelerate the inclusion of small businesses in the digital payments ecosystem.
The detailed framework for the fund will be finalized in consultation with the Reserve Bank of India within the next three months.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment