

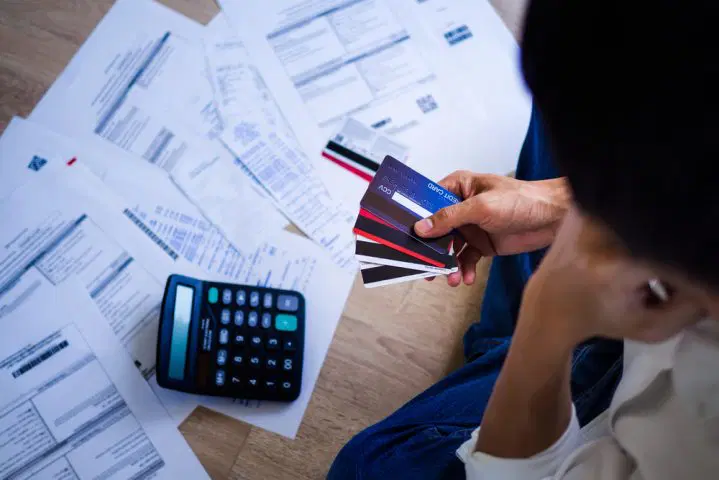
You Paid Off $10,000 In Credit Card Debt. How Much Did Your Credit Score Actually Change?


Paying off $10,000 in credit card debt can feel like a financial mic drop, but your credit score may not respond with the dramatic standing ovation you expected. The reason comes down to how credit scoring models look at your entire credit profile, not simply the dollar amount you just erased.
There is no universal“$10,000 payoff equals 50 points” formula. Your score could rise significantly, move only a little, or barely budge at first, depending on your credit utilization, payment history, account age, other balances, and which scoring model a lender uses.
The $10,000 Matters Less Than What It Did to Your Credit UtilizationImagine a person carrying a $10,000 balance on a card with a $12,000 credit limit. That person uses roughly 83% of the available credit on that card, which can make the account look heavily utilized to a scoring model.
Now imagine that same balance reaches $0 after an aggressive payoff. The utilization on that card drops to zero, and the person's overall utilization can fall dramatically too, depending on the limits and balances on other cards. Credit scoring models consider how much revolving credit a person uses compared with how much credit remains available, so a large payoff can make a meaningful difference when it substantially lowers that ratio.
Why One Person Could Gain More Points Than AnotherTwo people can each erase $10,000 of credit card debt and see completely different results. Someone who started with nearly maxed-out cards could see a more noticeable improvement because the payoff changes a major part of the information feeding the score.
Someone else might have a long, clean credit history, several cards with modest balances, and plenty of available credit already. In that case, removing $10,000 could improve the profile without creating a dramatic score jump because the person already had relatively low utilization and strong payment history. Credit scores also vary by scoring model, credit report data, and even the day someone calculates the score.
Paying Off the Debt Does Not Mean the Score Changes OvernightThere is another little wrinkle hiding behind that glorious zero balance: the credit bureaus need updated information before a scoring model can reflect the change. Card issuers generally report account information to the credit bureaus on their own schedules, so a person can make a huge payment and still see the old balance on a credit report for a while.
That timing explains why someone might pay off the debt on Monday, check a credit score on Tuesday, and wonder whether the payment got lost somewhere in the Bermuda Triangle of personal finance. The CFPB notes that scores can change based on when the score gets calculated and what balance appears in the credit report at that point.
Paying Off the Card Can Help Without Giving You a Perfect ScoreA major debt payoff can improve one important piece of the credit picture, but it cannot erase late payments, a short credit history, recent applications, or other information that affects scoring models. That matters because a credit score represents a broader record of how someone has handled credit over time.
The good news is that paying off the debt does not require carrying another balance just to“keep the credit gods happy.” That common myth can cost real money because carrying a balance can lead to interest charges, while paying cards in full can keep utilization lower and avoid unnecessary interest.
The Smart Move After the $10,000 PayoffOnce the balance disappears, the best next step usually involves keeping the accounts in good standing rather than immediately chasing another score boost. Continue making every payment on time, keep revolving balances manageable, and avoid opening a pile of new accounts simply because the score looks better.
Be careful about closing the paid-off card, too, especially if it has no annual fee and a useful credit limit. Closing an account can reduce the total amount of available credit and potentially push utilization higher, which can work against some of the progress created by the payoff.
The Real Victory Is Bigger Than the Number on the ScreenPaying off $10,000 in credit card debt can improve a credit profile, but nobody can responsibly promise a specific number of points without seeing the underlying credit information and scoring model. The bigger win comes from removing expensive revolving debt while creating more room between current balances and available credit.
That distinction matters because a credit score serves as a snapshot, while the financial benefit of eliminating high-interest debt can continue long after the score refreshes. If the payoff also frees up money that previously went toward interest and minimum payments, the person now has an opportunity to build savings, avoid new debt, and keep the newly cleared credit cards from filling right back up.
So, how much did your credit score change after paying off a big chunk of credit card debt, and did the result surprise you?
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.
Comments
No comment