


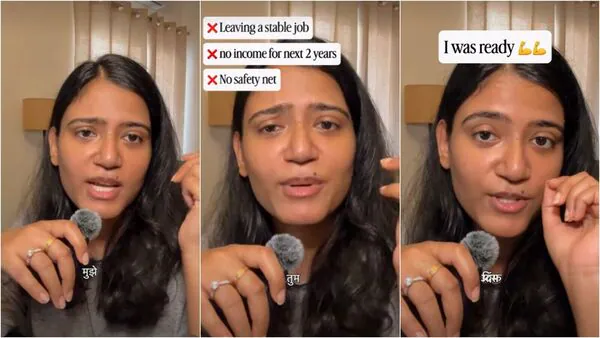
Who Is Dimple Porwal? Meet The IIM Kozhikode Graduate Who Repaid Her ₹25 Lakh Education Loan In Five Years


Porwal, who currently works at Microsoft, recently shared her repayment journey in a video on social media. She explained how planning, regular prepayments and careful use of additional income helped her close the loan a decade earlier than planned. According to her, the approach also helped her save nearly ₹10 lakh in interest.
Her story has attracted attention online, particularly among students and young professionals dealing with education loans.
Who is Dimple Porwal and why did she take a ₹25 lakh loan?Porwal pursued her MBA at IIM Kozhikode after leaving a stable job. However, funding the course meant taking on a major financial responsibility.
Also Read | ₹37 LPA salary package wasn't enough: Why an IIM graduate quit his joShe recalled that the day her education loan was approved, she could not sleep because she was thinking about the debt she would have to repay.
Being the only child of a single mother made the decision even more challenging. She also had to leave her job, which meant there would be no regular income for the next two years while she completed her MBA.
Instead of waiting until she started earning, Porwal began planning how she would repay the loan even before receiving her first salary at Microsoft.
Her bank had offered a repayment period of 15 years, but she wanted to become debt-free much sooner.
How did she repay the ₹25 lakh education loan in five years?Porwal followed five steps to bring down her loan amount and reduce the interest she would have to pay.
1. Never missed an EMI: Her monthly instalment was around ₹22,000. She made sure every payment was made on time to avoid late fees and protect her credit score.
2. Paid four additional EMIs every year: Apart from her regular monthly payments, she paid four extra EMIs annually. This meant making one additional payment every quarter, helping her reduce the outstanding loan faster.
3. Used bonuses and stock awards: Instead of spending her annual bonuses and Microsoft stock awards, she directed a significant part of this additional income towards loan prepayments.
4. Increased her EMI with salary hikes: Whenever her salary increased by 10%, she increased her monthly loan instalment by the same percentage. This helped her put more money towards the loan as her income grew.
5. Used education loan tax benefits: Porwal also used the tax benefits available on education loan interest and directed the savings towards further repayments.
How much did Dimple Porwal save in interest?According to Porwal, she paid approximately ₹4.6 lakh in interest while repaying the ₹25 lakh loan over five years. Had she continued with the original 15-year repayment schedule, the total interest would have been nearly ₹15 lakh.
This means she saved around ₹10 lakh by closing the loan early.
The tax benefit she mentioned is worth understanding. Under the earlier Income-tax Act, Section 80E allowed eligible taxpayers to claim a deduction on interest paid towards qualifying higher education loans. From 1 April 2026, the corresponding provision is Section 129 of the Income-tax Act, 2025. Eligibility and conditions apply.
Internet reacts to her repayment strategyPorwal's story has received appreciation on social media, with several users praising her financial discipline and planning. While some congratulated her on becoming debt-free, others said her approach offered useful lessons for people taking education loans.
Her message to those considering a major financial commitment is simple: believe in yourself, but have a repayment plan.
Her experience also highlights how regular prepayments, using additional income wisely and increasing EMIs with salary growth can reduce the overall interest burden.
Legal Disclaimer:
MENAFN provides the
information “as is” without warranty of any kind. We do not accept any
responsibility or liability for the accuracy, content, images, videos,
licenses, completeness, legality, or reliability of the information
contained in this article. If you have any complaints or copyright issues
related to this article, kindly contact the provider above.


Comments
No comment